


Emerson Electric (EMR) Power And LNG Narrative Keeps Valuation In Focus
Emerson Electric (EMR) has attracted fresh attention after recent share price moves, with the stock closing at $161.59. Investors are weighing this performance against the industrial group’s current financial profile and recent returns.
Emerson Electric’s recent move to $161.59 comes on the back of steady share price momentum, with a 30-day share price return of 4.53% and a 90-day gain of 9.23% contributing to an 18.97% year-to-date rise and a one-year total shareholder return of 23.70%. This builds on very strong three- and five-year total shareholder returns of 93.51% and 83.89% respectively, which suggests investors have gradually been pricing in improved prospects and a shift in perceived risk over several timeframes.
Scan other industrials with momentum similar to Emerson Electric by exploring our hand picked 42 power grid technology and infrastructure stocks.
Recent gains put Emerson Electric at a point where investors need to decide whether the share price is mainly tracking the underlying business or leaning more on changing sentiment, which is exactly what the valuation picture now tests.
Most Popular Narrative: 7% Undervalued
Emerson Electric’s most followed narrative pegs fair value at about $173.68, above the recent $161.59 close. This helps put the recent rally in context and frames why execution on key growth areas matters so much.
Large-scale investments in power generation, LNG and life sciences driven by rising energy security concerns, electrification and sustainability initiatives are driving significant greenfield and modernization projects in regions such as North America, Asia and the Middle East. This is visible in the growth in power orders, the expansion of the power project funnel to about US$3b and the US$2.2b LNG funnel, and could support revenue and operating margin resilience.
See why 60 investors see Emerson Electric as 7% undervalued.
Result: Fair Value of $173.68 (UNDERVALUED)
Still, Emerson Electric faces real pressure points as conflict related disruptions in the Middle East trim an estimated US$100m from FY2026 sales and China demand remains soft.
Find out about the key risks to this Emerson Electric narrative.
Another View On Emerson Electric’s Valuation
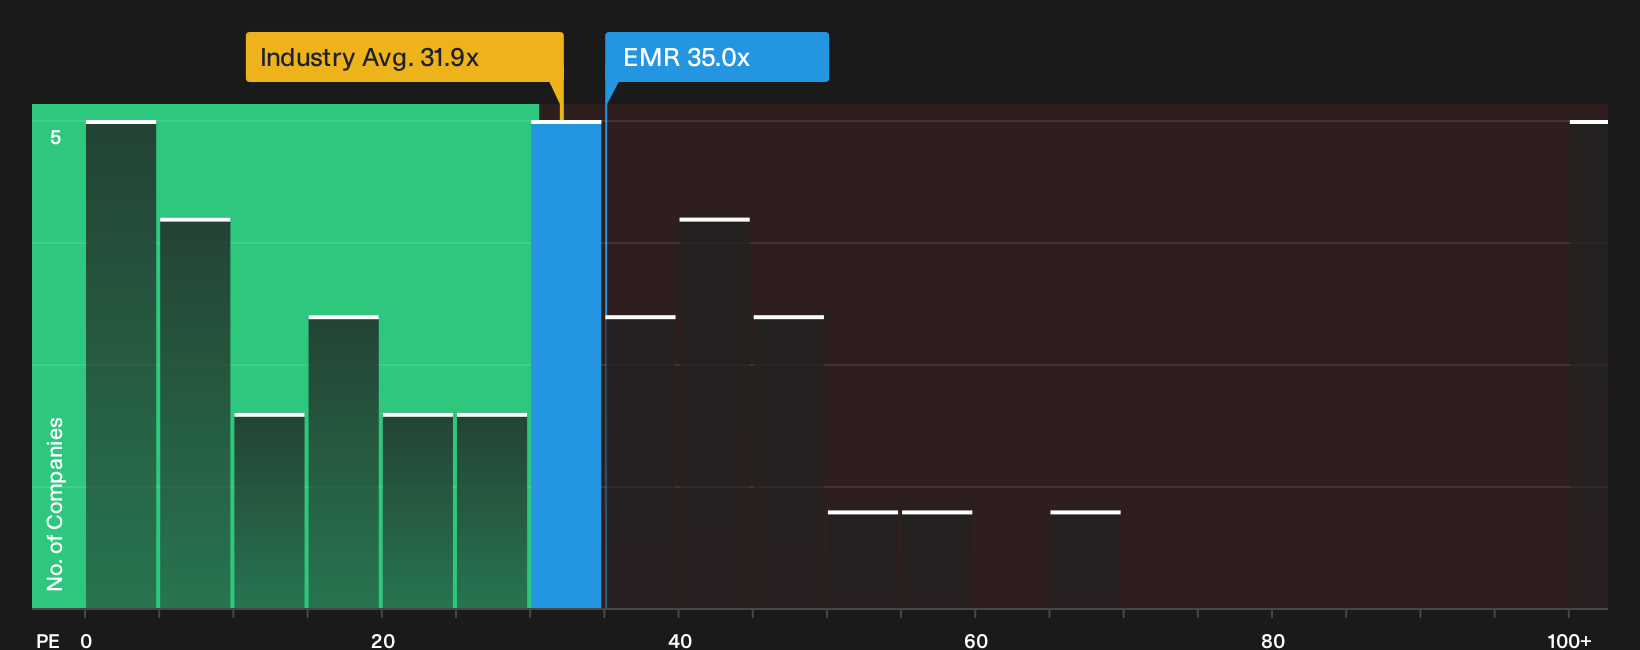
The analyst narrative points to Emerson Electric trading about 7% below a fair value of $173.68. A different lens tells a less generous story. On a P/E of 35x, the stock sits above the US Electrical industry at 31.9x and well ahead of its own fair ratio of 29.3x, which signals less margin for error if expectations soften.
That gap between the current multiple, peers and the fair ratio raises a simple question for investors: Is sentiment just running hotter than the underlying cash and earnings profile can support over time?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Emerson Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Emerson Electric’s valuation and narrative are exactly when your own homework matters most, so take a close look at both sides of the story and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Emerson Electric?
If Emerson Electric has sharpened your focus on quality, do not stop here. Use powerful screeners to quickly shortlist other potential opportunities tailored to your style.
- Target resilience by scanning a 30 resilient stocks with low risk scores that prioritises companies with lower risk scores and steadier profiles.
- Hunt for strong fundamentals with a list of solid balance sheet and fundamentals (25 results) that filters for healthier finances and more robust balance sheets.
- Spot potential future leaders through a 21 high quality undiscovered gems that highlights underfollowed businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com