


Did Fleetwood’s Fall Catch You Out? What Investors Missed
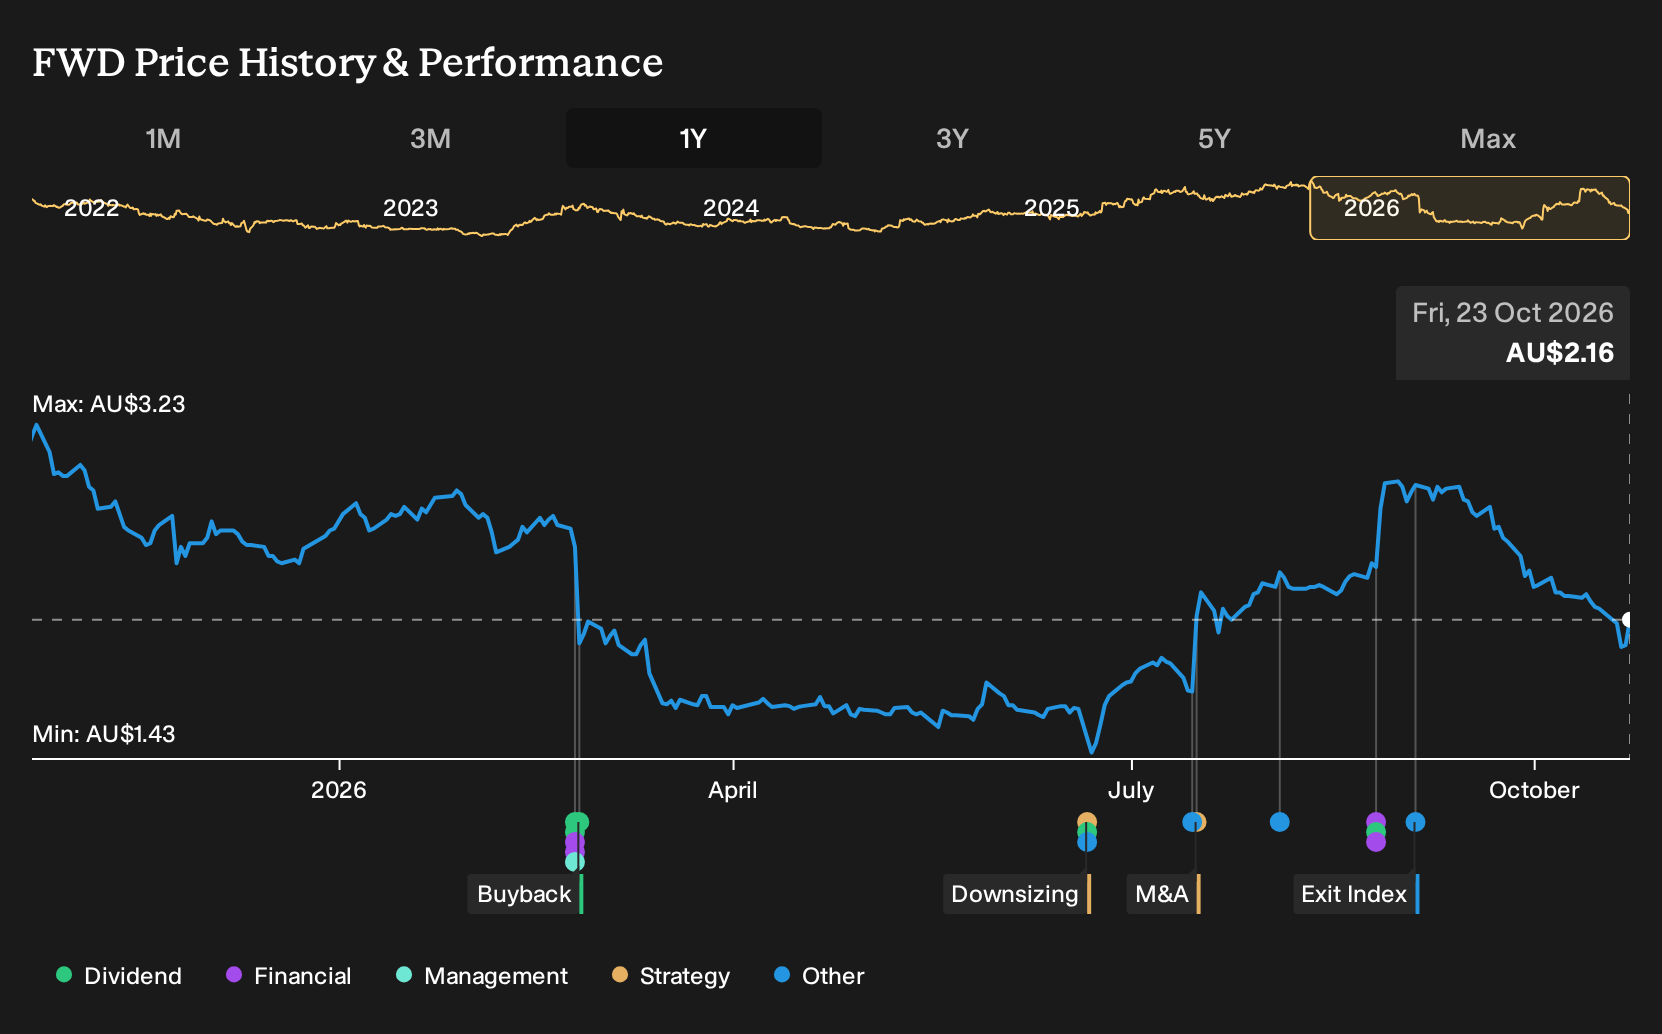
Fleetwood’s latest half year report landed on 26 August 2026, showing revenue of A$245.5 million paired with a swing from A$9.9 million in underlying profit to a A$6.1 million loss, and a net margin that moved from 4.3% to a 2.5% deficit. Holding Fleetwood over the past year would have meant a 27.4% loss, including dividends. If you had made that call back in October 2025, you may want to consider how today’s weaker profitability fits into your expectations now.
The easy part of this move is behind Fleetwood. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Fleetwood
The shares cost A$3.17 at the start of the period, so any Fleetwood view in late 2025 really came down to which story you believed about its future earnings power.
On the optimistic side, the bullish Narrative pointed to a Fair Value of A$3.46, a price implied by assumptions such as revenue growing 3.4% a year and profit margins reaching 5.9%. Supporters leaned on deeper government panel relationships and strong repeat customer rates in modular buildings.
The more cautious camp worked off a Fair Value of A$2.79 and focused on risks. That view highlighted structural pressure in RV Solutions, including declining locally manufactured RV sales and competition from low cost imports, as a potential drag on group profitability.
What The Results Changed For Fleetwood
Fleetwood delivered A$245.5 million in revenue in H2 2026, above the prior A$232.5 million, which lent some support to the optimistic story about demand. Profit flipped from an underlying A$9.9 million gain to a A$6.1 million loss though, and net margin moved from a 4.3% surplus to a 2.5% deficit, so the profitability leg of the bullish case was not proven.
The key assumption here was that higher sales would translate into healthier earnings. For any other stock built on a similar claim, track net income and net margin alongside revenue to see whether growth is turning into actual profitability.
What Fleetwood’s Lower Price Now Asks You To Believe
Fleetwood now changes hands at A$2.16, well below where it started a year ago. The selected Narrative sees Fair Value above that level, tied to Community Solutions and a leaner portfolio after exiting RV Solutions.
For that higher figure to make sense, a buyer today must assume accommodation undersupply and cost cuts translate into consistently profitable projects and stronger cash generation.
"Persistent undersupply of transient worker accommodation in Karratha, with management indicating a shortfall of roughly 1,500 beds over the next five years and Searipple Village already fully booked to the end of calendar 2026, supports the potential for sustained high occupancy and ongoing revenue and earnings contribution from Community Solutions."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Fleetwood’s Construction Story
Fleetwood keeps your attention on accommodation close to the ground. One step away, another business operates far above that familiar view.
Instead of villages and modular rooms, this operator concentrates on rockets and satellites. Your customers might sleep in Fleetwood assets, while their data increasingly moves through orbit.
It plans to create a cheaper, reliable launch platform and supply the hardware riding on top. Together, those pieces target infrastructure that many space based services require.
If that effort succeeds, more everyday tools could quietly rely on its rockets and satellite systems. Most users might never realise their routines depend on technology overhead.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 86% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com