


How Middle East Supply Risk At Ovintiv Stock Has Changed Its Investment Story
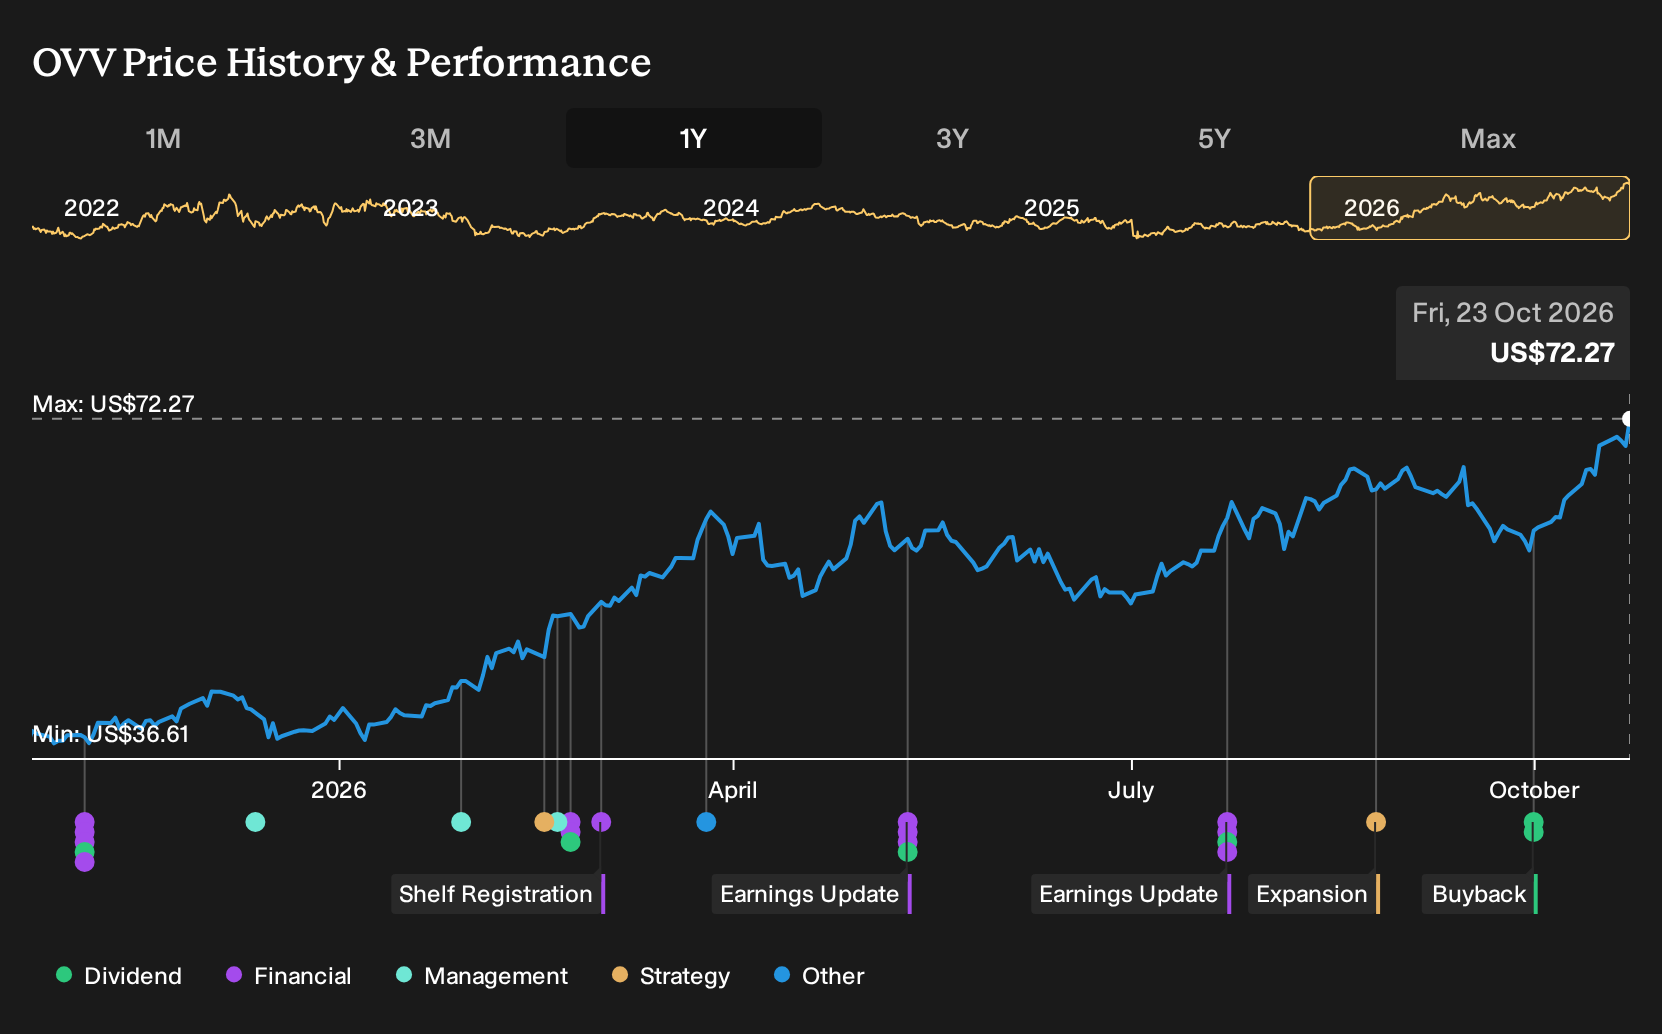
- Ovintiv has moved into a technical buy zone up to $70.89 after recent Middle East conflict risks shifted investor focus toward energy producers and potential supply disruption.
- The renewed spotlight on Ovintiv highlights how its North American oil and gas portfolio can become a perceived hedge when global supply reliability is questioned.
- This article examines how Ovintiv's investment narrative intersects with rising Middle East risk, particularly its role as a North American supply alternative.
Scan beyond Ovintiv and review hand picked energy producers that may also benefit from shifting supply risk through the 42 power grid technology and infrastructure stocks
Ovintiv Investment Narrative Recap
To own Ovintiv, you need to believe the drilling and completion efficiency work in the Permian and Montney, plus the NuVista and Paramount Montney integration, can keep supporting healthy cash generation even if headline revenue drifts lower. The near term swing factor is how well those cost and productivity gains offset any pricing or volume softness.
The biggest operational risk right now is that valuation already bakes in optimistic free cash flow and earnings assumptions while reported results carry noise from past impairments and one off items. If future wells or acquisition outcomes disappoint or require further write downs, sentiment could turn quickly, regardless of Middle East headlines.
There have been no fresh company specific announcements tied directly to the Middle East situation. The most relevant context is therefore Ovintiv’s existing capital and operating framework. Management has highlighted low leverage near US$3.0b and a plan to keep returning a large share of free cash flow through buybacks and dividends, subject to cash generation.
For you, the key link between that framework and current catalysts is execution. Efficiency gains in the Permian and Montney, gas marketing optimization, and targeted US$100m of annualized Montney acquisition synergies form the operational engine that needs to support those capital returns. Any shortfall in these areas would matter more to Ovintiv’s medium term story than short bursts of geopolitical risk.
Ovintiv Forecasts And Analyst Assumptions
Analysts are effectively betting that Ovintiv can turn a slightly shrinking top line into much stronger profitability. Revenue is modeled to decline by 1.8% a year over the next three years, yet profit margins are expected to rise from 9.7% today to 20.9% by around 2029.
The earnings bridge that underpins this view is sizeable. Consensus points to earnings of US$1.9b by 2029, compared with US$920.0m today. This implies roughly a doubling of the profit pool if those estimates hold. That is before factoring in a wide spread of views, with forecasts ranging from US$1.3b to US$3.1b.
Ovintiv's narrative projects US$9.0b in revenue and US$1.9b in earnings by 2029. This rests on revenue declining by 1.8% per year and earnings rising by about US$980.0m from current earnings of US$920.0m.
Valuation work in the analyst reports ties those operating assumptions to a specific earnings multiple. To line up with the consensus price targets, Ovintiv would need to trade at a P/E of 17.3x on the 2029 earnings estimate. This compares with 19.8x today and an industry level quoted at 12.3x for US oil and gas peers.
Share issuance also features in the model. Forecasts currently assume the share count grows by 7.0% a year over the next three years. This means any per share outcome depends not just on profit delivery but also on how that additional equity interacts with buybacks and capital returns already outlined by management.
For readers comparing Ovintiv to other energy producers, the key takeaway from these projections is the mix of slightly lower forecast sales, higher margins, and meaningfully higher earnings, all anchored to a 2029 view. Your own stance on the stock will likely come down to how achievable that margin expansion looks, given the operational plans in the Permian and Montney and the broader role of North American supply when global energy security is in question.
Uncover why Ovintiv's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Ovintiv’s premium drilling inventory at the center of the story. The most optimistic analysts were modeling revenue of about US$9.9b and earnings near US$2.7b by 2029 before the latest Middle East flare up. You can treat those forecasts as a ceiling that might shift as events unfold and explore where you sit between them and the more cautious scenarios.
Explore 5 other Ovintiv fair value estimates, including one that suggests potential upside of up to 191% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ovintiv research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ovintiv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ovintiv's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ovintiv?
If the Ovintiv setup has sharpened your thinking and you want to pressure test that framework across a wider opportunity set, the Simply Wall St Screener can help you quickly filter for businesses that better fit your risk, income, or value preferences.
- For investors who want potential bargains with quality fundamentals, scan through 27 high quality undervalued stocks and see which stocks line up with your return and risk expectations.
- If capital resilience matters more to you than excitement, focus on balance sheet strength using the list of solid balance sheet and fundamentals (25 results) and compare how those companies stack up on debt and liquidity.
- When income reliability is the priority, use the dividend focused 5 dividend fortresses to find payouts that may better match your cash flow needs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com