


SK Hynix (KOSE:A000660) Stock May Look Reasonable Following AI Spending Concerns
SK hynix has logged huge gains over the past few years, and with the stock still tightly linked to the memory cycle, the live question is whether today's price can be explained by the earnings that underpin it.
- Over the past 5 years the share price has delivered a very large total return, which puts extra focus on how much of that move is supported by the profit stream investors are now paying for.
- Recent swings in semiconductor stocks around AI infrastructure spending, memory pricing and Chinese competition feed directly into what SK hynix may be able to earn on its heavy investment in high bandwidth memory and related products.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
The issue now is whether the current market value of SK hynix is aligned with what its earnings justify on an objective appraisal.
If you want to stress test the same earnings question that hangs over SK hynix against a broader set of AI infrastructure plays, line it up beside 55 AI infrastructure stocks.
Does SK hynix Look Undervalued on Earnings?
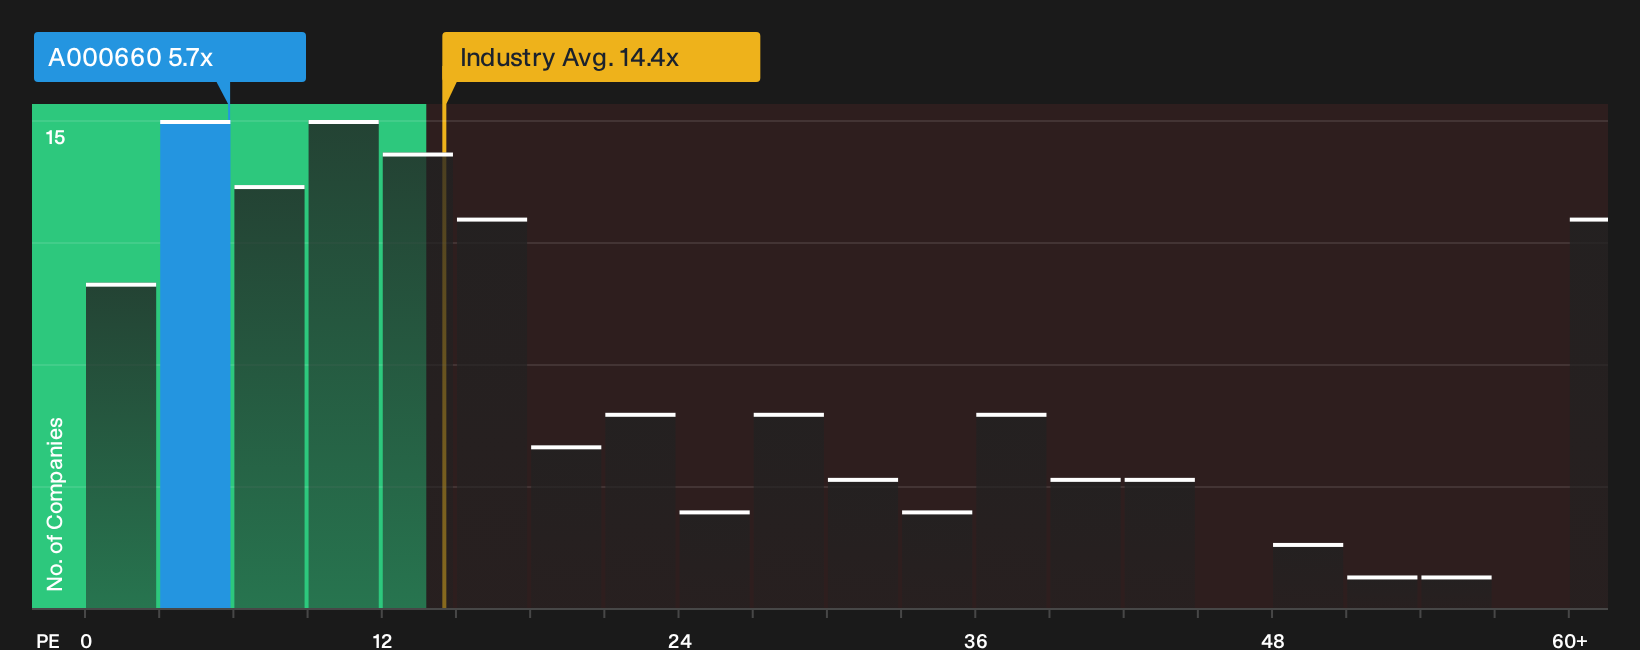
P/E works well for SK hynix because earnings remain the key yardstick investors watch for a capital intensive memory producer. On this lens the stock trades on a P/E of 5.7x, which is less than half the semiconductor sector average of 14.4x and also below the peer group at 11.1x. That is a wide gap for a large listed chipmaker and it puts a lot of weight on the idea that current profits are either unusually high or at risk.
The fair multiple that drops out of the earnings model, which factors in SK hynix specific growth profile, margins, size and risk, still comes out higher than where the shares now change hands. Because recent concern over AI infrastructure spending and Chinese competition has pushed semiconductor stocks down sharply, this discount on P/E suggests the market is already baking in a fairly cautious earnings path compared with the sector. You need to decide whether that caution is excessive or justified before relying on the apparent P/E gap. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the SK hynix valuation question leaves off by explaining which earnings, growth and margin paths would need to hold for the shares to appear materially higher or lower than today. Each narrative links its number to a specific view on how SK hynix's profitability, reinvestment and risk profile could evolve, providing a reference point you can revisit as new information emerges.
One of the top community narratives on SK hynix: 59% undervalued
"Close partnerships with large AI and GPU customers, including multiyear HBM co development and supply work with NVIDIA and around 10 long term agreements..."
Discover why this Narrative puts SK hynix at 59% undervalued.
One more SK hynix check that sits beside the price tag
Before leaning too hard on where SK hynix trades relative to peers, it helps to look at the specific risk markers our research has picked up, and weigh how they sit against the upside story. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com