


Ouster (OUST) Could Be 49% Undervalued On Forterra Ukraine Defense Expansion
Ouster (OUST) is back in focus after extending its multi-year partnership with Forterra, linking its digital lidar hardware to autonomous ground vehicles that are performing real-world missions and casualty evacuations in Ukraine.
That Ukraine deployment story has hit just as Ouster’s 1-day share price return of 6.11% and 7-day share price gain of 4.43% begin to claw back some of the damage from a 30-day share price decline of 24.61% and a 90-day share price retreat of 12.78%.
Viewed over a wider window, the stock carries a 27.04% year-to-date share price return, a 1-year total shareholder return decline of 17.07% and a 3-year total shareholder return that is very large at around 7x. The 5-year total shareholder return is still down 51.80%, which hints that recent defense wins are arriving after a long and volatile journey for investors.
Scan the defense and autonomy space beyond Ouster by checking a curated set of lidar and robotics plays in the 95 robotics and automation stocks that are already seeing real-world deployment.
After Ouster’s sharp pullback and recent bounce, the stock trades at a wide gap to both analyst targets and intrinsic value estimates. Where does a fair price actually land within that range?
Most Popular Narrative: 49% Undervalued
Analysts following Ouster anchor on a fair value of about $57.83, which sits well above the recent $29.69 close and frames the current debate around how much of its lidar and autonomy story is already reflected in the share price.
Ouster is tapping into the massive Intelligent Transportation Systems (ITS) market with their Blue City traffic management solution, which could drive significant revenue growth as they expand deployments across the US, Europe, and Asia. This is expected to positively impact revenue.
See why 84 investors see Ouster as 49% undervalued.
The most followed narrative uses an 8.89% discount rate and assumes rapid expansion across automotive, industrial, robotics, and smart infrastructure adoption to support that $57.83 fair value. It leans heavily on high forecast revenue growth and a shift from losses of $53.3 million today toward future profitability, even as Ouster remains unprofitable and is still working toward cash flow breakeven.
Those projections also factor in the potential from products like the Rev8 lidar platform and BlueCity traffic systems, along with broader physical AI use cases in humanoid robotics, drones, and Counter UAS applications. In that context, the near 49% gap between the narrative fair value and the latest share price reflects a view that the market is not fully pricing in these expected deployments and margin improvements.
Result: Fair Value of $57.83 (UNDERVALUED)
Still, intense competition from lidar peers and the risk that projected revenue and margin improvements do not materialize could quickly challenge this Ouster upside narrative.
Find out about the key risks to this Ouster narrative.
Another View: What Ouster’s P/S Ratio Is Telling You
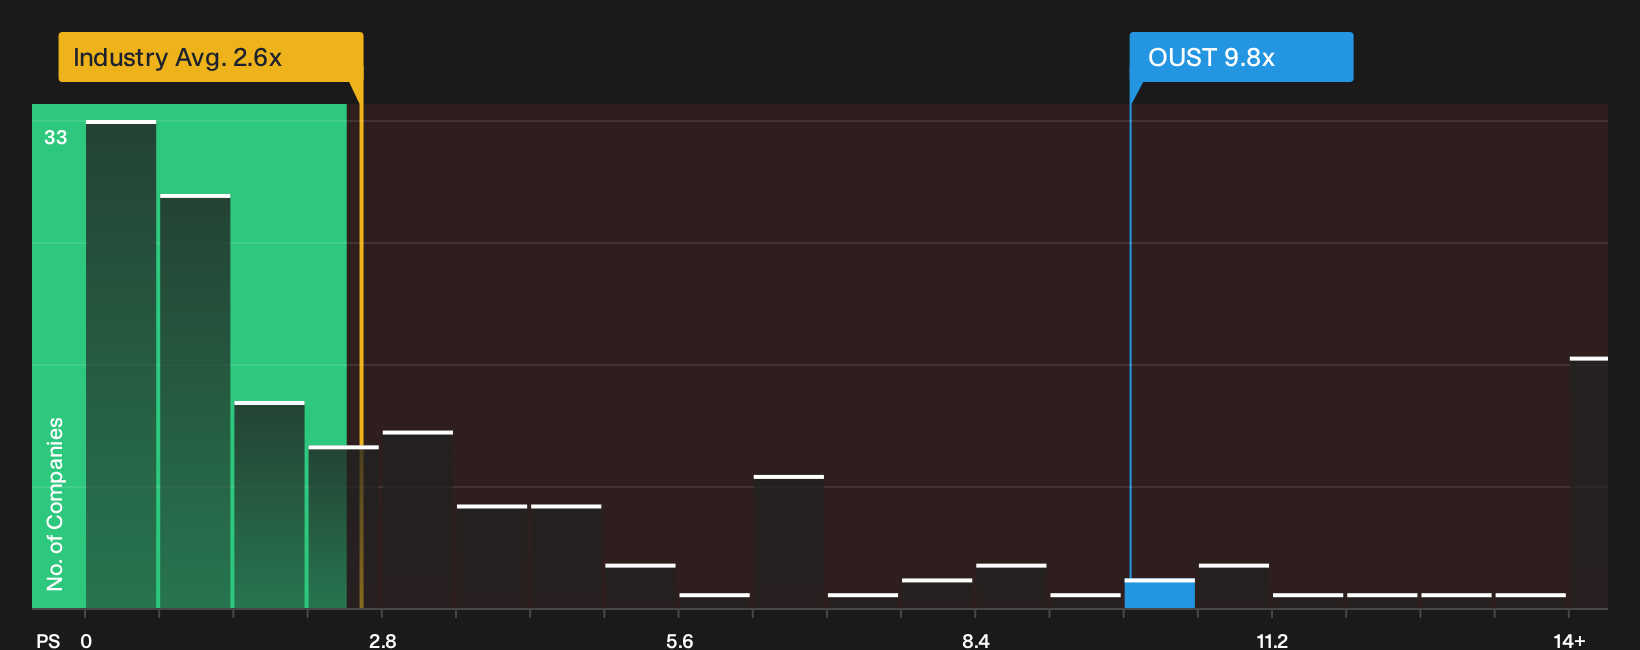
That 49% undervalued story on Ouster bumps into a very different message from the price to sales ratio. The stock trades around 9.8x P/S, compared with 3.8x for peers and 2.6x for the wider US Electronic industry, while the fair ratio sits nearer 5.3x.
In plain terms, the share price already bakes in a much richer sales multiple than both sector averages and that fair ratio target. This points to valuation risk if high growth expectations or margin gains slip. The real question is whether you think Ouster can grow into that premium before sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by Ouster’s mix of promise and risk in this story so far? Do not wait on the sidelines when the data is in front of you and ready to stress test. To weigh both the potential upside and the issues investors are watching closely, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ouster?
If Ouster’s story has sharpened your focus, do not stop at one ticker. Broaden your watchlist now, or you risk missing the next setup hiding in plain sight.
- Hunt for mispriced quality by scanning the 29 high quality undervalued stocks that combine stronger financial profiles with discounted valuations.
- Build a sturdier income stream by reviewing the 6 dividend fortresses that offer higher yields with a focus on resilience.
- Lean into financial strength by checking the list of solid balance sheet and fundamentals (26 results) so cash rich, lower risk businesses are on your radar early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com