


How Investors May Respond To Quanta Services (PWR) Earnings And Data Center Expansion
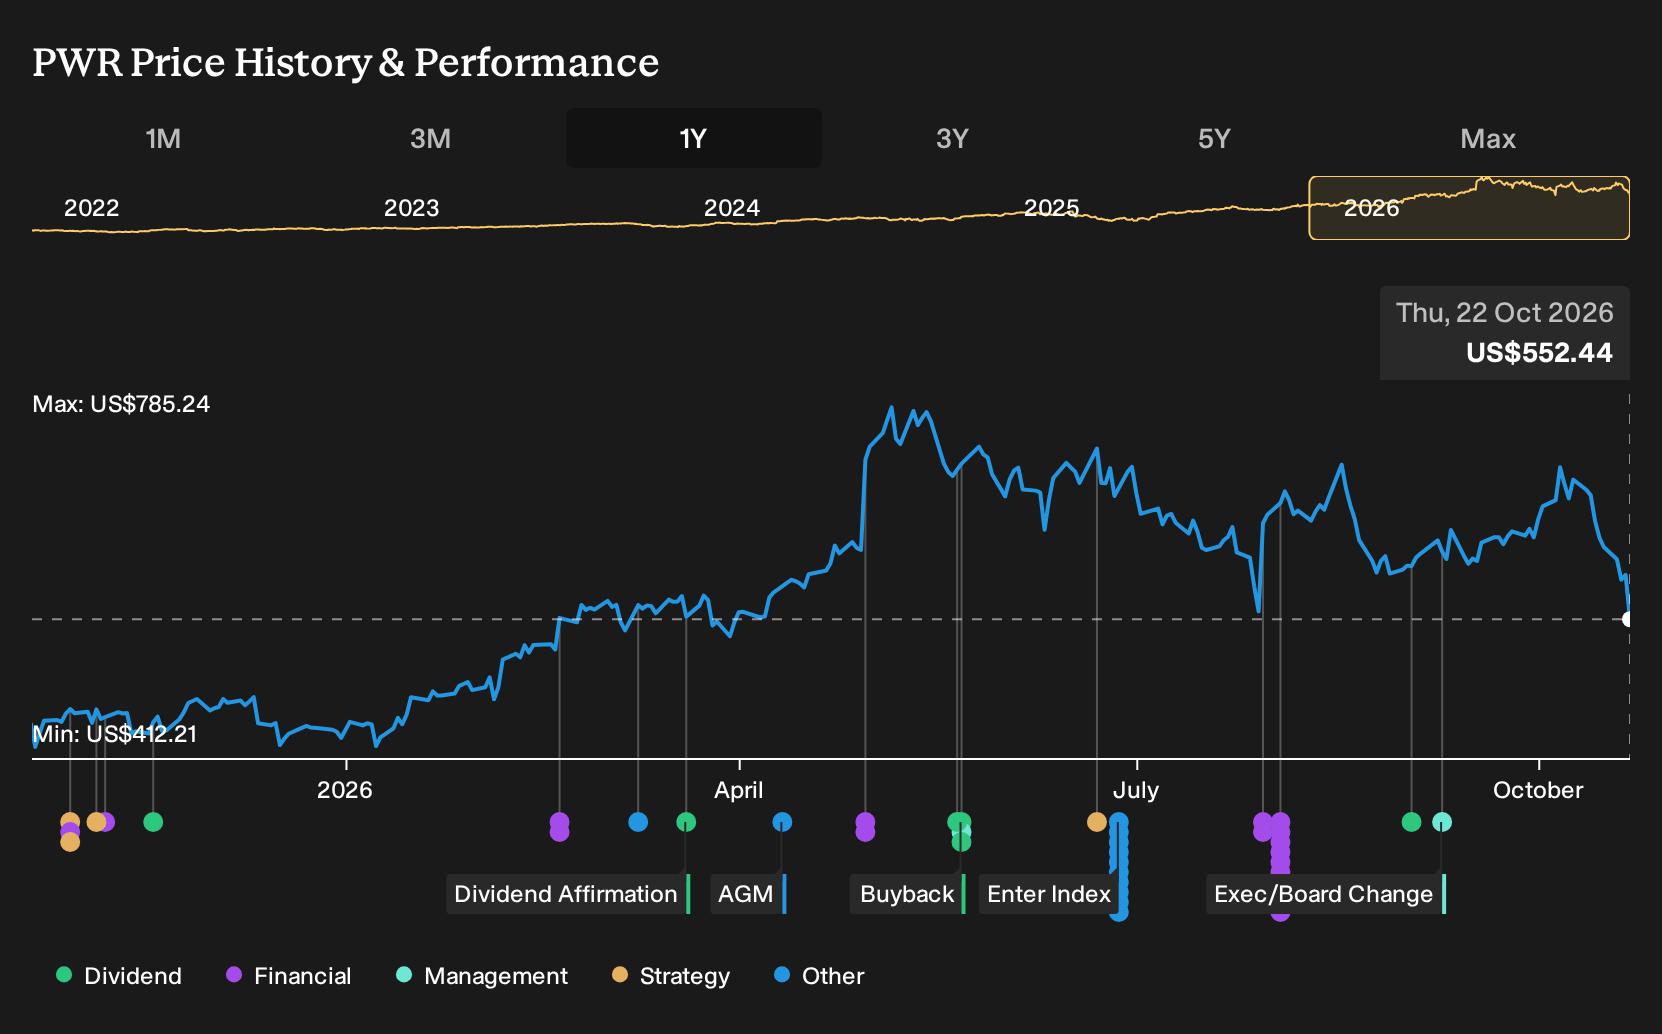
- Quanta Services is in focus after a sharp recent share price decline, with attention building ahead of its October 29, 2026 earnings release and management’s push into data center and hyperscaler related infrastructure work.
- The expansion of integrated electrical, mechanical and grid interconnection services, including added fabrication capacity and past acquisitions, is pulling Quanta Services closer to early project planning, where scope and contract structure can materially shape profitability and risk.
- We will examine how Quanta Services' investment narrative is tested by earnings expectations and its push into hyperscaler and data center infrastructure.
Compare Quanta Services' hyperscaler push with other potential grid and data center beneficiaries by scanning the hand picked 42 power grid technology and infrastructure stocks now, while this theme is in sharp focus.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to be comfortable with a contractor that is tightly tied to long lead grid, transmission and data center projects, where execution quality and contract mix matter more than headlines. The recent 8.1% share price drop puts a harsher spotlight on the October 29 earnings release, but does not change the underlying work already in backlog.
The key short term swing factor is whether management can keep delivering on its raised 2026 revenue, EBITDA and free cash flow targets while scaling hyperscaler related infrastructure. The biggest risk is that project complexity, cost inflation or weaker acquisition contributions lead to a guidance reset, which would hit both earnings and the already premium P/E.
The clearest announcement that ties into this setup is Quanta Services leaning harder into AI driven data center and large load power work. Management expects this area to represent 15% to 20% of revenue in 2026 with very strong projected growth, which sits behind a record backlog of about US$53b as of Q2 2026.
That build out is supported by US$500m to US$700m of investment to roughly double domestic transformer capacity and expand off site fabrication to about 6.7m to 7m square feet. Execution on this manufacturing and integration push is central to the hyperscaler story, and any delays, cost overruns or underused capacity would quickly become a headwind for margins and free cash flow.
How Quanta Services' Long Term Forecasts Frame The Hyperscaler Bet
Analyst models around Quanta Services give a sense of how bold the hyperscaler and grid story needs to be to keep the equity case intact. Forecasts currently point to revenue growing by 18.4% a year over the next three years, with profit margins modeled to move from 4.0% today to 5.0% over the same window. On the earnings line, consensus calls for profit to reach about US$2.7b by 2029, compared with roughly US$1.3b today, while the most optimistic estimates stretch to US$3.2b. That step up would require earnings to a little more than double from current levels, with analysts also building in modest share count growth of 0.82% a year.
Quanta Services' narrative projects US$54.6b revenue and US$2.7b earnings by 2029. This assumes 18.4% yearly revenue growth and an earnings increase of about US$1.4b from US$1.3b today.
Valuation expectations tie these fundamental targets directly to the share price debate. To line up with the current analyst consensus target of US$769.04, investors would need to accept a 2029 setup where Quanta Services generates US$54.6b of revenue and US$2.7b of earnings and trades on a 56.0x P/E multiple, compared with about 73.9x today and roughly 29.1x for the wider US construction peer group. Disagreement inside that framework is visible in the wide spread of price targets, from US$410 at the low end to US$976 at the top, and in one valuation service flagging the stock as 66% to 79% above its own intrinsic value estimate.
These numbers make the hyperscaler and data center push less of a free option and more of a requirement baked into expectations. Management has already lifted 2026 goals to US$39.3b to US$39.7b of revenue, US$4.1b to US$4.2b of adjusted EBITDA and US$2.0b to US$2.5b of free cash flow, helped by acquisitions and manufacturing investments that are meant to ease transformer and high voltage equipment bottlenecks. Any material miss against these targets, or weaker earnings contribution from deals like Phalcon, Enerfab, Percheron and PSD, would make it harder to argue that the rich multiple and the 2029 earnings bridge still hold together.
For readers comparing Quanta Services with other grid and data center contractors, this forecast setup can act as a reference checklist. Revenue growth expectations at 18.4% a year over three years, margin expansion from 4.0% to 5.0%, earnings stretching toward US$2.7b by 2029 and a forward 56.0x P/E are all quantifiable hurdles. The key question is whether the combination of long dated grid modernization, AI driven data center work and expanded fabrication capacity can support that path without eroding returns through project overruns or an overbuilt manufacturing footprint.
Uncover why Quanta Services' fair value signals a 39% potential upside to its current price, a discount that could narrow more quickly than many investors expect.
Exploring Other Perspectives
One alternate view on Quanta Services puts more weight on the risk that hyperscaler and data center demand does not fully absorb the expanded manufacturing footprint. The most cautious analysts were penciling in about US$50.9b of 2029 revenue and US$2.5b of earnings before this selloff and upcoming earnings, which reflects a meaningfully lower bar than the consensus narrative. These forecasts were set before the latest 8.1% share price drop, so treat them as moving pieces rather than fixed truth, and use them as a prompt to compare several different viewpoints before you decide how this story fits your portfolio.
Explore 4 other Quanta Services fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Quanta Services?
If you want to put Quanta Services in context, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener before making any portfolio moves.
- For investors who care most about balance sheet strength and fundamental resilience, scan our list of solid balance sheet and fundamentals (26 results) to compare businesses that may better match your risk tolerance.
- If you are hunting for potential mispriced opportunities, sort through the 29 high quality undervalued stocks and see which companies currently combine quality metrics with compressed valuations.
- Income focused investors can quickly filter for consistent cash payers by reviewing the 6 dividend fortresses and then deciding which yields and payout profiles fit their goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com