


What NICE Stock's Gartner Leader Recognition Means For Shareholders
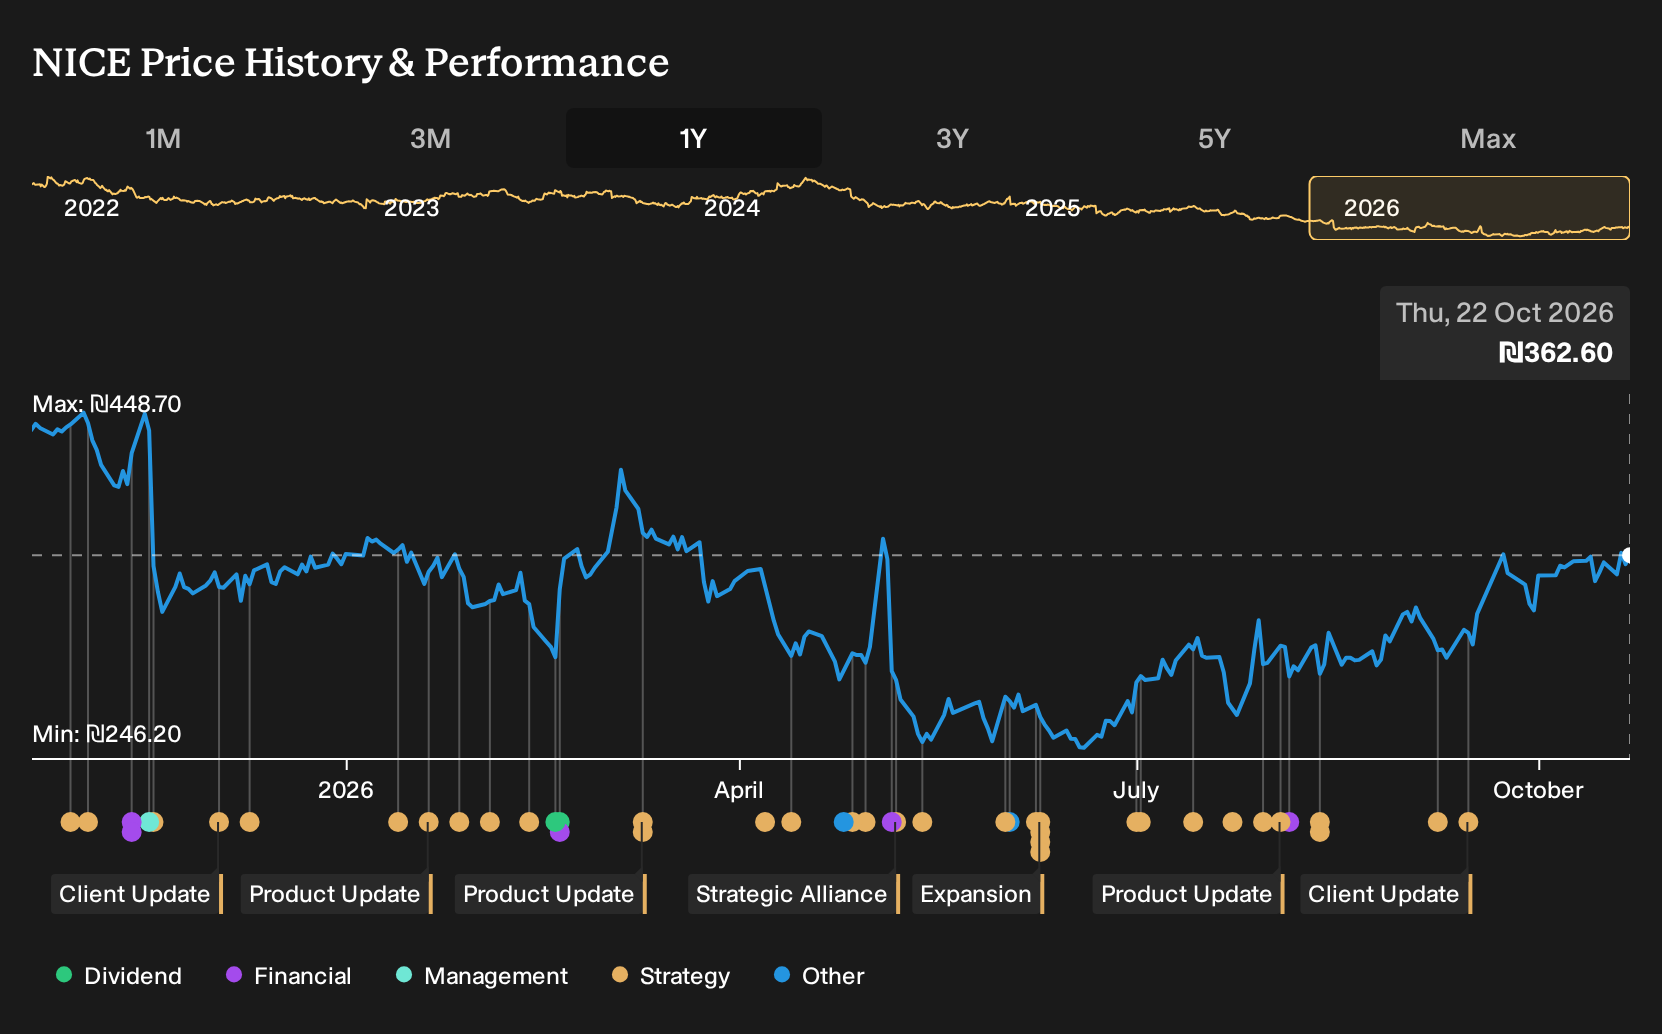
- NICE was recognized in the past as a Leader in the 2026 Gartner Magic Quadrant for Contact Center as a Service, reflecting Gartner's view of its execution and vision in AI-driven customer experience that combines automated agents with human support.
- The recognition highlights growing traction for NICE's AI products, including record AI bookings and wider enterprise deployments, which indicates that customer interaction budgets are shifting toward its cloud platform and AI-centric contact center solutions.
- We will examine how NICE's investment narrative is influenced by Gartner's CCaaS leadership recognition and its AI-driven contact center platform.
Scan how NICE fits into the broader AI customer experience trend by reviewing the hand picked 39 profitable AI stocks that aren't just burning cash that are already turning automation budgets into real earnings.
NICE Investment Narrative Recap
NICE is a bet on AI driven customer engagement becoming the default way large enterprises run their contact centers. To be a shareholder, you need to believe its cloud platforms, including CXone and Actimize, keep winning long term contracts even while gross margins carry the weight of heavy cloud and international spending.
The Gartner CCaaS leadership call supports that belief, but it does not remove the main near term swing factors. The key upside catalyst is continued traction in AI bookings and large deals. The biggest risk is that higher LiveVox churn, margin pressure, and long ramp times keep profitability under strain.
The most relevant data point here is Gartner placing NICE as a Leader in the 2026 CCaaS Magic Quadrant and highlighting its AI driven platform that blends virtual agents with human support. That recognition lines up with reported strength in AI and self service ARR and expanding enterprise deployments.
For you as an investor, the question is execution. If that CCaaS leadership turns into more high quality, recurring cloud contracts across regions, it could support the revenue growth analysts model. If regulatory friction around AI, partner disintermediation, or elevated churn in acquired customers persists, the risk side of the story gets louder.
NICE's narrative projects $4.0b revenue and $638.7m earnings by 2029, based on analysts assuming 9.8% yearly revenue growth and an earnings increase of about $109m from $529.6m today.
Uncover why NICE's fair value indicates a 71% potential upside to its current price before the market closes this gap.
Exploring Other Perspectives
Fair value estimates for NICE from 2 private investors in the Simply Wall St Community cluster between about US$621 and US$758 per share, even before factoring in the latest Gartner news. You are weighing those upbeat models against issues like LiveVox churn, regulatory questions around AI, and partner power, so it helps to review several contrasting viewpoints before acting.
Explore another NICE fair value estimate, including one that suggests it could be worth just ₪620.96!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NICE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NICE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NICE's overall financial health at a glance.
Looking for more investment ideas beyond NICE?
Once you have a view on NICE, it helps to compare it with other opportunities that share some of the qualities you care about most, whether that is value, resilience, or balance sheet strength.
- If you want companies priced below what their fundamentals might suggest, start with a curated 201 high quality undervalued stocks that combine solid cash generation with disciplined financial profiles.
- If capital preservation sits high on your priority list, scan a focused 221 resilient stocks with low risk scores that screens for resilient businesses with lower risk scores.
- If balance sheet strength is non negotiable for you, filter ideas through a list of solid balance sheet and fundamentals (205 results) so you are only comparing stocks with robust finances and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com