


Pickup Alliance Altering The Investment Case For Mitsubishi Motors Stock?
- Honda Motor and Mitsubishi Motors signed a memorandum of understanding to co-develop a Triton-based pickup for ASEAN, with production planned at Mitsubishi’s Thai facility and sales targeted for 2028.
- The project deepens Mitsubishi Motors' role as a manufacturing hub in Thailand, potentially lifting plant utilization while giving Honda quicker access to a regional pickup portfolio.
- We will look at how Mitsubishi Motors' investment narrative shifts as Thai pickup manufacturing capacity is shared with Honda under this agreement.
Scan how this Mitsubishi Motors deal fits into a wider regional autos story by lining up other manufacturers exposed to ASEAN demand via the 42 power grid technology and infrastructure stocks
Mitsubishi Motors Investment Narrative Recap
Mitsubishi Motors asks you to believe it can turn a low margin, export heavy car business into something more resilient and better balanced. The focus is clear: push a higher margin mix, lean more on ASEAN demand and keep chipping away at costs after a period where operating profit dropped and North America stayed exposed to tariffs.
The new pickup MoU with Honda looks additive rather than transformational. It supports the existing bet on Thailand as a hub, but it does not change the core near term swing factors. The key upside driver is still execution on mix and model rollouts. The main risk remains margin pressure from intense price competition and incentives.
The Thai investment plan of Bt16b by 2030 is the clearest reference point for this Honda tie up. Management is already committing capital to use Thailand for pickups and future EVs, while also consolidating production there to cut structural costs. The Honda production supply fits into that same manufacturing logic.
For you as a shareholder, the question is how these commitments interact with existing headwinds. Retail volumes recently fell 5%, operating profit declined 46% to ¥75.5b and net income slipped to ¥10b, while earnings are still forecast to grow strongly. Execution risk stays high. More plant sharing and platform reuse only matter if Mitsubishi Motors can hold pricing in a tough market and avoid further one off hits.
Mitsubishi Motors' narrative aligns with analyst expectations for revenues of ¥3,269.1b and earnings of ¥60.7b by 2029, which assumes 4.0% yearly revenue growth and an earnings increase of about ¥50.0b from ¥10.7b today.
Uncover why Mitsubishi Motors' fair value indicates an 8% potential upside to its current price that could narrow quickly.
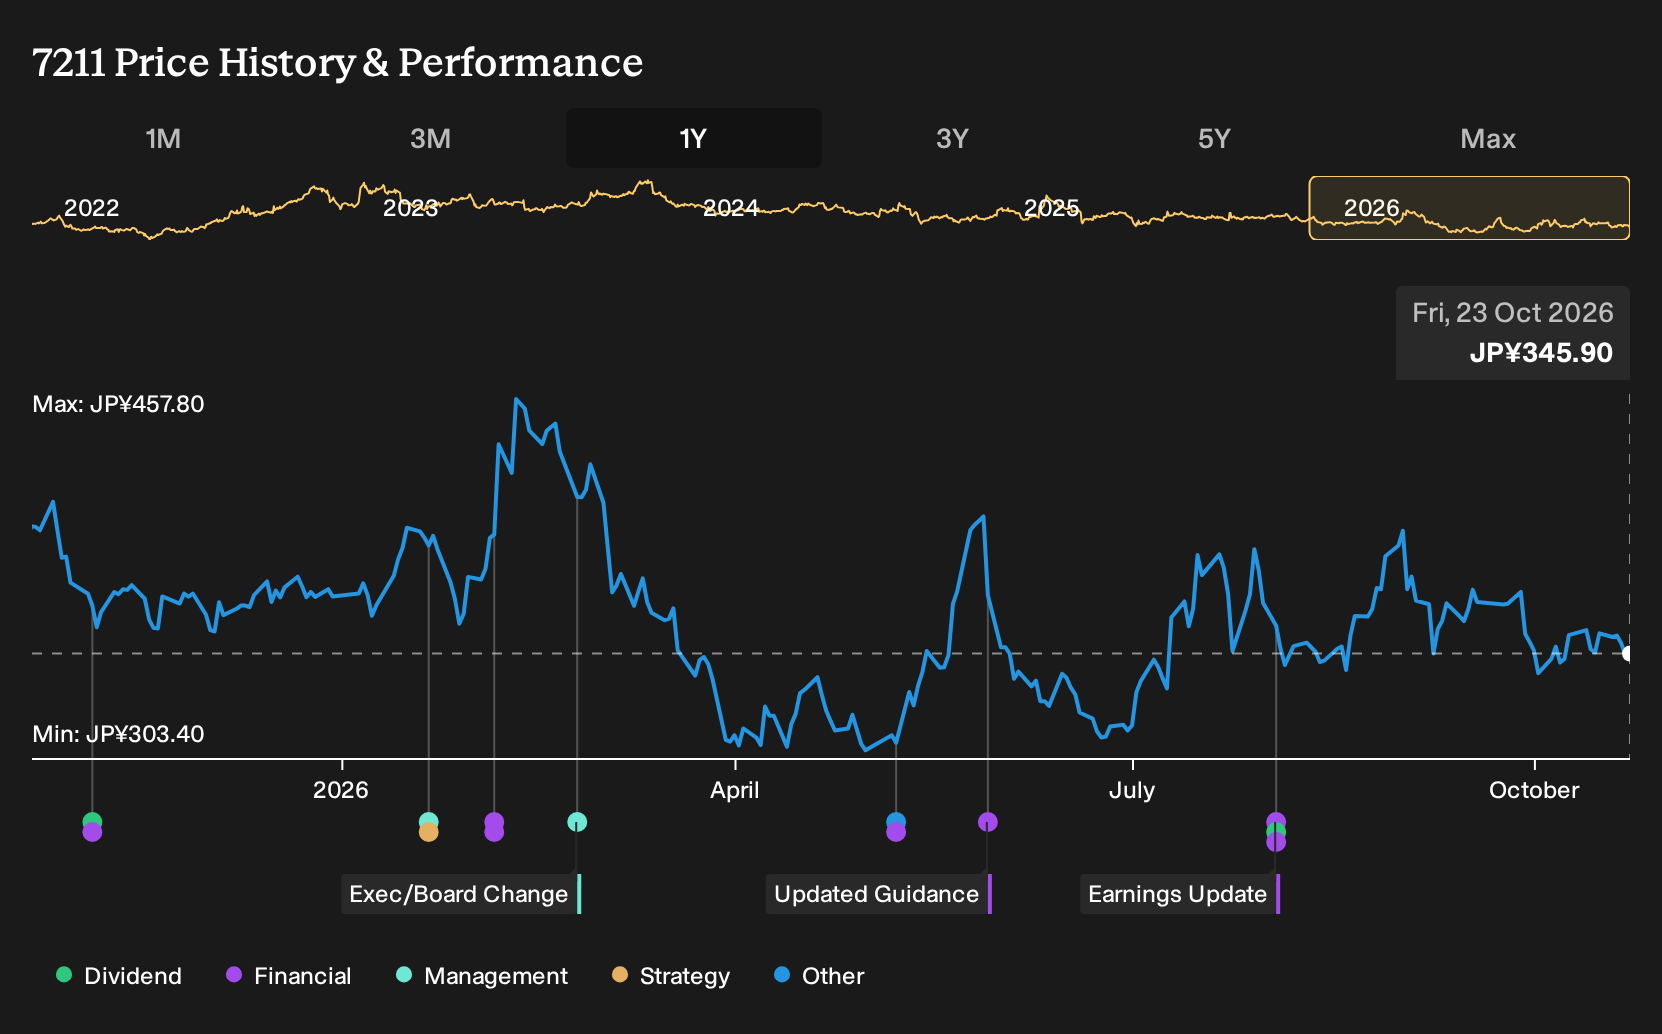
Exploring Other Perspectives
Some of the lowest Mitsubishi Motors forecasts lean heavily on pickup risk. Those analysts worry that Thailand focused projects could struggle if EV costs and tariffs continue to have an impact. As a result, they only pencilled in about ¥3,094.5b of revenue and ¥49.9b of earnings by 2029 before this Honda MoU. Use that gap to weigh your own view.
Explore another Mitsubishi Motors fair value estimate, including one that suggests it could be worth just ¥374.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsubishi Motors research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mitsubishi Motors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi Motors' overall financial health at a glance.
Looking for more Mitsubishi Motors investment ideas?
Mitsubishi Motors is only one way to position around the themes in this story. If you want a broader watchlist that lines up with your risk tolerance and income goals, the Simply Wall St Screener can help you build it quickly and stay focused on what matters to you.
- If you want stability first and foremost, start with a 22 resilient stocks with low risk scores that aim to keep volatility in check while still giving you equity exposure.
- If balance sheet strength is your priority, filter for companies on the list of solid balance sheet and fundamentals (23 results) so you can focus on businesses with room to handle shocks.
- If you are hunting for potential future leaders that fewer investors are watching, scan through a 72 high quality undiscovered gems that already show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com