


OMRON (TSE:6645) Expands Its AI Data Center Push, Is The Stock Fully Valued?
OMRON (TSE:6645) is back in focus after RS highlighted an expanded lineup of Omron Automation control panel components tailored for AI data centers, along with renewed attention on its role in body composition analyzers.
Recent trading has been choppy for OMRON, with the share price falling 9.36% over the past week and 13.94% over the past month, even though the year to date share price return is up 32.83% and the 1 year total shareholder return is 21.91%. The 3 and 5 year total shareholder returns show declines, which points to shorter term momentum improving off a weaker long range track record that investors are now reassessing as new AI data center and healthcare themes come into focus.
Scan beyond OMRON and this single headline and size up hand-picked peers plugged into automation, AI infrastructure, and medical hardware through our 95 robotics and automation stocks.
After a sharp pullback and a strong year-to-date rebound, OMRON now sits at a crossroads. Does the current valuation still compensate you for the execution and cyclicality risks embedded in this story?
Preferred P/E of 24x: Is it justified?
On simple earnings math, OMRON trades on a P/E of 24x, which prices the stock above the level suggested by the SWS fair P/E of 21.9x and leaves investors paying up for each yen of profit at ¥5,308 per share.
The P/E ratio compares what the market is willing to pay today for each unit of current earnings. It gives you a quick reality check on how optimistic sentiment is around OMRON and its automation and healthcare exposure.
Against direct peers, that 24x multiple looks more restrained, since similar electronics stocks average 34.2x. The market is assigning OMRON a richer valuation than the broader JP Electronic industry on 15.2x, which suggests investors are treating the recent 32.9% earnings growth and 5.4% net margin as worthy of a premium tag while still leaving a discount to closest rivals.
Compared with the fair P/E of 21.9x, the current pricing is still higher. This signals that the market may already be baking in a portion of the forecast 15.2% annual profit growth and could move closer to that fair ratio level if sentiment cools.
Explore the SWS fair ratio for OMRON.
Result: Price-to-earnings of 24x (OVERVALUED)
Still, the recent share price drop and the weaker 3 and 5 year total returns leave room for sentiment to flip if AI data center demand or healthcare device appetite softens.
Find out about the key risks to this OMRON narrative.
Another view on OMRON’s value
The SWS DCF model tells a different story to the 24x P/E. On this approach, OMRON’s future cash flows point to a value of ¥4,168.88 per share, compared with the current ¥5,308. That signals an overvalued result and raises a simple question: which signal should carry more weight for you?
Before leaning on either method too heavily, it helps to see how this cash flow view is built up through detailed assumptions and scenarios. Look into how the SWS DCF model arrives at its fair value.
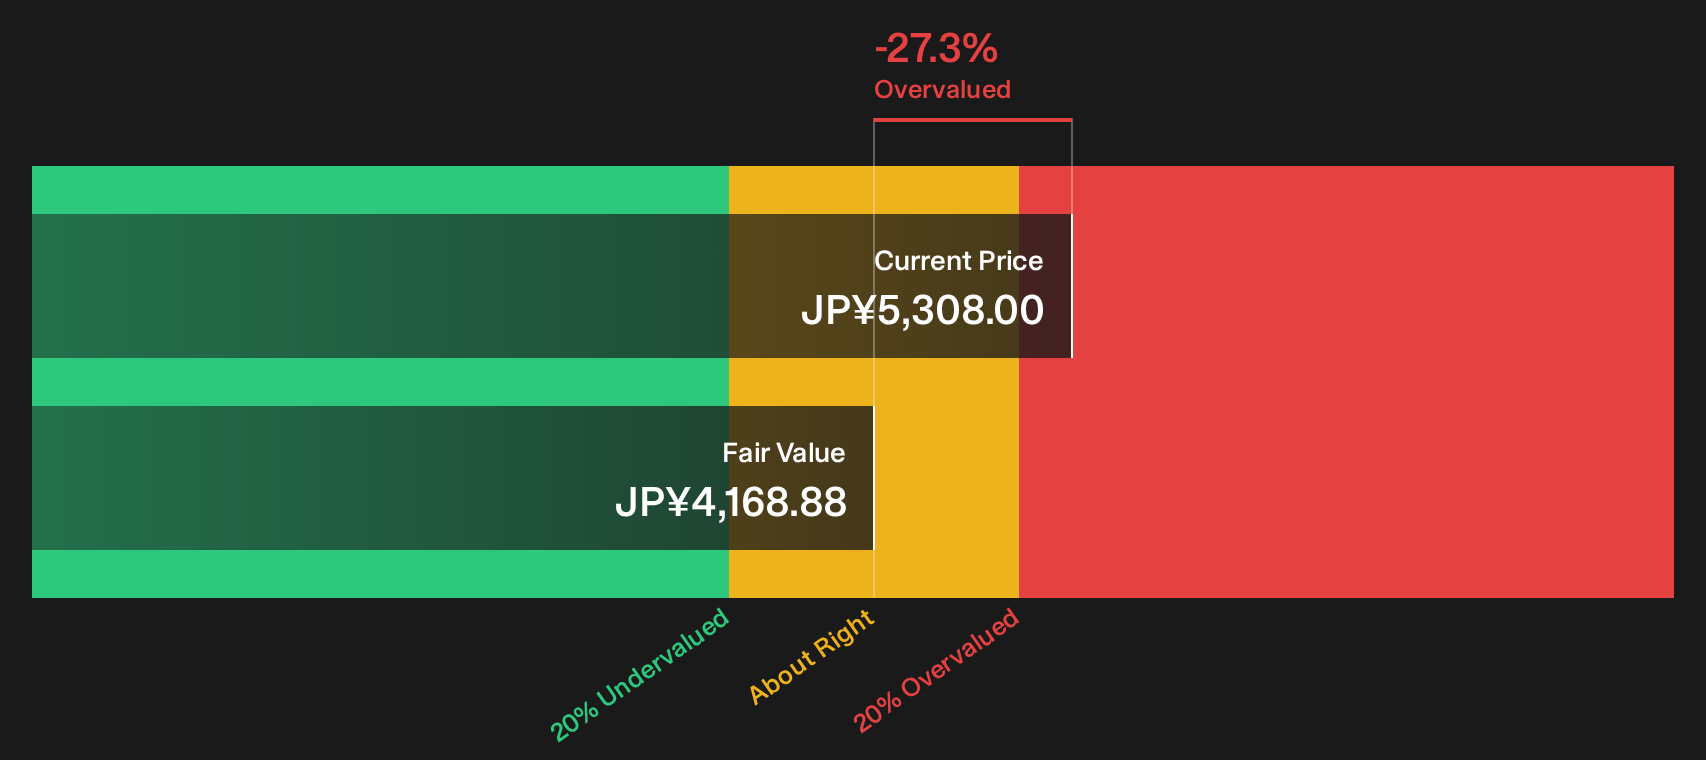
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OMRON for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around OMRON is clearly split, which is often a good time to move quickly and test the numbers against your own expectations by looking at the full breakdown of 2 key rewards and 2 important warning signs.
Looking for more OMRON investment ideas?
If OMRON has sharpened your focus on where capital could work harder, broaden the search now with a few targeted screens that surface very different types of opportunities.
- Target steady cash generators by using the 15 high quality undervalued stocks that combine strong fundamentals with prices that still look reasonable.
- Strengthen your defense with the 22 resilient stocks with low risk scores that filters for businesses carrying lower overall risk scores.
- Hunt for future standouts through the 72 high quality undiscovered gems that highlight quality companies the wider market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com