


What Merck KGaA Stock's Cancer Trial Supply Deal Means For Shareholders
- Adlai Nortye announced on 15 October 2026 that it entered clinical trial collaboration and supply agreements with Eli Lilly and Merck KGaA to provide cetuximab for a global Phase I trial of AN4035 in CEACAM5-enriched, RAS-addicted solid tumors across the US, Australia and China.
- The deal reinforces Merck KGaA’s role as a key cetuximab supplier in early oncology research, linking its Healthcare portfolio to external ADC development without taking on direct sponsorship risk for the AN4035 program.
- This article examines how Merck KGaA’s investment narrative is influenced by this cetuximab supply partnership for a global oncology trial.
Scan how Merck KGaA’s oncology partnership fits beside other potential breakout healthcare opportunities by comparing it with 126 healthcare AI stocks.
Merck KGaA Investment Narrative Recap
To own Merck KGaA, you effectively need to believe that Life Science and Electronics can carry more of the weight while Healthcare transitions away from older blockbusters. The immediate swing factor is execution on acquisitions and workflow deals that are meant to support margins as products like Mavenclad face visible loss of exclusivity.
The Adlai Nortye cetuximab supply news is directionally aligned with that Healthcare refocus but looks immaterial to near term earnings. The bigger short term risk still sits in Healthcare concentration and potential currency headwinds, with any renewed softness in Electronics delivery systems likely to matter more than this single oncology trial collaboration.
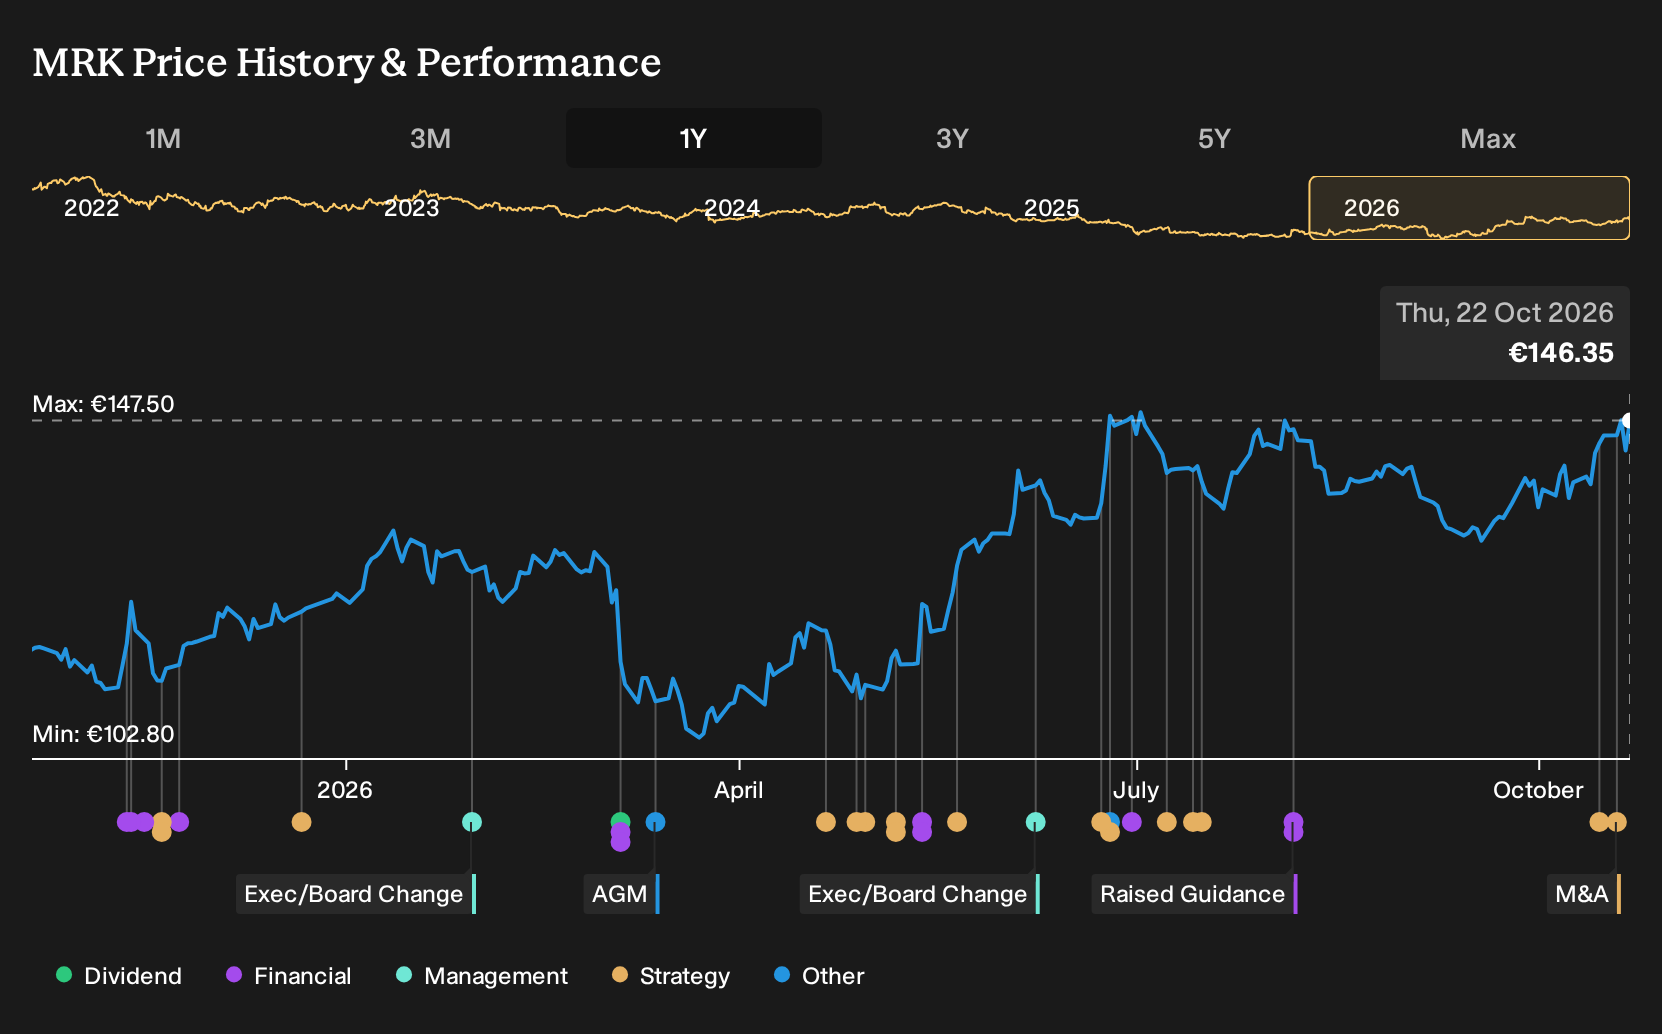
The recent clinical trial collaboration where Merck KGaA supplies cetuximab to Adlai Nortye’s AN4035 Phase I study ties directly into the current Healthcare catalyst story. Investors are watching whether newer oncology, rare disease and fertility assets, supported by this type of early pipeline exposure, can offset the expected erosion from Mavenclad and other mature therapies.
ESMO 2026 in Madrid now becomes a useful checkpoint. Any fresh data or portfolio context around Merck KGaA’s oncology efforts, including how partnered programs like AN4035 sit alongside internal late stage assets such as enpatoran and Precem TcT, feeds into the same core question for shareholders: how durable future Healthcare earnings can be.
Merck KGaA's current analyst narrative points to €24.6b in revenue and €3.4b in earnings by 2029, based on a projected 5.2% yearly increase in sales and an earnings uplift of €1.0b from €2.4b today.
Uncover why Merck KGaA's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts on Merck KGaA frame Bio-Techne as the real swing factor, not oncology deals like the Adlai Nortye cetuximab partnership. They were already pencilling in roughly €26.1b of revenue and €3.8b of earnings by 2029. You can treat these upbeat forecasts as one extreme and compare other viewpoints to assess how today’s news might reshape them.
Explore 3 other Merck KGaA fair value estimates, including one that suggests as much as 127% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Merck KGaA research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Merck KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merck KGaA's overall financial health at a glance.
Looking For More Investment Ideas Beyond Merck KGaA?
Once you have a view on Merck KGaA, it can help to widen the lens and compare it with other stocks that fit different risk and income profiles using the Simply Wall St Screener.
- If you want income to do more of the work in your portfolio, take a look at companies we flag as potential 226 dividend fortresses that may suit a yield focused approach.
- For readers who care most about resilient balance sheets and solid fundamentals, the list of solid balance sheet and fundamentals (205 results) can help surface candidates that match a more defensive style.
- If you enjoy hunting for potential mispriced opportunities that the market may not be paying much attention to yet, the 615 high quality undiscovered gems is a useful next step.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com