


Farmers & Merchants Bank Of Long Beach (FMBL) Just Raised A Bigger Question
Farmers & Merchants Bank of Long Beach (FMBL) just posted a sharp third quarter 2026 setback, moving from a profit a year ago to a US$36.78 million loss despite higher net interest income.
Despite the Q3 setback, Farmers & Merchants Bank of Long Beach has seen its share price gain 18.84% year to date, with a 28.87% total shareholder return over the past year and a very large 3 year total shareholder return. This suggests longer term momentum has not yet fully faded even as recent quarterly results reset expectations around risk and valuation pressure.
Stress test how this setback compares by scanning other hand picked regional and community banks with resilient balance sheets using our list of solid balance sheet and fundamentals (26 results).
Farmers & Merchants Bank of Long Beach now appears to be a solid regional franchise carrying fresh earnings scars. After that Q3 loss and powerful multi year shareholder return, investors may be asking whether the stock still represents a quality business at a fair price.
Price-to-Earnings of 31.1x: Is it justified?
Valuation is now a key tension point for Farmers & Merchants Bank of Long Beach, with the stock at a last close of $9,840 and trading on a P/E of 31.1x while the Q3 2026 loss and weaker recent profit trends sit in the background.
The P/E ratio compares the share price to earnings per share and gives a quick sense of how much investors are paying for each dollar of profit. For a regional bank like Farmers & Merchants Bank of Long Beach, this gauge often reflects what the market is willing to pay for its franchise strength, lending mix and perceived earnings resilience.
FMBL carries a 31.1x P/E, while earnings have declined by 17.5% per year over the past 5 years and fell 27.9% over the past year, alongside a Q3 move into a US$36.78 million loss and a low 2.9% return on equity. That combination points to investors accepting a high price relative to recent profitability, rather than a ratio that lines up cleanly with the bank’s reported earnings profile.
Compared with the US Banks industry average P/E of 11.5x and a peer average of 11.9x, the 31.1x figure is far richer. The valuation multiple sits well above those benchmarks, which signals the market is assigning a premium relative to sector and peer references rather than pricing Farmers & Merchants Bank of Long Beach in line with other regional lenders.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 31.1x (OVERVALUED)
Still, the Q3 loss and low 2.9% return on equity leave Farmers & Merchants Bank of Long Beach exposed if profitability or credit quality weakens further.
Find out about the key risks to this Farmers & Merchants Bank of Long Beach narrative.
Another View: DCF Puts Farmers & Merchants Bank of Long Beach In A Different Light
The market is paying a rich 31.1x P/E for Farmers & Merchants Bank of Long Beach, yet our DCF model points to a future cash flow value of $1,250.26 per share against a current price of $9,840. That wide gap implies investors are leaning heavily on franchise appeal rather than modeled cash generation. This raises the question of how long both views can coexist.
Look into how the SWS DCF model arrives at its fair value.
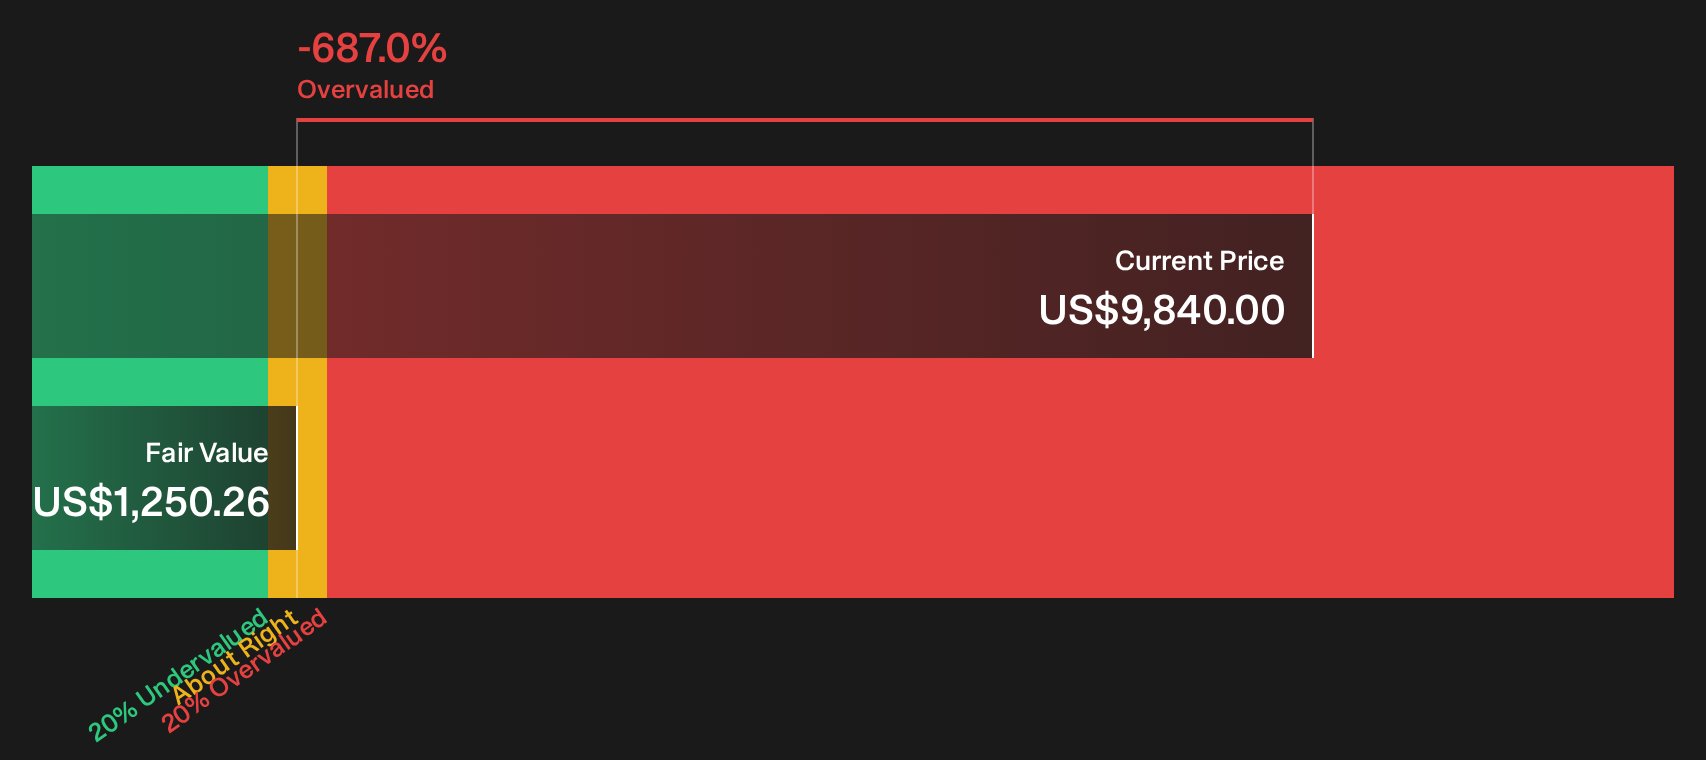
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Farmers & Merchants Bank of Long Beach for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big valuation gap or early warning sign: Either way, you should move quickly, review the underlying data and weigh the 1 important warning sign.
Looking for more investment ideas beyond Farmers & Merchants Bank of Long Beach?
If Farmers & Merchants Bank of Long Beach raises more questions than answers for your portfolio, you could broaden your watchlist with fresh ideas from the Simply Wall Street Screener while this research is still top of mind.
- Target potential mispricings by scanning a curated 29 high quality undervalued stocks that combines quality fundamentals with attractive valuations.
- Strengthen your income stream by reviewing a focused 6 dividend fortresses designed for investors who care about both yield and staying power.
- Dial down portfolio risk by filtering a 30 resilient stocks with low risk scores that highlights companies with sturdier financial profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com