


Higher Earnings Estimates Might Change The Case For Investing In Stock Yards Bancorp Stock (SYBT)
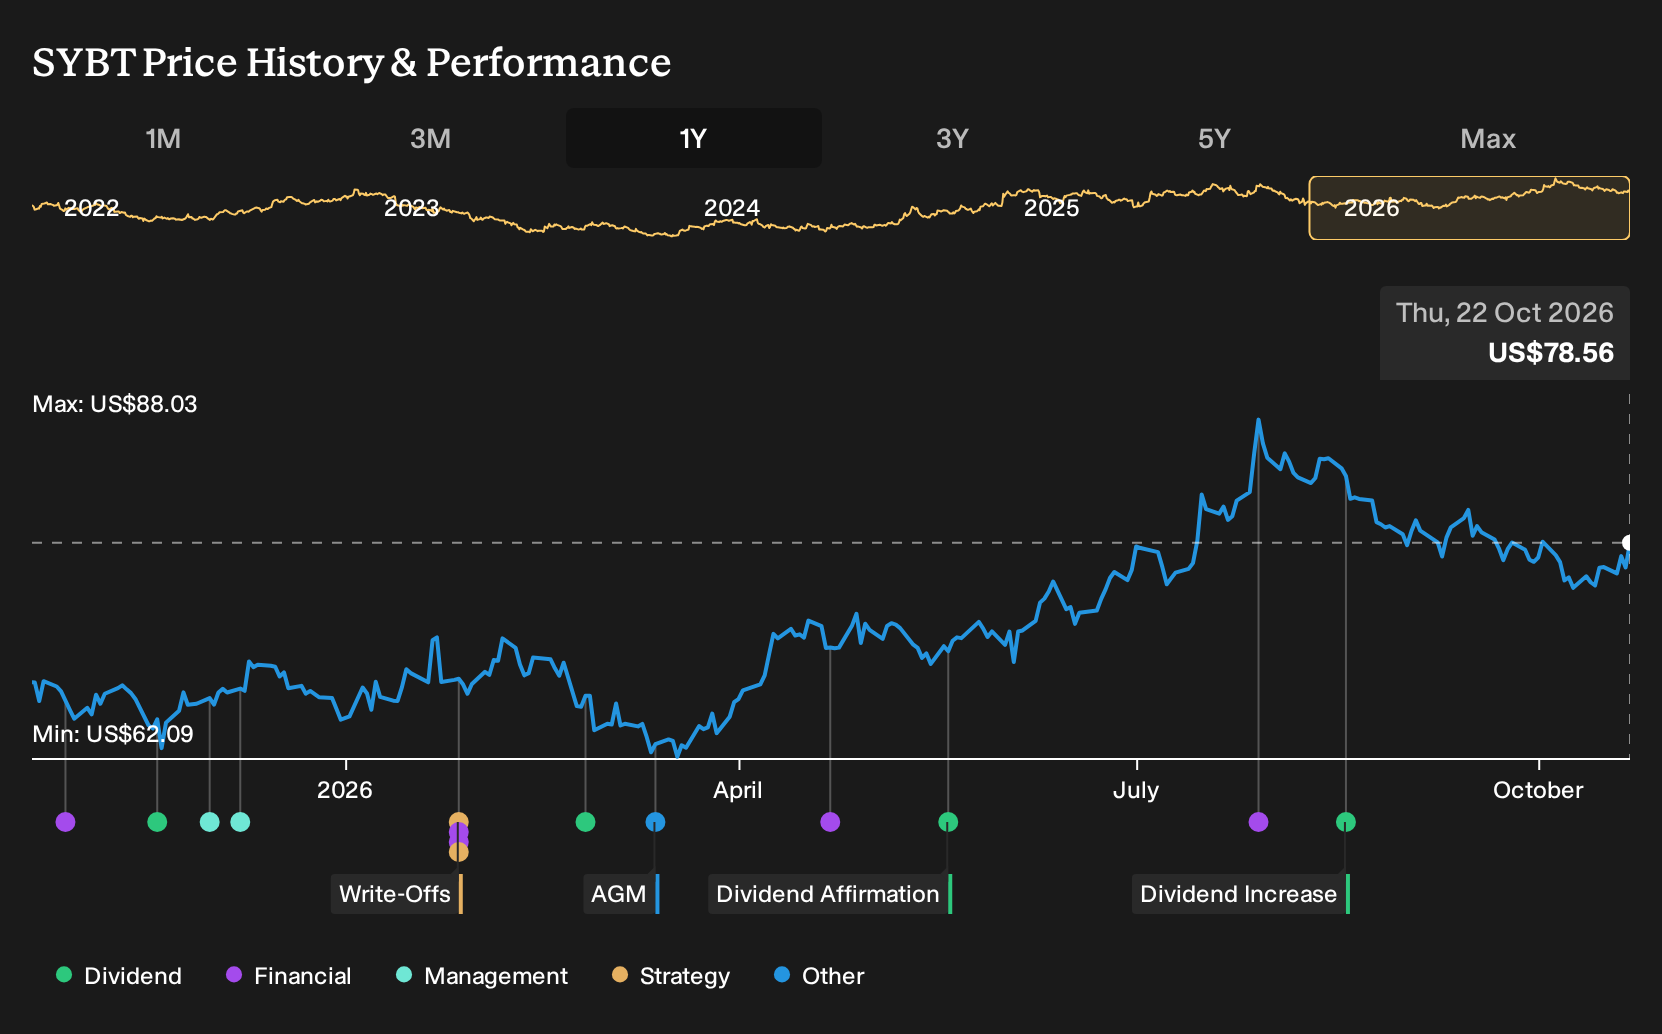
- Stock Yards Bancorp is expected to report quarterly earnings of $1.34 per share for the September 2026 quarter, with projected revenue of $118.82 million and consensus EPS estimates recently revised higher.
- Net interest income and tangible book value per share have shown strong multi year growth, pointing to a balance sheet and core banking engine that investors closely watch ahead of earnings.
- We will look at how Stock Yards Bancorp's investment narrative is shaped by rising EPS expectations and accelerating tangible book value.
Scan how Stock Yards Bancorp compares to other banks with strong balance sheets and earnings momentum by reviewing our hand picked list of solid balance sheet and fundamentals (26 results).
What Is Stock Yards Bancorp's Investment Narrative?
To own Stock Yards Bancorp, you need to be comfortable with a pretty straightforward banking story. The commercial lending and wealth management mix has to keep producing consistent fee and interest income, and management needs to keep proving it can price loans sensibly without chasing volume. The recent lift in EPS and revenue expectations for the September 2026 quarter reinforces that investors are watching execution closely in the near term, not just long run narratives about balance sheet quality.
Short term, the key swing factors are loan demand, deposit costs, and credit quality, all of which feed straight into net interest income and that steadily rising tangible book value profile. The higher earnings estimate cuts both ways, since it raises the bar on what will be considered a “good enough” print. The shares already trade on a P/E above the broader US banks group, so any stumble on operations or guidance might matter more than usual.
Even so, there is one pressure point around Stock Yards Bancorp that is easy to gloss over until you look closely at ...
There's only one way to know the right time to buy, sell or hold Stock Yards Bancorp. Head to Simply Wall St's company report for the latest analysis of Stock Yards Bancorp's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stock Yards Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stock Yards Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stock Yards Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stock Yards Bancorp?
If you want to pressure test your view on Stock Yards Bancorp, it helps to line it up against other companies with different risk and income profiles. The Simply Wall St Screener lets you scan the market quickly using fundamentals, so you can spot opportunities that fit your own style rather than relying on headlines.
- If you want potential upside with strict attention to quality, review a curated set of under-the-radar opportunities through 20 high quality undiscovered gems.
- For income focused investing with an eye on resilience, check out a selection of payout heavy businesses described as 6 dividend fortresses.
- When capital preservation ranks high on your priority list, narrow your search to companies filtered as 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com