


Fort Worth Expansion Might Change The Case For Investing In Carrier Global (CARR)
- Carrier Global plans to invest more than US$600 million over the next three years in a more than 1 million square foot advanced manufacturing and engineering center in Fort Worth, Texas. The project is intended to expand U.S. capacity for thermal management systems and is targeting operations from 2027 with about 1,500 new jobs.
- The Fort Worth build out connects Carrier Global’s thermal management business directly to long term demand from data centers, healthcare providers, educators and industrial customers. It also aligns with the company’s 2030 sustainability goals through a planned LEED certification and local workforce partnerships.
- This article examines how Carrier Global’s investment narrative is shaped by its US$600 million Fort Worth manufacturing expansion commitment.
Scan for other infrastructure plays that may be benefiting from similar demand as Carrier Global’s Fort Worth expansion by zeroing in on our hand picked 42 power grid technology and infrastructure stocks.
Carrier Global Investment Narrative Recap
For Carrier Global, you need to believe the demand story around climate and energy solutions in data centers, commercial buildings and transport can translate into growing cash generation over time. The Fort Worth build out fits that picture, since it is aimed at advanced thermal management systems that tie directly to the current US$8b plus backlog.
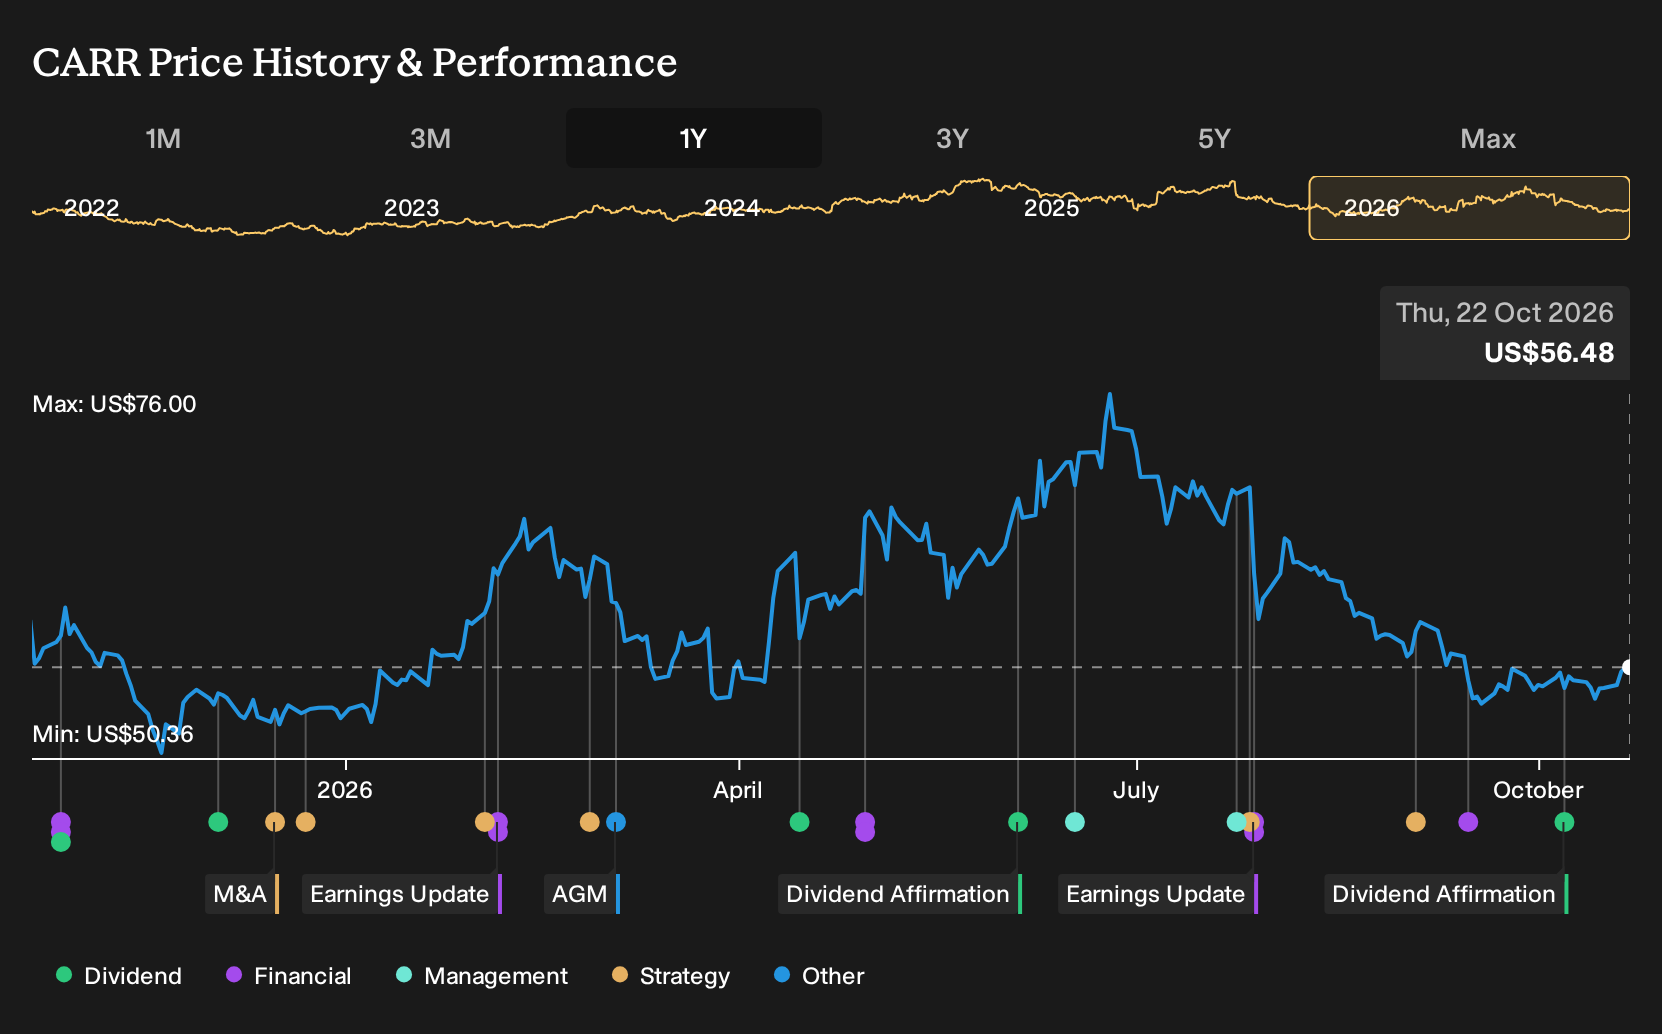
The near term swing factor still sits with execution on margins and capital intensity. Earnings expectations for the September 2026 quarter are mixed, and Carrier Global already faces input cost pressure and tariff headwinds. A US$600 million multiyear project raises the bar on delivering better operating cash flow and returns from that extra capacity.
The most relevant recent development for this story is the Fort Worth advanced manufacturing and engineering center. Management plans to invest more than US$600 million over three years to expand U.S. capacity for air and water cooled commercial chillers and broader thermal management systems, with production targeted from 2027 and about 1,500 new roles.
For you as a shareholder, the operational question is whether this extra footprint helps convert the roughly US$2b of data center backlog, and the wider commercial pipeline, into higher margin, higher quality earnings. The risk is that uneven regional demand, rising tariffs and already compressed net margins limit how much benefit actually reaches the bottom line.
Carrier Global's narrative projects US$27.3b revenue and US$2.6b earnings by 2029. This assumes 7.2% yearly revenue growth and an earnings increase of about US$1.4b from US$1.2b today.
Uncover why Carrier Global's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Carrier Global leans heavily on demand risk from a few big data center customers. Those bearish analysts were only baking in about US$26.3b of revenue and US$2.2b of earnings by 2029 before this Fort Worth news, so they present a much cooler outlook. You can use that gap to stress test your own expectations.
Explore 4 other Carrier Global fair value estimates, including one that suggests as much as 11% downside from the current price.
Form Your Own Verdict
Do not just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Carrier Global research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carrier Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carrier Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carrier Global?
If the Carrier Global story has sharpened your thinking, it can help to compare it with other opportunities that share some of the same themes, from financial resilience to income potential. A focused screener gives you a fast way to surface candidates that match the type of balance sheet strength or return profile you want to research next.
- If capital preservation sits high on your checklist, start with companies that score well on financial resilience by reviewing our 30 resilient stocks with low risk scores.
- For investors who care most about quality at a sensible entry point, filter for strong fundamentals with appealing pricing through our 20 high quality undiscovered gems.
- If reliable income is a priority, narrow the field to companies offering robust payouts that clear a 5% yield hurdle using our 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com