


Is Selkirk Copper Mines (CVE:SCMI) In A Good Position To Deliver On Growth Plans?
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
Given this risk, we thought we'd take a look at whether Selkirk Copper Mines (CVE:SCMI) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is Selkirk Copper Mines' Cash Runway?
A company's cash runway is calculated by dividing its cash hoard by its cash burn. When Selkirk Copper Mines last reported its June 2026 balance sheet in August 2026, it had zero debt and cash worth CA$37m. Importantly, its cash burn was CA$39m over the trailing twelve months. So it had a cash runway of approximately 11 months from June 2026. That's quite a short cash runway, indicating the company must either reduce its annual cash burn or replenish its cash. You can see how its cash balance has changed over time in the image below.
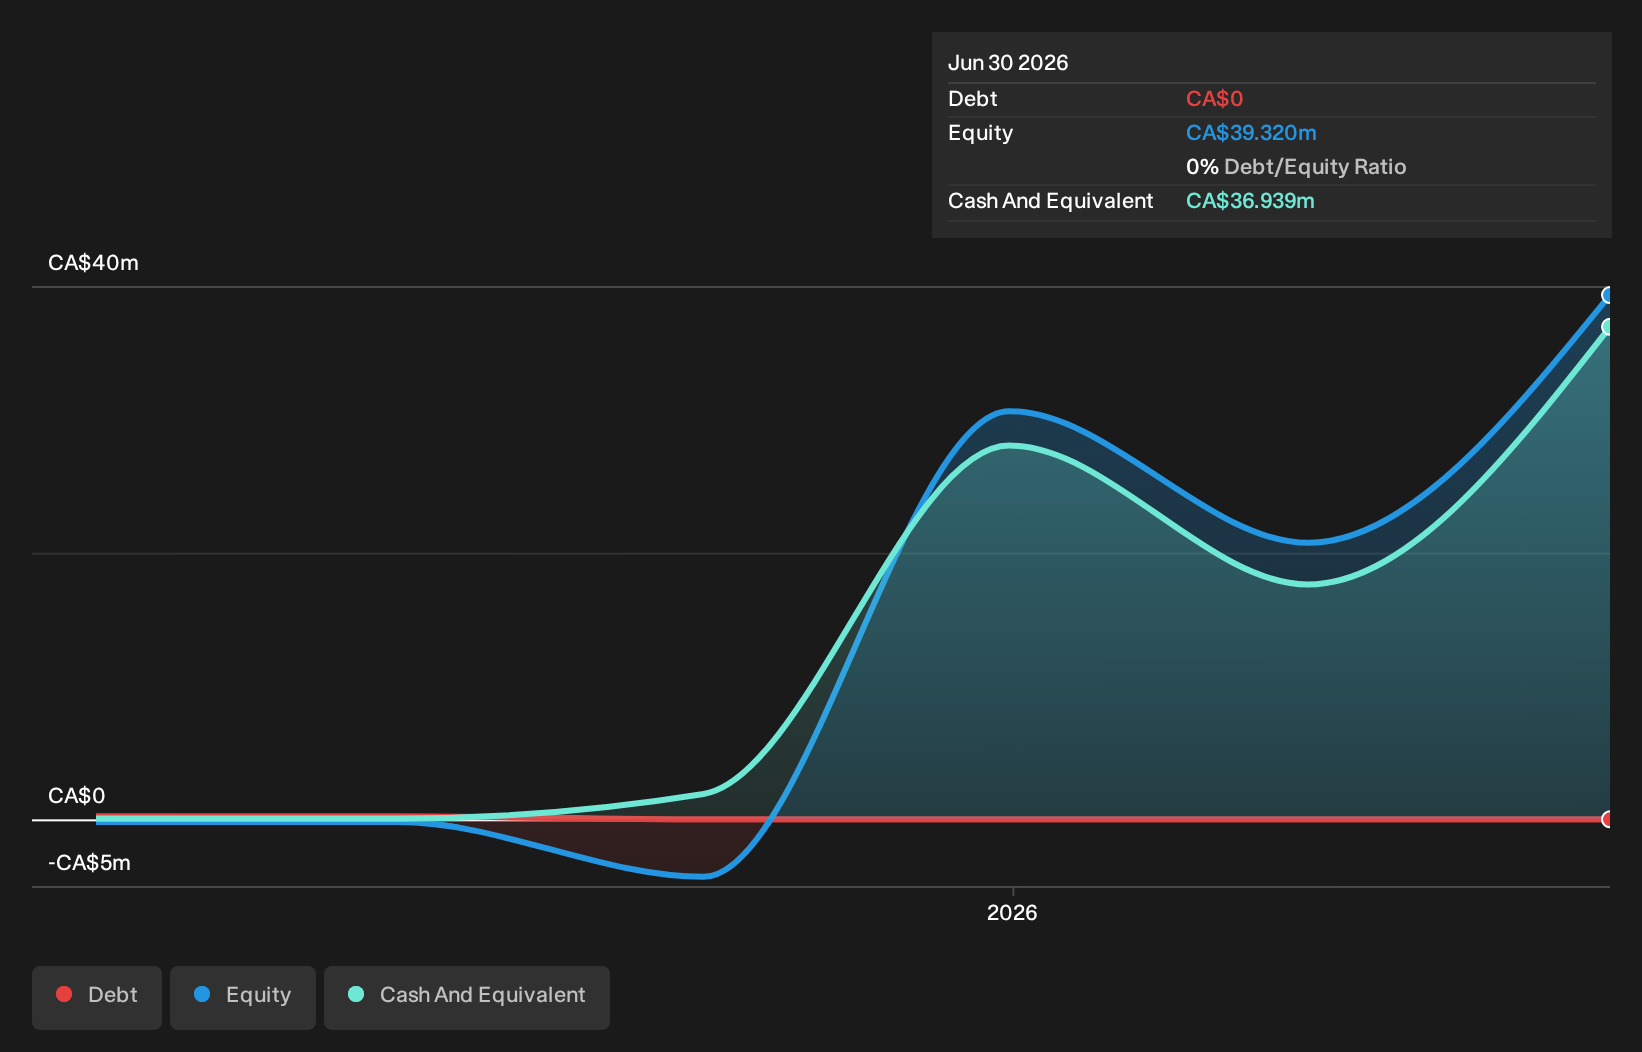
See our latest analysis for Selkirk Copper Mines
How Is Selkirk Copper Mines' Cash Burn Changing Over Time?
Selkirk Copper Mines didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. Its cash burn positively exploded in the last year, up 5,598%. Given that sharp increase in spending, the company's cash runway will shrink rapidly as it depletes its cash reserves. Admittedly, we're a bit cautious of Selkirk Copper Mines due to its lack of significant operating revenues. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
Can Selkirk Copper Mines Raise More Cash Easily?
Given its cash burn trajectory, Selkirk Copper Mines shareholders should already be thinking about how easy it might be for it to raise further cash in the future. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Selkirk Copper Mines has a market capitalisation of CA$182m and burnt through CA$39m last year, which is 22% of the company's market value. That's fairly notable cash burn, so if the company had to sell shares to cover the cost of another year's operations, shareholders would suffer some costly dilution.
So, Should We Worry About Selkirk Copper Mines' Cash Burn?
Selkirk Copper Mines is not in a great position when it comes to its cash burn situation. While its cash burn relative to its market cap wasn't too bad, its increasing cash burn does leave us rather nervous. After looking at that range of measures, we think shareholders should be extremely attentive to how the company is using its cash, as the cash burn makes us uncomfortable. Taking a deeper dive, we've spotted 3 warning signs for Selkirk Copper Mines you should be aware of, and 2 of them make us uncomfortable.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.