


Is Parsons (PSN) Undervalued As PFAS Cleanup Progress Revives The Debate?
Parsons (PSN) just received a Success Memo from the U.S. Department of War’s ESTCP and the Defense Innovation Unit for its PFAS soil remediation work, opening the door to follow-on federal cleanup contracts.
Parsons’ Success Memo arrives after a sharp short-term bounce, with a 1-day share price return of 5.29% and a 30-day share price return of 8.41% contrasting with a weaker year-to-date share price return. The 1-year total shareholder return has declined 43.31%, which indicates that recent momentum is improving after a tougher stretch for longer term holders.
Scan beyond Parsons and see how other contractors with environmental and infrastructure exposure are setting up right now with the curated list of solid balance sheet and fundamentals (26 results).
Parsons has just moved higher on the PFAS news after a tough year for long-term holders. Is this a reset worth leaning into now, or does patience on the entry price still look more attractive as valuation comes under the microscope next?
Most Popular Narrative: 20% Undervalued
Parsons last closed at $47.80, while the most followed thesis on the stock pegs fair value closer to $59.64. The current debate centers on whether investors are pricing recent contract issues too heavily relative to its backlog and margin ambitions. That narrative rests on Parsons shifting its work mix toward higher margin, software and AI led federal programs and away from riskier construction and legacy joint ventures that have weighed on reported results.
The main thing that has to go right is Parsons successfully executing its portfolio mix shift toward higher margin, product and AI driven federal work while continuing to wind down and exit lower return or higher risk construction and advisory contracts without further large charges.
The current valuation implies the share price reflects concern about guidance cuts and recent one off losses more than the size and duration of Parsons’ backlog, product programs and identified long runway in infrastructure and environmental remediation.
See why 13 investors see Parsons as 20% undervalued.
Result: Fair Value of $59.64 (UNDERVALUED)
Still, the Q2 2026 losses tied to contract exits and the cut to 2026 revenue guidance show how quickly the Parsons narrative can swing if problems resurface.
Find out about the key risks to this Parsons narrative.
Another View: Parsons Looks Rich On Earnings
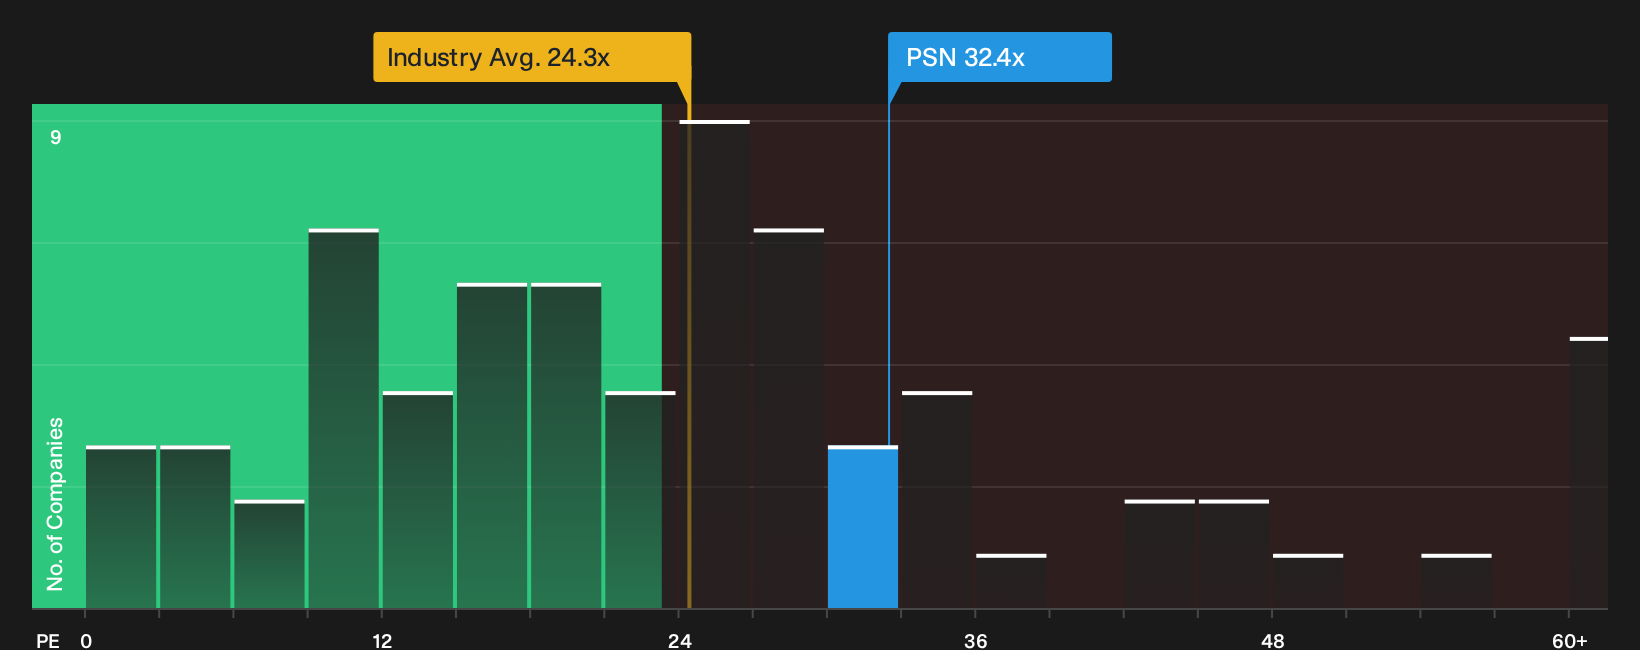
The fair value narrative paints Parsons as undervalued at $47.80 versus a $59.64 estimate, yet the simple P/E check sends a different message. The stock trades on a 32.4x P/E, above both its 31.2x fair ratio and the US Professional Services average of 23.4x. That richer starting point can limit upside if sentiment cools again. How much weight do you put on earnings multiples versus narrative fair values?
For a closer look at how this earnings based view lines up with peers and the fair ratio the market could move toward next, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Parsons is split, with real concerns on one side and clear upside arguments on the other. Move quickly to review the underlying data yourself before opinions harden, and then weigh both angles with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Parsons?
Parsons might be on your radar today, but your next strong candidate could come from a very different corner of the market. Use the tools at your fingertips to pressure test assumptions, compare risk profiles, and maintain a fresh bench of potential opportunities before the crowd turns its attention there.
- Target resilient balance sheets that can handle shocks by scanning the curated list of solid balance sheet and fundamentals (26 results).
- Hunt for quality on sale by working through the focused 29 high quality undervalued stocks.
- Zero in on quieter opportunities that others may be overlooking with the carefully filtered 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com