


Global Growth Companies With Strong Insider Ownership
In recent weeks, global markets have been characterized by a rotation away from large-cap growth stocks due to concerns over AI infrastructure spending and inflation pressures, with investors shifting focus toward value-oriented and defensive segments. Amidst this backdrop, companies with strong insider ownership can offer an additional layer of confidence for investors, as significant insider stakes may indicate alignment between management and shareholder interests during volatile market conditions.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.8% |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
Suzhou Novosense Microelectronics (SHSE:688052)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Suzhou Novosense Microelectronics Co., Ltd. operates in the semiconductor industry, focusing on the design and development of microelectronic products, with a market cap of approximately CN¥29.32 billion.
Operations: Suzhou Novosense Microelectronics generates its revenue from various segments within the semiconductor industry, focusing on the design and development of microelectronic products.
Insider Ownership: 21.7%
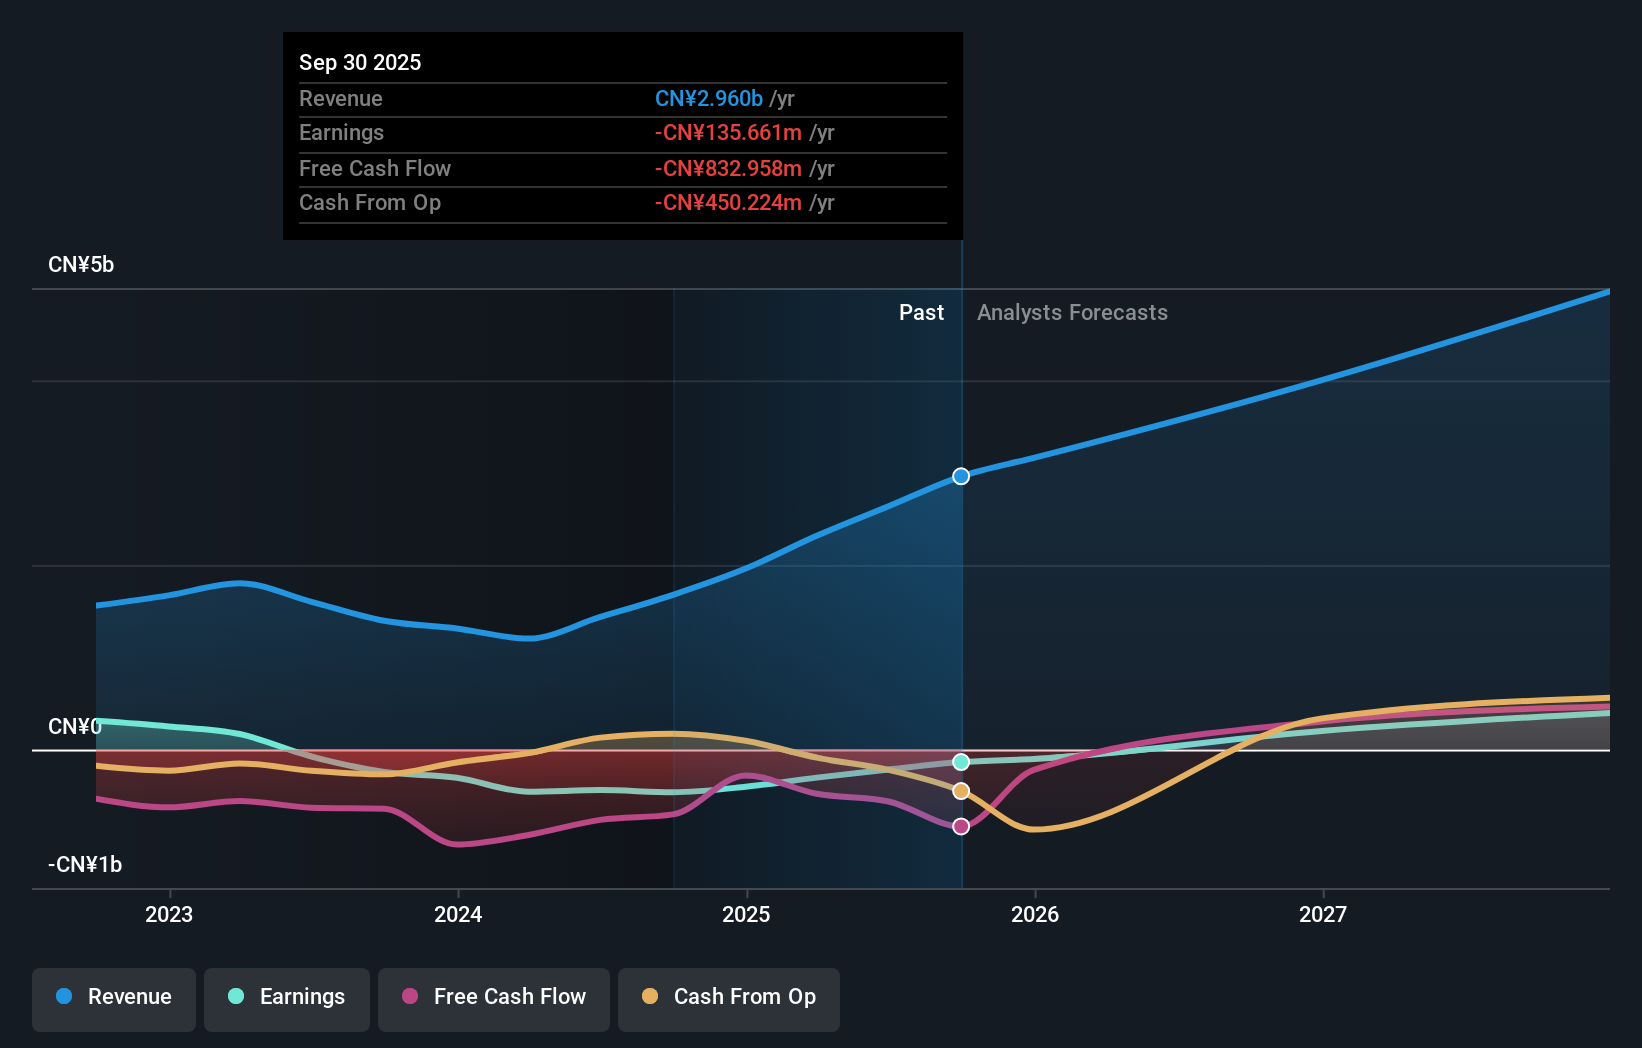
Suzhou Novosense Microelectronics has demonstrated significant growth potential, with its revenue forecasted to expand by 22.7% annually, outpacing the Chinese market average of 16.2%. Recent earnings show a positive turnaround with net income reaching CNY 67.59 million for H1 2026 from a prior loss. The company is trading slightly below its fair value estimate and aims for profitability within three years, though it faces challenges such as past shareholder dilution and share price volatility.
- Get an in-depth perspective on Suzhou Novosense Microelectronics' performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Suzhou Novosense Microelectronics shares in the market.
Cambricon Technologies (SHSE:688256)
Simply Wall St Growth Rating: ★★★★★★
Overview: Cambricon Technologies Corporation Limited focuses on the research, development, design, and sale of core AI chips for terminal devices in China with a market cap of CN¥555.34 billion.
Operations: Cambricon Technologies generates its revenue primarily from the research, development, design, and sale of AI chips for terminal devices in China.
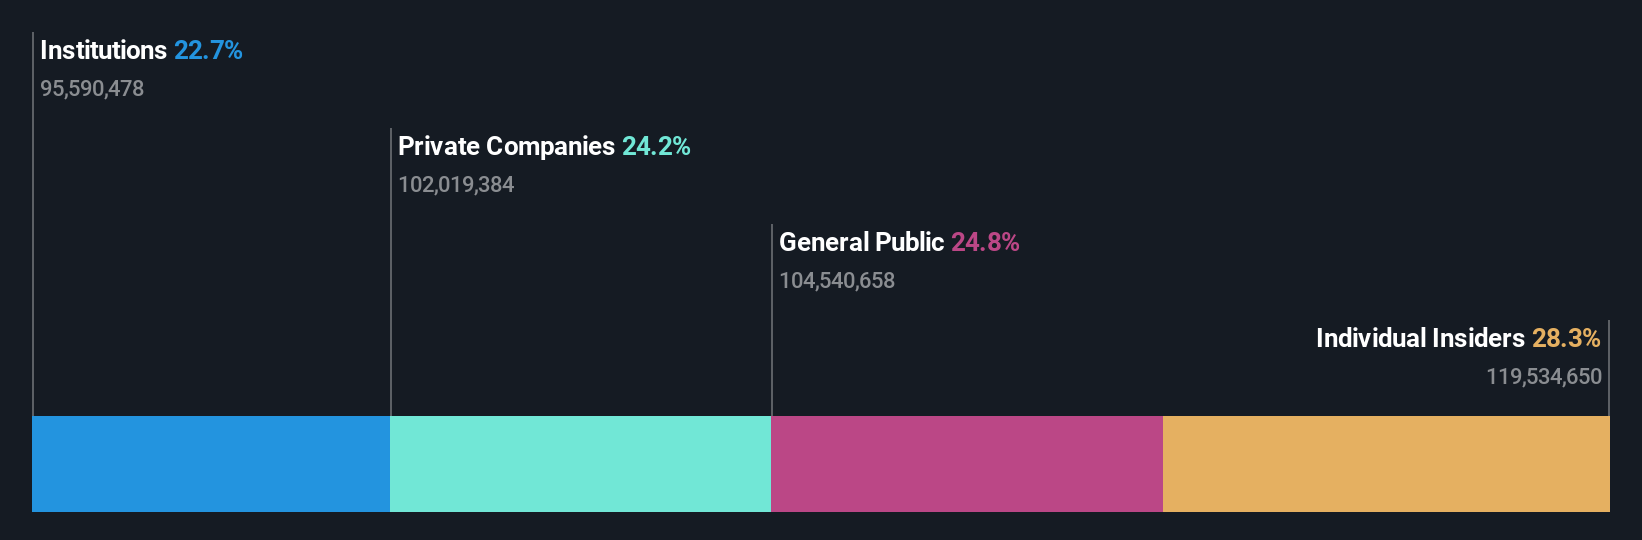
Insider Ownership: 30%
Cambricon Technologies shows strong growth prospects with earnings projected to rise 43.1% annually, surpassing the Chinese market's average. Revenue is also set to increase by 41.3% per year, significantly outpacing the market rate of 16.2%. Recent financials highlight substantial improvements, with H1 2026 sales at CNY 5.99 billion and net income at CNY 2.31 billion, reflecting robust performance despite share price volatility and high non-cash earnings levels.
- Click here and access our complete growth analysis report to understand the dynamics of Cambricon Technologies.
- Insights from our recent valuation report point to the potential overvaluation of Cambricon Technologies shares in the market.
NextVision Stabilized Systems (TASE:NXSN)
Simply Wall St Growth Rating: ★★★★★★
Overview: NextVision Stabilized Systems, Ltd. develops, manufactures, and markets stabilized day and night cameras for ground and aerial vehicles in Israel and internationally with a market cap of ₪17.97 billion.
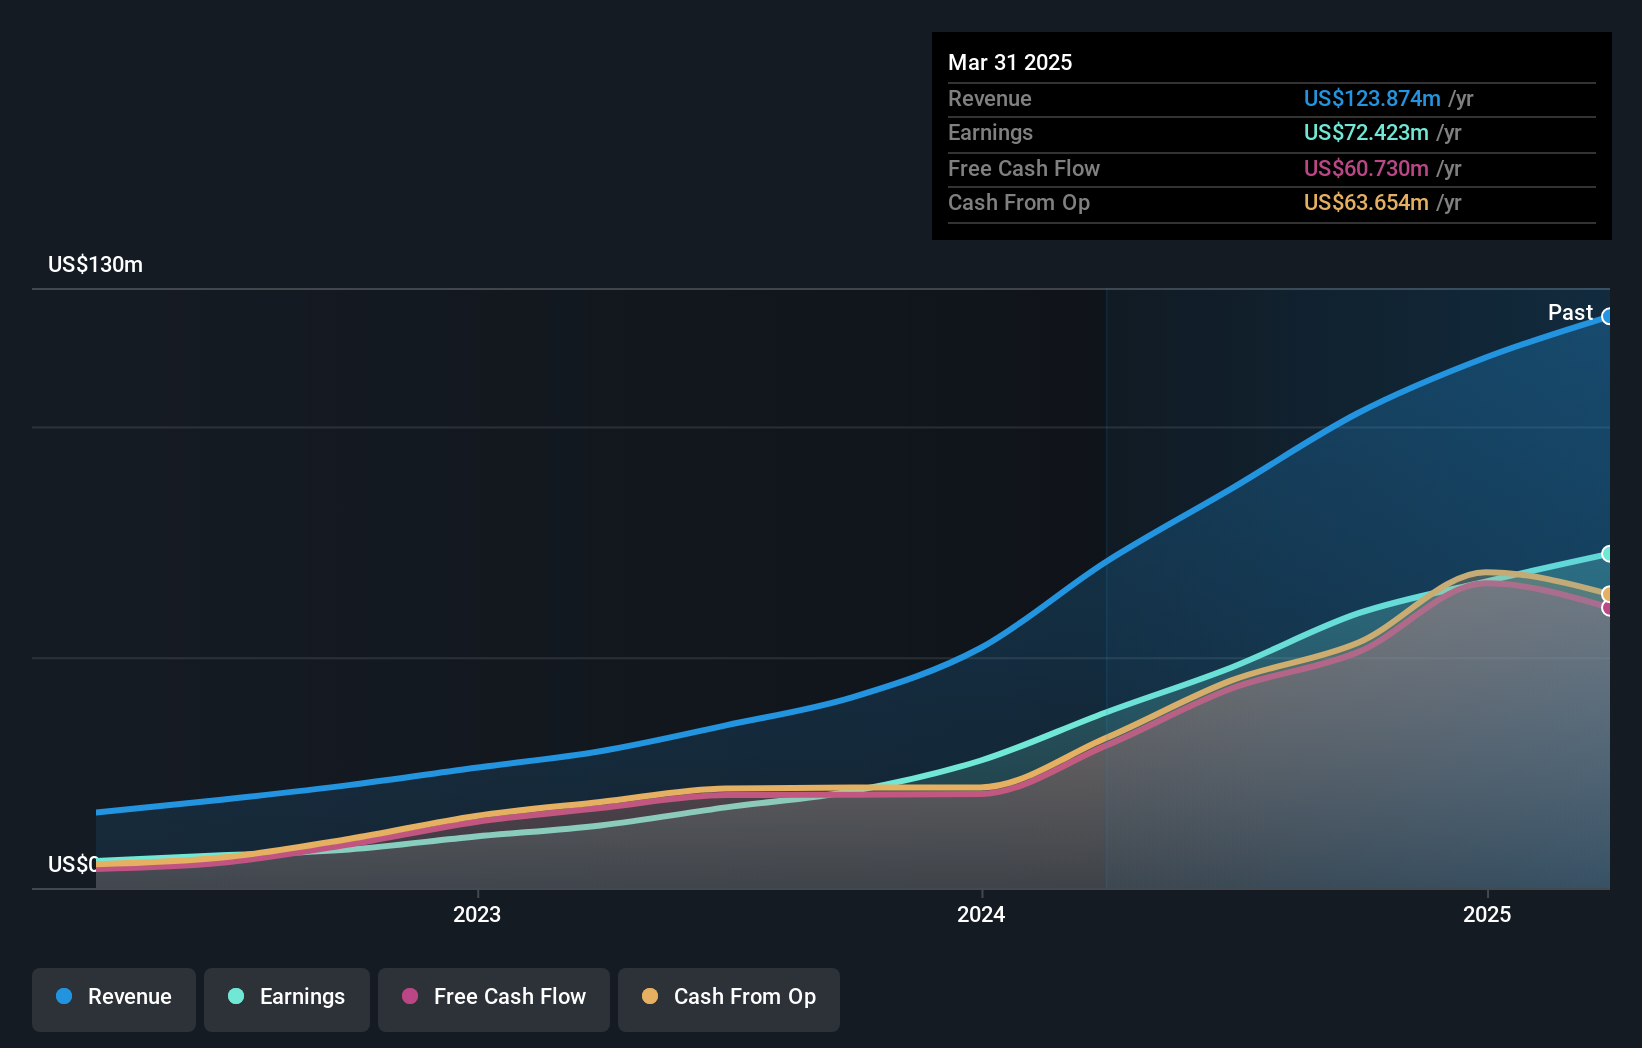
Operations: The company's revenue segment includes electronic security devices, generating $250.65 million.
Insider Ownership: 16.1%
NextVision Stabilized Systems demonstrates strong growth potential with forecasted revenue growth of 25.1% annually, outpacing the IL market's 9.6%. The company projects significant earnings growth at 25.8% per year, exceeding the market average of 13.4%. Despite recent share price volatility, NextVision raised its 2026 revenue target to US$355 million, reflecting a substantial increase over previous guidance. Recent orders totaling over US$50 million enhance its financial outlook for upcoming quarters.
- Unlock comprehensive insights into our analysis of NextVision Stabilized Systems stock in this growth report.
- The analysis detailed in our NextVision Stabilized Systems valuation report hints at an inflated share price compared to its estimated value.
Where To Now?
- Discover the full array of 732 Fast Growing Global Companies With High Insider Ownership right here.
- Ready To Venture Into Other Investment Styles? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com