


Is Clearway Energy (CWEN) A Bargain As Its Hyperscale Renewable Projects Advance?
Clearway Energy (CWEN) is moving ahead with several large scale renewable complexes tied to data hungry hyperscale customers, bringing renewed focus to how these contracted projects might influence its future cash generation.
The share price is US$31.43 after a 1-day move that slipped 0.57%. However, the 7-day share price return of 4.91% hints at renewed interest as these large projects gain attention.
Over a longer stretch, the year-to-date share price return is down 7.45%. Even so, the 1-year total shareholder return of 4.93% and 3-year total shareholder return of 66.37% indicate that investors who stayed invested in Clearway Energy have seen meaningfully better results than short-term traders focused on recent volatility.
Scan other grid and data infrastructure players with a similar energy demand backdrop by reviewing the curated 42 power grid technology and infrastructure stocks.
Clearway Energy now trades below its year-to-date level, yet sits on much stronger multi-year returns. Is this a reasonable entry point, or does it pay to stay patient and wait for a pullback?
Most Popular Narrative: 22% Undervalued
Clearway Energy’s most followed narrative pegs fair value around $40.43 against the recent $31.43 share price, framing the current level as a discount that leans heavily on contracted data center power demand and a deep project queue.
Expansion of late stage wind, solar and storage projects, with 100% of 2026 and 2027 vintages already commercialized and a 2028 to 2029 pipeline larger than what is needed for internal CAFD targets, gives the company multiple ways to add contracted capacity that can lift CAFD and support dividend coverage.
See why 10 investors see Clearway Energy as 22% undervalued.
Result: Fair Value of $40.43 (UNDERVALUED)
Still, if data center power demand slows or tax credit and permitting rules tighten, the Clearway Energy buildout and cash flow story could look very different.
Find out about the key risks to this Clearway Energy narrative.
Another View: Clearway Energy Looks Expensive On Earnings
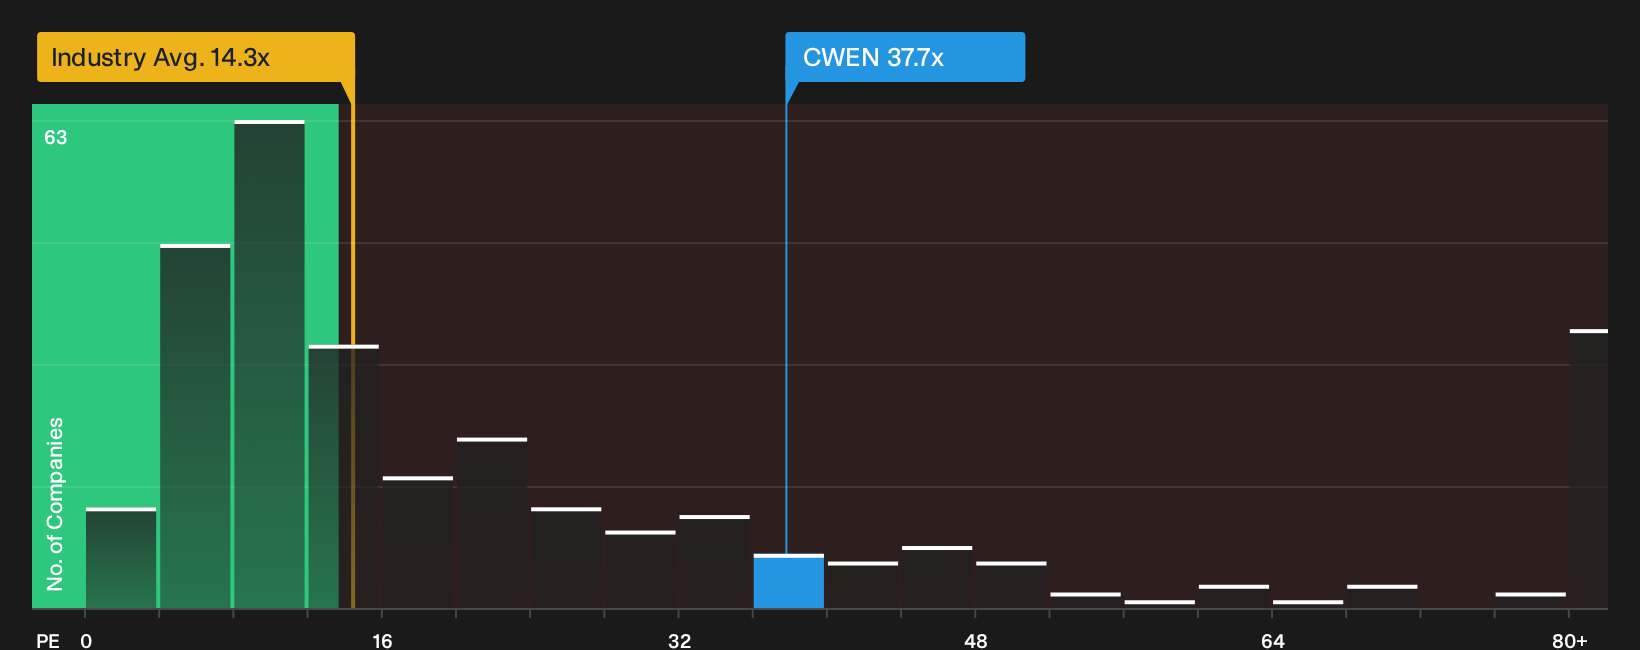
On the flip side of that US$40.43 fair value narrative, Clearway Energy’s current P/E of 37.7x screens as rich. It sits above the peer average of 29x, the global Renewable Energy industry on 14.3x, and even the 25.9x fair ratio that the market could move toward over time.
If the share price drifts closer to that fair ratio or even peer levels, current buyers would be paying up for growth that already sits in the multiple. The question is whether you are comfortable underwriting that gap, or whether it makes more sense to wait for sentiment to reset before reassessing valuation risk.
For a closer look at how this earnings-based view lines up with the rest of the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if they push you to check the numbers yourself and decide where you stand on Clearway Energy. Act while sentiment is balanced by weighing both sides of the story through the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Clearway Energy?
If Clearway Energy has you rethinking your watchlist, use that momentum and run a quick screen for other setups that fit your style.
- Target potential mispricings by scanning the 29 high quality undervalued stocks that pair strong fundamentals with what may be more modest expectations baked into current prices.
- Prioritise resilience first by reviewing a 30 resilient stocks with low risk scores that aims to keep drawdowns in check while you stay invested through different market conditions.
- Spot under-the-radar opportunities by checking a 20 high quality undiscovered gems that many investors have not yet added to their core watchlists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com