


Del Monte (DMC) Unveiled New Products, Is The Stock 42% Undervalued?
How Del Monte’s New Product Wave Frames The Stock Story
Del Monte (DMC) just rolled out six fresh items plus new pineapple formats that tie its Fresh and Foods teams together, giving investors a clearer view of how management is thinking about product breadth.
The lineup ranges from Red and Green Chimichurri sauces to an Açaí Parfait cup aimed at on the go snacking. Fresh produce gets more attention too through fruit kabobs, a Watermelon Feta Salad, a Premium Snack Fruit Trio Tray built around Honeyglow and Pinkglow pineapple, and Medjool dates sourced from the Jordan Valley.
The fresh product story is landing against a mixed share performance for Del Monte, with the US$29.93 stock jumping 7.28% on a 1 day share price return but still down 15.26% on a year to date share price basis, while the 3 year total shareholder return of 31.07% points to longer term holders seeing a very different experience to the recent pullback.
Scan other food and consumer staples stocks that show similar product-led momentum using our curated 20 high quality undiscovered gems.
After a sharp 1 day jump to US$29.93, but a weaker year-to-date share price record, does it make more sense to step into Del Monte now or wait for a cheaper swing point before the valuation work starts?
Most Popular Narrative: 42% Undervalued
At a last close of $29.93 against a narrative fair value of $52.00, Del Monte is framed as materially discounted, with the debate shifting toward whether its higher margin mix shift can show up quickly enough in reported earnings.
Integration of Del Monte Foods into a single, unified Del Monte brand creates a larger prepared foods platform that is expected to contribute about US$625 million of net sales and US$35 million of adjusted EBITDA in 2026, which could support a higher mix of branded, higher-margin earnings.
See why 15 investors see Del Monte as 42% undervalued.
Result: Fair Value of $52 (UNDERVALUED)
Still, the Del Monte story can change quickly if banana pricing stays under pressure or if freight and farm input costs continue to eat into margins.
Find out about the key risks to this Del Monte narrative.
Another View: What P/E Says About Del Monte
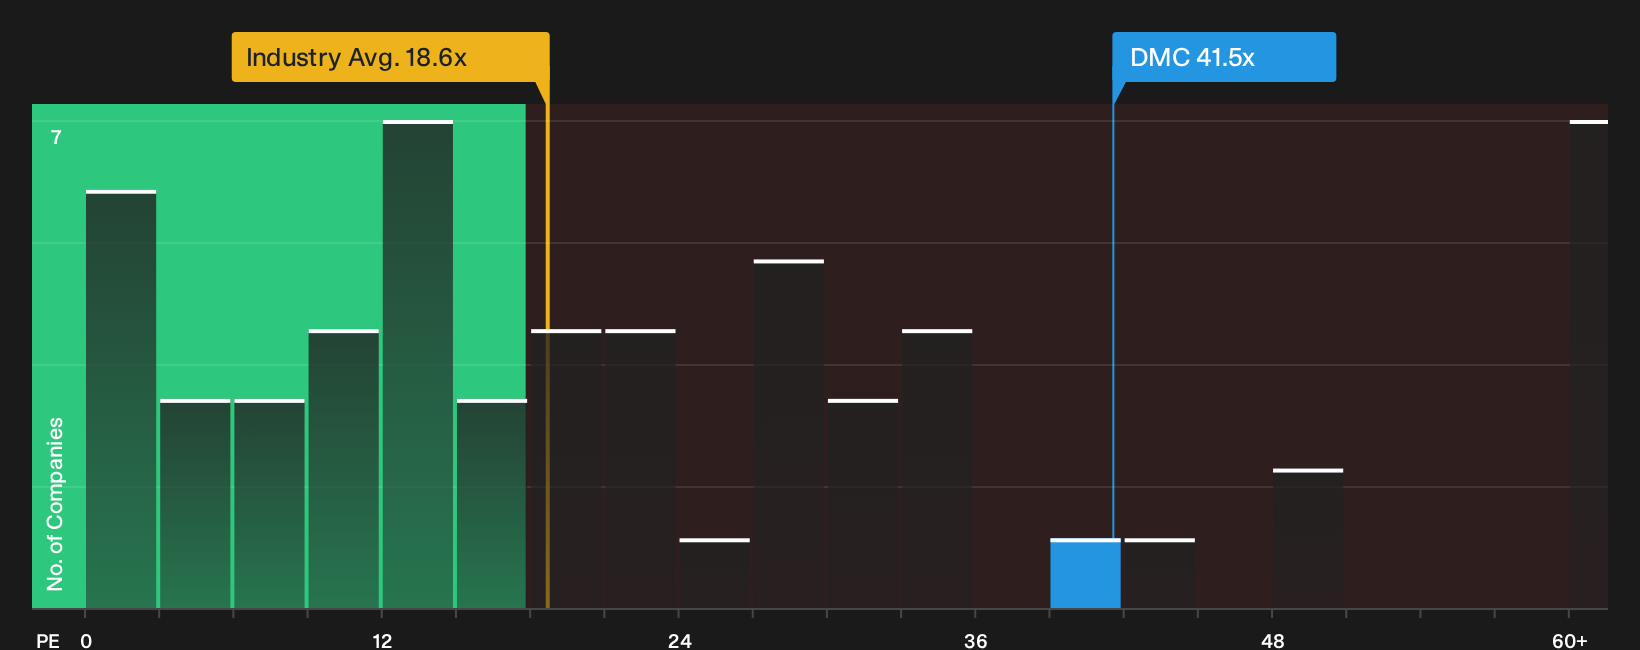
On simple P/E math, Del Monte looks expensive at 41.5x earnings compared with 18.6x for the wider US Food group, even though peers average a much richer 54.8x. The fair ratio sits far higher at 95.7x. Is the share price cautious, or is the model too generous?
For a closer look at how that earnings multiple could evolve and what it might mean for valuation risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Del Monte so far. If that leaves you on the fence, go directly to the source data and weigh both the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Del Monte?
If Del Monte has sharpened your appetite for opportunities, broaden your watchlist now with focused stock ideas that match how you like to invest.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (26 results).
- Hunt for potential mispricing by reviewing the 29 high quality undervalued stocks.
- Aim for stability plus income by checking out the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com