


DraftKings (DKNG) Stock May Be Reasonable Despite NBA Betting Limits
DraftKings has seen its share price fall 55.6% over the past five years, even as the U.S. sports betting market has become more crowded and heavily marketed. With investors now paying close attention to how much revenue the platform actually generates, the open question is whether the current US$20.94 share price is justified by its sales.
- The five year share price decline of 55.6% puts the focus squarely on what investors are getting in terms of sales for every dollar paid for DraftKings stock.
- Rising competitive marketing spend and tighter betting rules around NBA wagers can influence how quickly DraftKings grows its top line and how much it may need to reinvest to protect that revenue base.
- The analysts covering DraftKings have run their own numbers. See what analysts think DraftKings's shares could be worth.
The issue now is whether the valuation investors are placing on DraftKings today makes sense when measured against the revenue the business currently generates.
If you want to test whether the same sales focused question on price applies beyond DraftKings, you can scan opportunities using the 29 high quality undervalued stocks.
Does DraftKings Look Undervalued on Sales?
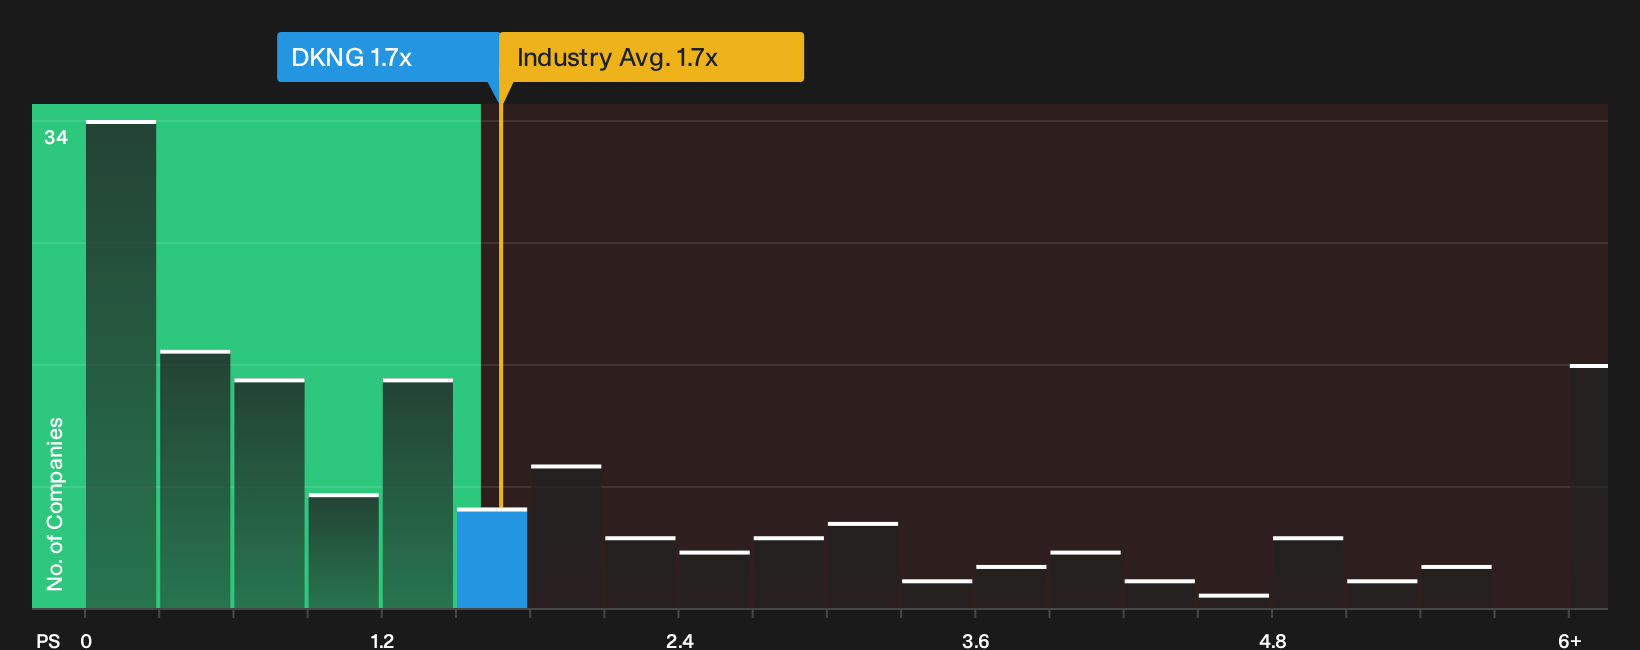
P/S is a cleaner yardstick for DraftKings because the business is still working through losses and accounting noise at the bottom line. On this measure, the stock trades on a P/S ratio of 1.7x, which is almost exactly in line with the wider hospitality industry average of 1.7x. Against its direct rivals, the picture is different, since the peer group average sits lower at about 1.2x. This means the current tag asks you to pay more revenue per dollar than many competitors.
The Fair Ratio model, which adjusts the P/S anchor for DraftKings' own growth profile, margins, size and risk, points to a higher multiple than where the shares change hands today. As a result, the current P/S signals the stock screens undervalued on this framework. Because NBA betting restrictions have taken some shine off near term sentiment, that softer backdrop makes the discount on this sales multiple more striking for anyone weighing the long term revenue story against regulatory and marketing pressure. Explore the numbers behind DraftKings's P/S valuation.
The DraftKings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DraftKings valuation question leaves off. They spell out which combinations of future growth, profitability and earnings paths would need to play out for the stock to look meaningfully cheap or expensive versus today's price on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and risks so you can track over time which version of DraftKings' story is actually unfolding.
Community views on DraftKings split between those who think the revenue engine is underappreciated and those who worry the quality of that income stream is stretched.
Bull case: 39% undervalued
"Expansion of DraftKings Predictions as a vertically integrated product, with over 600,000 customers year to date 2026 and annualized traded volume rising from US$2.3b in April to US$11b in July…"
Discover why this Narrative puts DraftKings at 39% undervalued.
Bear case: roughly fairly valued
"Although DraftKings is reporting solid adjusted EBITDA in the core business, the 4.6% year-over-year fall in Q2 2026 revenue to US$1.44b and a 4.5% revenue miss against expectations signal that weaker hold and heavier acquisition spending could be symptoms of a business that needs structurally higher marketing and promotional intensity…"
Explore why this Narrative puts DraftKings at roughly fairly valued.
One more DraftKings cross-check before you move on
Price ratios tell you what the market pays today, but the analyst models looking a few years out show what professionals currently expect this business to become. Explore where analysts expect DraftKings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com