


Why Everyone Is Watching Convatec Group (LSE:CTEC) Today
Vizient awards put fresh attention on Convatec Group shares
Convatec Group (LSE:CTEC) has just picked up two supplier awards from Vizient, a large US healthcare performance improvement group. The recognition centres on advanced wound care, ostomy care, and bowel management.
Investors now have a fresh prompt to look at how this medical products specialist is priced, how it makes money, and where recent share moves might fit into that picture.
Recent moves have been quietly positive. Convatec Group’s 1 day share price return of 1.67% and 1 week gain of 3.04% contribute to a 30 day share price return of 13.38% and a 90 day move of 12.96%. Meanwhile, the 3 year total shareholder return of 28.91% and 5 year figure of 37.03% show a steadier build up in value, suggesting momentum has been improving as investors factor in recognition such as the Vizient awards and shifts in perceived business risk.
Spot fresh momentum around Convatec Group, then scan a curated shortlist of healthcare-focused opportunities in the 8 healthcare AI stocks that could be setting up for their next move.Convatec Group shares have already logged a solid run after the Vizient news, yet the valuation still points to a sizeable discount. Is the bigger opportunity now ahead of the latest rally or behind it?
Most Popular Narrative: 19% Undervalued
The most followed valuation storyline for Convatec Group puts fair value at £3.02 per share against the latest £2.44 close, framing the Vizient awards against a model that already saw upside before this latest news hit the tape.
Ongoing investment in product innovation and R&D, as seen in the robust pipeline (e.g., ConvaNiox, ConvaVac, next-gen infusion sets), is enabling differentiation, premium pricing, and enhanced gross margins, positioning the company to maintain or expand net margins despite reimbursement volatility.
See why 20 investors see Convatec Group as 19% undervalued.
That narrative uses an 8.39% discount rate and blends those product pipeline assumptions with analyst forecasts, which call for earnings to grow 25.7% a year and margins to settle near 14.7%. The result is a fair value of £3.02, around 19% above the quoted price, and it sits alongside a separate Simply Wall St DCF view that places future cash flow value materially higher again at £4.24 per share.
Analysts in that consensus framework are effectively asking investors to weigh a current net income of $124.0m on revenue of $2.49b against a longer term picture that includes higher profitability, a forecast return on equity of 25% and share count drifting lower. On the flip side, they also factor in real pressure points, including a 5% net margin that is below last year’s 9.2%, a high level of debt, reimbursement exposure on around 12% of group sales, and a dividend yield of 2.22% that is not well covered by earnings or free cash flow.
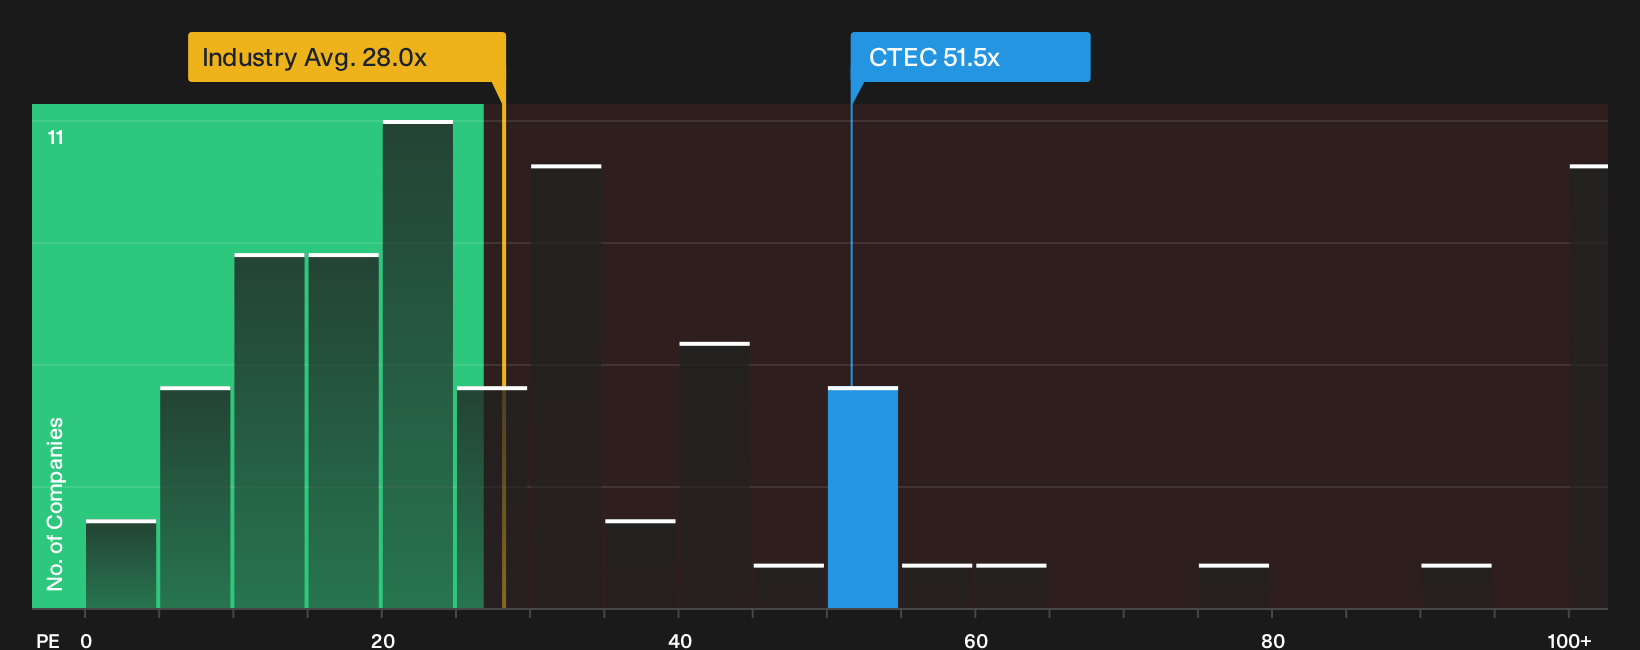
Put together, the fair value work suggests the share price is not simply reacting to the Vizient awards in isolation. It is sitting at a level that the prevailing narrative still treats as below both a £3.02 central estimate and a £4.24 future cash flow value, while also assigning a relatively high current P/E of 51.5x against an estimated fair P/E of 36.5x and an industry multiple of 26.3x.
Result: Fair Value of £3.02 (UNDERVALUED)
Still, the biggest swing factors for that Convatec Group storyline involve potential US reimbursement cuts on roughly 12% of sales, as well as any further delays or underperformance in the product pipeline.
Find out about the key risks to this Convatec Group narrative.
Another View: Convatec Group Through A P/E Lens
The SWS DCF model points to Convatec Group shares trading below estimated future cash flow value, yet the earnings multiple sends a different signal. The current P/E of 51.5x is far above both the fair ratio of 36.5x and the European Medical Equipment industry on 26.3x, even if it sits below the 65.1x peer average. That gap leaves investors weighing whether they are paying up for forecast profit growth or accepting more valuation risk than the fair ratio implies.
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Convatec Group is mixed, with real risks on one side and genuine bright spots on the other. Act quickly and test the data yourself to see which matters more for you, then weigh both angles through the 3 key rewards and 4 important warning signs
Looking for more Convatec Group sized opportunities?
If you stop with Convatec Group, you risk missing other setups that fit your style. Put a few minutes into scanning targeted ideas that match your goals.
- Target strong value potential by zeroing in on companies that combine quality fundamentals with appealing prices through the 7 high quality undervalued stocks.
- Build a steadier income stream by focusing on reliable payers with higher yields using the 4 dividend fortresses.
- Prioritise resilience by filtering for businesses with robust finances and low risk profiles through the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com