


MarineMax (HZO) Is Getting Attention, So What Is Behind It?
MarineMax (HZO) moved into the spotlight after Halper Sadeh LLP announced an investigation into its agreed sale to Safe Harbor Marinas for $53.00 per share in cash. The move has put the deal terms and shareholder protections under scrutiny.
MarineMax now trades at US$52.38, just below the agreed US$53.00 cash offer, after a strong run that included a 44.2% 3 month share price return and a 117.5% year to date share price gain, alongside a 99.8% 1 year total shareholder return that reflects how the market has reassessed both upside potential and deal related risks.
Scan the takeover action around MarineMax and then size up other potential targets or rerating candidates with our curated 20 high quality undiscovered gems.
After a near triple digit 1-year total return and a takeover bid that almost matches the current quote, MarineMax now faces a simple question: Is there still enough potential upside to justify taking on new risk from this point as the valuation work begins?
Most Popular MarineMax Narrative: 6% Overvalued
Against the last close at $52.38, the most widely followed MarineMax narrative pegs fair value at $49.40 using a 10.4% discount rate. That gap is small, yet it reflects a view that the agreed $53.00 offer already captures much of the expected earnings recovery.
Expansion into higher margin service and marina activities, including parts and service, finance and insurance, marinas and superyacht services, which recently lifted consolidated gross margin into the mid 30% range, can continue to increase the share of recurring revenue and support more resilient net margins.
See why 7 investors see MarineMax as 6% overvalued.
Result: Fair Value of $49.40 (OVERVALUED)
Still, shrinking U.S. powerboat registrations and MarineMax boat margins that sit roughly 300 to 400 basis points below pre COVID levels could quickly challenge that fair value story.
Find out about the key risks to this MarineMax narrative.
Another View on MarineMax Valuation
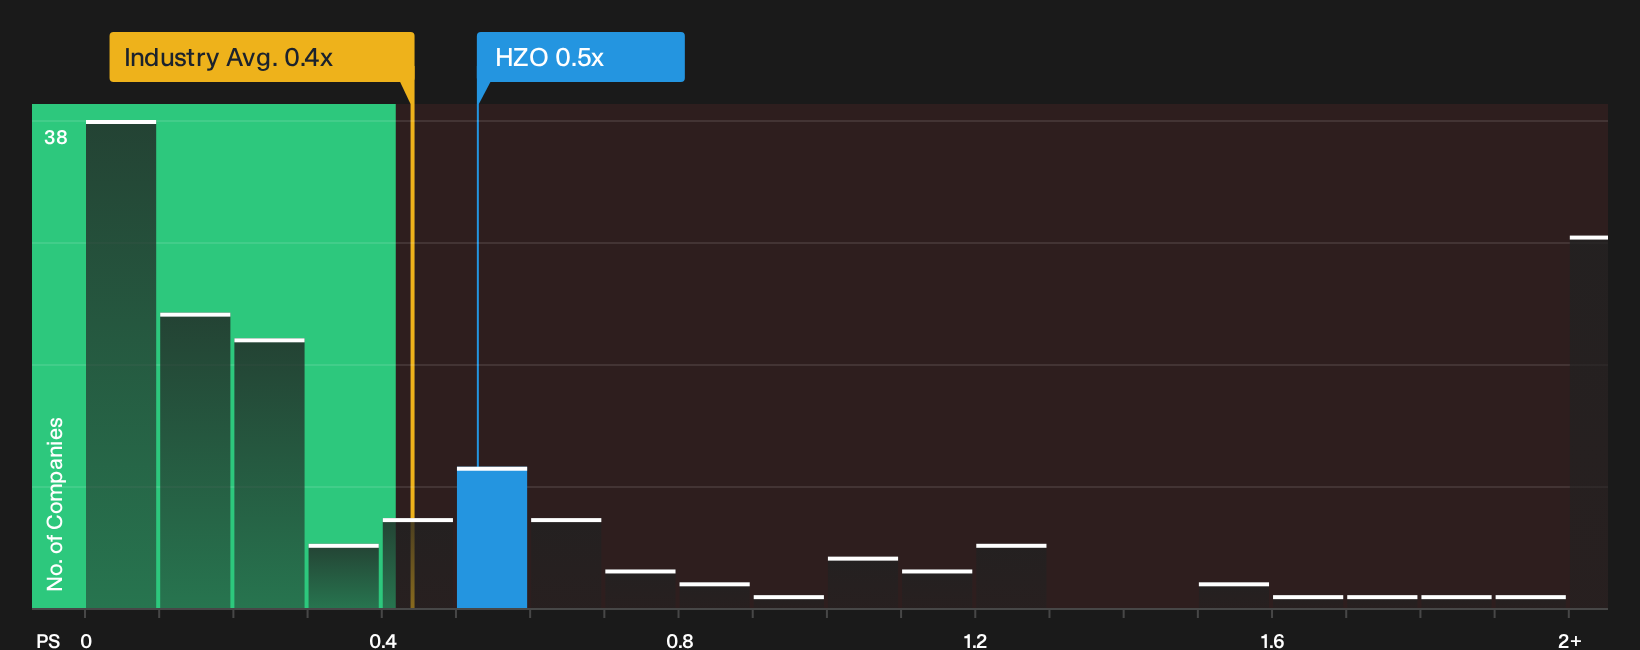
The story shifts when you stop looking at future earnings and focus on what investors pay for today’s revenue. On a P/S of 0.5x, MarineMax screens cheaper than a 3.1x peer average, yet it trades above a 0.3x fair ratio estimate, which points to limited margin for error if sentiment cools.
To see how this stacks up when you anchor everything to current trading multiples rather than long range forecasts, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around MarineMax can create a lot of noise. Consider acting promptly, reviewing the underlying data yourself, and pressure testing your own thesis with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MarineMax?
If you stop with MarineMax, you only see one angle. Broaden your watchlist using focused screeners that surface companies by quality, value, and resilience.
- Hunt for mispriced opportunities that pair strong fundamentals with discounted valuations through the 29 high quality undervalued stocks.
- Prioritize payouts and stability by scanning the 6 dividend fortresses for companies with higher yielding distributions backed by solid metrics.
- Dial down portfolio risk and concentrate on durability with the 30 resilient stocks with low risk scores to spot businesses scoring well on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com