


LTC Properties (LTC) Stock Looks Undervalued As Earnings Stay In Focus
LTC Properties has delivered strong share price gains in recent years, and that kind of run naturally raises a question about whether the current valuation still lines up with its earnings power. With the stock around US$43.33 and investors watching a busy acquisition pipeline in senior housing, the issue is what those earnings actually justify.
- The share price has returned 75.9% over the past 5 years, which puts real weight on whether the earnings profile has kept pace with investor enthusiasm.
- Recent acquisitions of senior housing communities, funded by recycling capital from asset sales, can reshape LTC Properties' earnings mix and may support different expectations for margins and cash flow over the coming years.
- The analysts covering LTC Properties have run their own numbers. See what analysts think LTC Properties's shares could be worth.
For investors, the debate is whether LTC Properties' recent share price level is adequately supported by the earnings it generates today and what those earnings may reasonably support over time.
If LTC Properties has you thinking about how earnings power and acquisition pipelines line up, it can help to compare that theme across a wider set of 29 high quality undervalued stocks.
Is LTC Properties Still Cheap on Earnings?
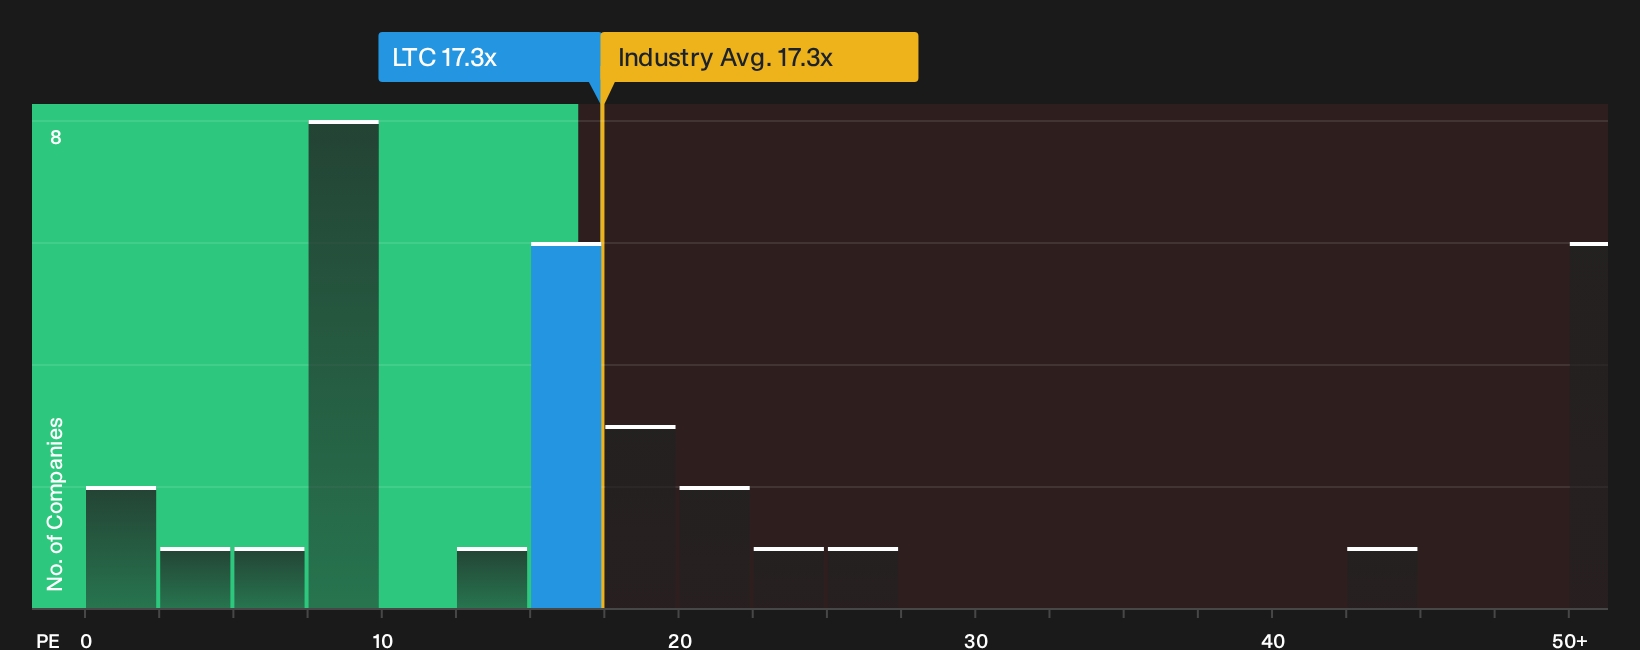
P/E tends to fit LTC Properties because investors often anchor senior housing REITs on steady earnings streams rather than rapid revenue swings. At about 17.3x P/E, the stock trades in line with the broader Health Care REITs group, where the average is also roughly 17.3x. Against that sector backdrop, LTC does not screen as richly priced or heavily marked down on headline earnings alone.
Compared with a tighter fair multiple implied by its own growth profile and risk mix, the current P/E comes in below what a more tailored model would suggest for LTC Properties, which leans toward it looking undervalued on this metric. Because recent SHOP acquisitions are pushing the portfolio closer to the 2026 investment target, the market is currently paying a P/E multiple that does not fully move away from the sector average despite the growing exposure to operating senior housing assets. Explore the numbers behind LTC Properties's P/E valuation.
The LTC Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for LTC Properties connect the current valuation puzzle to the assumptions behind it, by spelling out what would need to happen to future earnings, margins and growth for the stock to look meaningfully higher or lower than today’s price. Instead of stopping at a single output from a ratio or model, Narratives lay out the future path that figure rests on so you can keep checking whether that storyline still matches how LTC Properties' business evolves, and they live on Simply Wall St's Community page.
One of the top community narratives on LTC Properties: 6% undervalued
"The main thing that has to go right is LTC Properties executing its accelerated SHOP expansion and platform build, including meeting its acquisition and NOI targets..."
Discover why this Narrative puts LTC Properties at 6% undervalued.
An unresolved question for LTC Properties investors
LTC Properties' current valuation only tells you what the market is willing to pay today, while analyst projections a few years out offer a separate lens on where earnings power could realistically sit. Explore where analysts expect LTC Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com