


Forgent Power Solutions (FPS) Faces A CFO Reset As Valuation Questions Build
Forgent Power Solutions (FPS) is back in focus after Chief Financial Officer Ryan Fiedler resigned and long-time finance leader Amy Ard took the role. This shift coincided with a sharp share pullback.
Over the past month, Forgent Power Solutions has swung from hot IPO story to pressure test, with the share price down 35.3% on a 30 day share price return basis and 30.6% lower over 90 days as investors reassess leadership risk and growth expectations ahead of the upcoming earnings update. The year to date share price return of a 14.1% decline points to momentum that has clearly faded in the short term, despite a longer narrative still linked to its role in data center and grid infrastructure.
Scan how other power grid and data center suppliers have been moving since the Forgent Power Solutions selloff by reviewing our hand picked 42 power grid technology and infrastructure stocks today.
Forgent Power Solutions now trades at $24.92 while analyst targets cluster near $54.67 and some intrinsic estimates sit even higher. Is this gap pointing to mispricing, or does it reflect real concern about the new CFO era?
Preferred P/E of 93.8x: Is it justified?
Valuation on Forgent Power Solutions is being pulled in two directions, with a steep share price pullback but a P/E multiple that still sits at 93.8x earnings and well ahead of many peers. For anyone watching the stock at $24.92, that headline number alone raises a fair question about how much future profit growth is already built into expectations.
The P/E ratio compares what investors are willing to pay today for each dollar of current earnings, and it matters a lot for a capital goods business tied to data centers and grid upgrades where profits can be cyclical. A 93.8x P/E suggests the market is placing a strong emphasis on future earnings potential rather than the $72.925m of current net income on $1.42b of revenue.
Forecast data backs up that future focus, with earnings expected to grow 37.2% per year and revenue projected to expand 25.3% annually, both ahead of broader US market expectations. Earnings are also expected to grow at a rate considered significant over the next 3 years, and the firm is projected to reach a very high 63.4% Return on Equity in three years according to estimates, which can support paying a higher multiple if those forecasts prove accurate.
The tension sits in the comparison set. Forgent Power Solutions trades on a P/E that is described as expensive versus the US Electrical industry average of 31.9x, and also above a peer group average of 17.5x. In addition, the current P/E is higher than an estimated fair P/E of 57.7x, which implies the market is already assigning a premium that could compress if growth or returns fall short of expectations.
Explore the SWS fair ratio for Forgent Power Solutions.
Result: Price-to-Earnings of 93.8x (OVERVALUED)
Still, the Forgent Power Solutions story could shift quickly if earnings forecasts are cut or if leadership turnover raises fresh concern about execution.
Find out about the key risks to this Forgent Power Solutions narrative.
Another View on Forgent Power Solutions: Cash Flows Tell a Different Story
The rich 93.8x P/E makes Forgent Power Solutions look expensive, yet our DCF model paints a very different picture. On that cash flow view, FPS at $24.92 is trading below an estimated future cash flow value of $97.39, which frames the current pullback as a potential mispricing rather than pure overexcitement.
The gap between those two signals is wide in practical terms. One lens warns that expectations baked into earnings multiples are heavy, while the SWS DCF model argues the share price already discounts a lot of risk. Which lens do you think better reflects the kind of business FPS is becoming over the next few years?
Look into how the SWS DCF model arrives at its fair value.
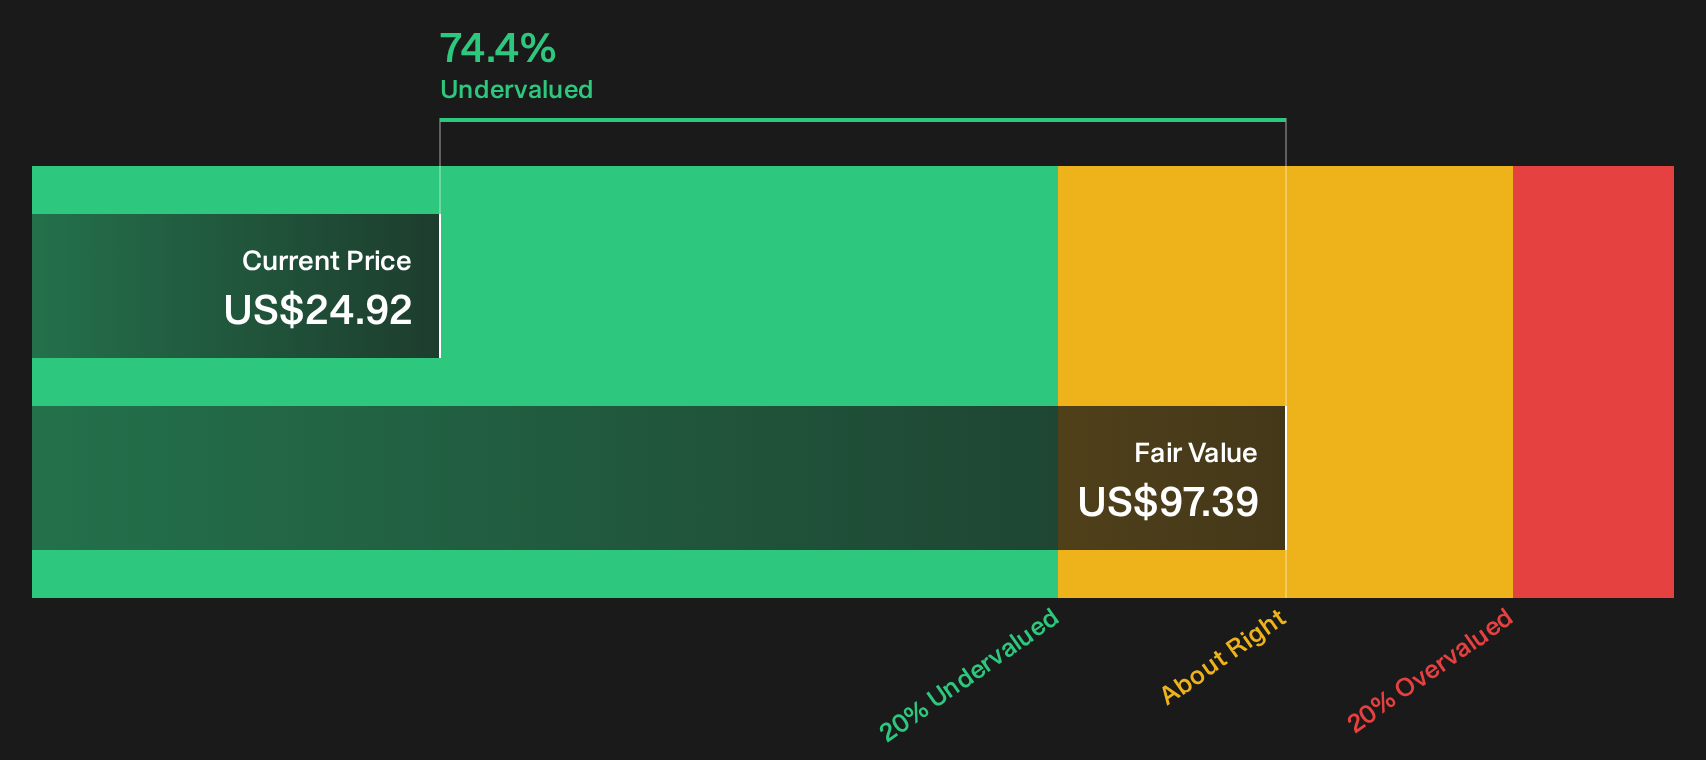
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Forgent Power Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Forgent Power Solutions clearly mixed, consider acting promptly and weigh the upside against the downside by reviewing the 3 key rewards and 2 important warning signs.
Looking for more Forgent Power Solutions style ideas?
If Forgent Power Solutions has your attention, do not stop here. Cast the net wider now so you are not chasing opportunities after they have moved.
- Target steady compounding by reviewing companies built on strong cash generation and healthy finances with the list of solid balance sheet and fundamentals (26 results).
- Hunt for mispriced opportunities by scanning the 30 high quality undervalued stocks where quality and pricing meet in a tighter margin of safety.
- Spot early stage potential by checking the 9 elite penny stocks with strong financials that pair smaller size with balance sheets and fundamentals that pass basic tests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com