


European Growth Stocks With High Insider Ownership In October 2026
As European markets navigate through geopolitical tensions and fluctuating energy prices, the STOXX Europe 600 Index has shown resilience with a notable advance, driven by a renewed focus on corporate fundamentals amid the earnings season. In this landscape, growth companies with high insider ownership can offer unique insights into potential long-term value creation, as insiders often have a vested interest in steering their companies through challenging market conditions.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.6% |
Here's a peek at a few of the choices from the screener.
Altri SGPS (ENXTLS:ALTR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Altri SGPS is a company that produces and sells cellulosic fibers both in Portugal and internationally, with a market cap of €873.86 million.
Operations: The company's revenue primarily comes from the production and commercialization of cellulosic fibers, amounting to €675.08 million.
Insider Ownership: 16.7%
Earnings Growth Forecast: 36.5% p.a.
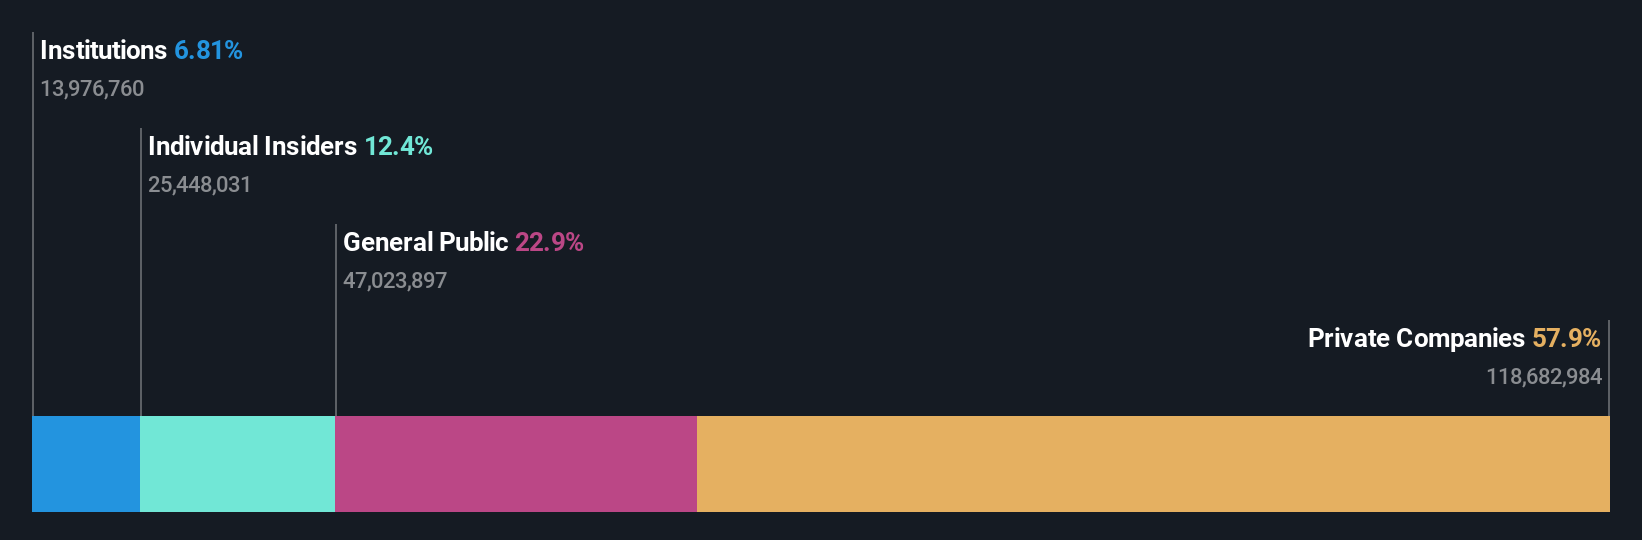
Altri SGPS shows potential for growth with earnings forecasted to increase significantly at 36.5% annually, outpacing the Portuguese market. Despite trading 56.9% below its estimated fair value, concerns include profit margins dropping from 8.1% to 1.9%, and dividends not being well covered by earnings or free cash flows. The company’s revenue is expected to grow faster than the local market but remains slower than high-growth benchmarks at 6% per year.
- Get an in-depth perspective on Altri SGPS' performance by reading our analyst estimates report here.
- Our expertly prepared valuation report Altri SGPS implies its share price may be lower than expected.
ID Logistics Group (ENXTPA:IDL)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: ID Logistics Group SA offers contract logistics services both in France and internationally, with a market capitalization of €2.41 billion.
Operations: The company's revenue segment includes Transportation - Trucking, generating €4.06 billion.
Insider Ownership: 20.9%
Earnings Growth Forecast: 20.1% p.a.
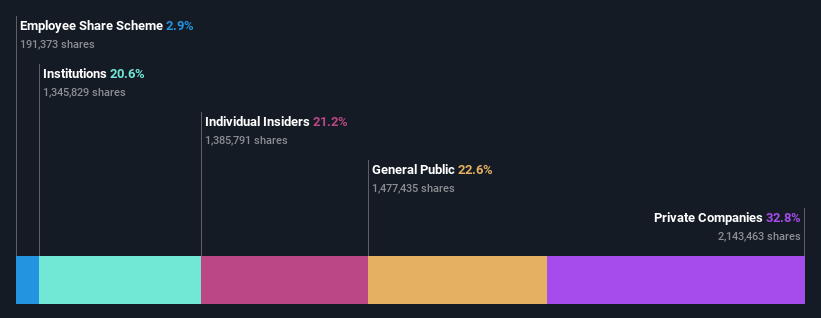
ID Logistics Group demonstrates growth potential, with earnings expected to grow significantly at 20.1% annually, outpacing the French market. Despite revenue growth of 11.1% per year being slower than high-growth benchmarks, it surpasses local market averages. Recent results show strong revenue increases, reaching €3.26 billion for the first nine months of 2026 from €2.7 billion a year ago. The stock is trading well below its estimated fair value and analysts anticipate a price rise of nearly 40%.
- Click here and access our complete growth analysis report to understand the dynamics of ID Logistics Group.
- Insights from our recent valuation report point to the potential undervaluation of ID Logistics Group shares in the market.
P/F Bakkafrost (OB:BAKKA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: P/F Bakkafrost, along with its subsidiaries, is involved in the production and sale of salmon products across North America, Western Europe, Eastern Europe, Asia, and other international markets; it has a market cap of NOK27.20 billion.
Operations: P/F Bakkafrost's revenue is primarily derived from its Farming Faroe Islands segment at DKK4.82 billion, followed by Fishmeal, Oil and Feed at DKK2.58 billion, Sales and Other at DKK11.54 million, Services at DKK991.63 million, Freshwater Faroe Islands at DKK991.77 million, Farming Scotland at DKK902.43 million, and Freshwater Scotland at DKK245.80 million.
Insider Ownership: 16.1%
Earnings Growth Forecast: 36.2% p.a.
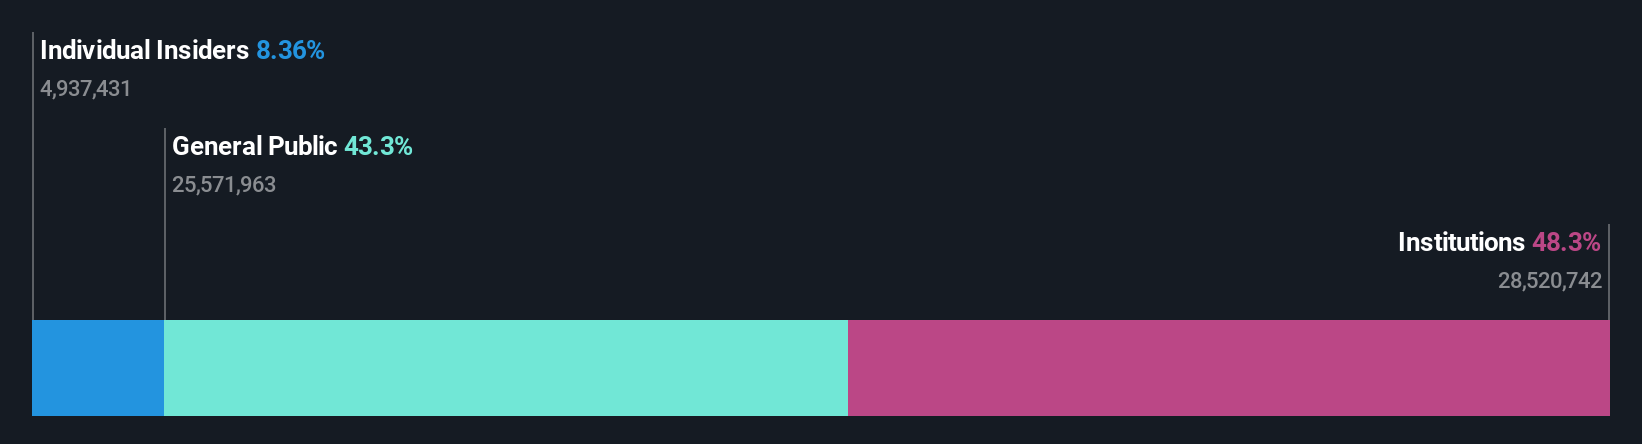
P/F Bakkafrost's earnings are forecast to grow significantly at 36.2% annually, surpassing the Norwegian market average. Revenue growth is expected at 13.2% per year, slower than high-growth benchmarks but faster than the local market. Despite a recent net loss in Q2 2026 and being dropped from the Oslo OBX Total Return Index, the company maintains its production guidance of 117,000 tonnes for 2026 and trades well below estimated fair value.
- Take a closer look at P/F Bakkafrost's potential here in our earnings growth report.
- In light of our recent valuation report, it seems possible that P/F Bakkafrost is trading behind its estimated value.
Turning Ideas Into Actions
- Investigate our full lineup of 200 Fast Growing European Companies With High Insider Ownership right here.
- Contemplating Other Strategies? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com