


What OFG Bancorp Stock's Strong Q3 Earnings Means For Shareholders
- OFG Bancorp reported Q3 2026 net income of US$56.61 million and net interest income of US$153.57 million, with lower net charge offs of US$14.46 million and ongoing share repurchases under its January 2026 buyback program.
- The combination of higher earnings per share, reduced credit losses, and continued digital banking progress points to a business leaning on efficiency rather than just headline revenue.
- We will look at how OFG Bancorp's investment narrative is affected by stronger earnings supported by disciplined expense management and credit performance.
OFG Bancorp Investment Narrative Recap
For an investor to stay with OFG Bancorp, the core belief is that a Puerto Rico focused lender can keep pairing commercial loan demand, growing digital usage and solid funding with disciplined credit. The latest quarter broadly supports that view. Earnings per share moved higher, credit costs eased and digital adoption progressed, which together help offset flat net interest income.
The near term swing factor is whether net interest margin and fee income can hold up while defending market share on deposits. The biggest risk still sits with concentration in Puerto Rico. Any economic shock, power disruption or severe storm could quickly pressure asset quality, loan growth and capital.
The most relevant piece of recent news is the Q3 2026 earnings print. OFG Bancorp reported net income of US$56.61 million, above the prior year, on net interest income of US$153.57 million that was slightly below the year ago level. Charge offs declined to US$14.46 million, which helps near term profitability and capital flexibility.
That mix matters for catalysts. Commercial lending momentum and a reported net interest margin near 5% support the loan pipeline and digital led growth story, while lower charge offs ease some of the credit concerns tied to Puerto Rico exposure and auto lending. Execution now hinges on keeping expenses tight without starving growth initiatives in digital and core banking.
What The OFG Bancorp Forecasts Are Actually Pricing In
Analysts are not just reacting to OFG Bancorp's latest quarter. Their models already bake in a specific glide path for the business over the next few years, and that path leans more on efficiency and buybacks than on rapid profit expansion. Revenue is projected to rise at 8.3% a year, while profit margins are expected to compress from 33.9% today to 24.8% by 2029. This points to a scenario where growth in the top line is offset by thinner profitability as competition for deposits and loans stays intense.
The earnings line in those forecasts is a useful reality check for investors who are focused on the recent momentum. Consensus expects OFG Bancorp to generate US$205.4 million of earnings by 2029, compared with US$220.4 million today, even as analysts also assume the share count falls by about 3.84% each year over the next 3 years. That combination implies only modest improvement in earnings per share from buybacks while total profit edges lower, which matters if you are banking on earnings compounding rapidly from here.
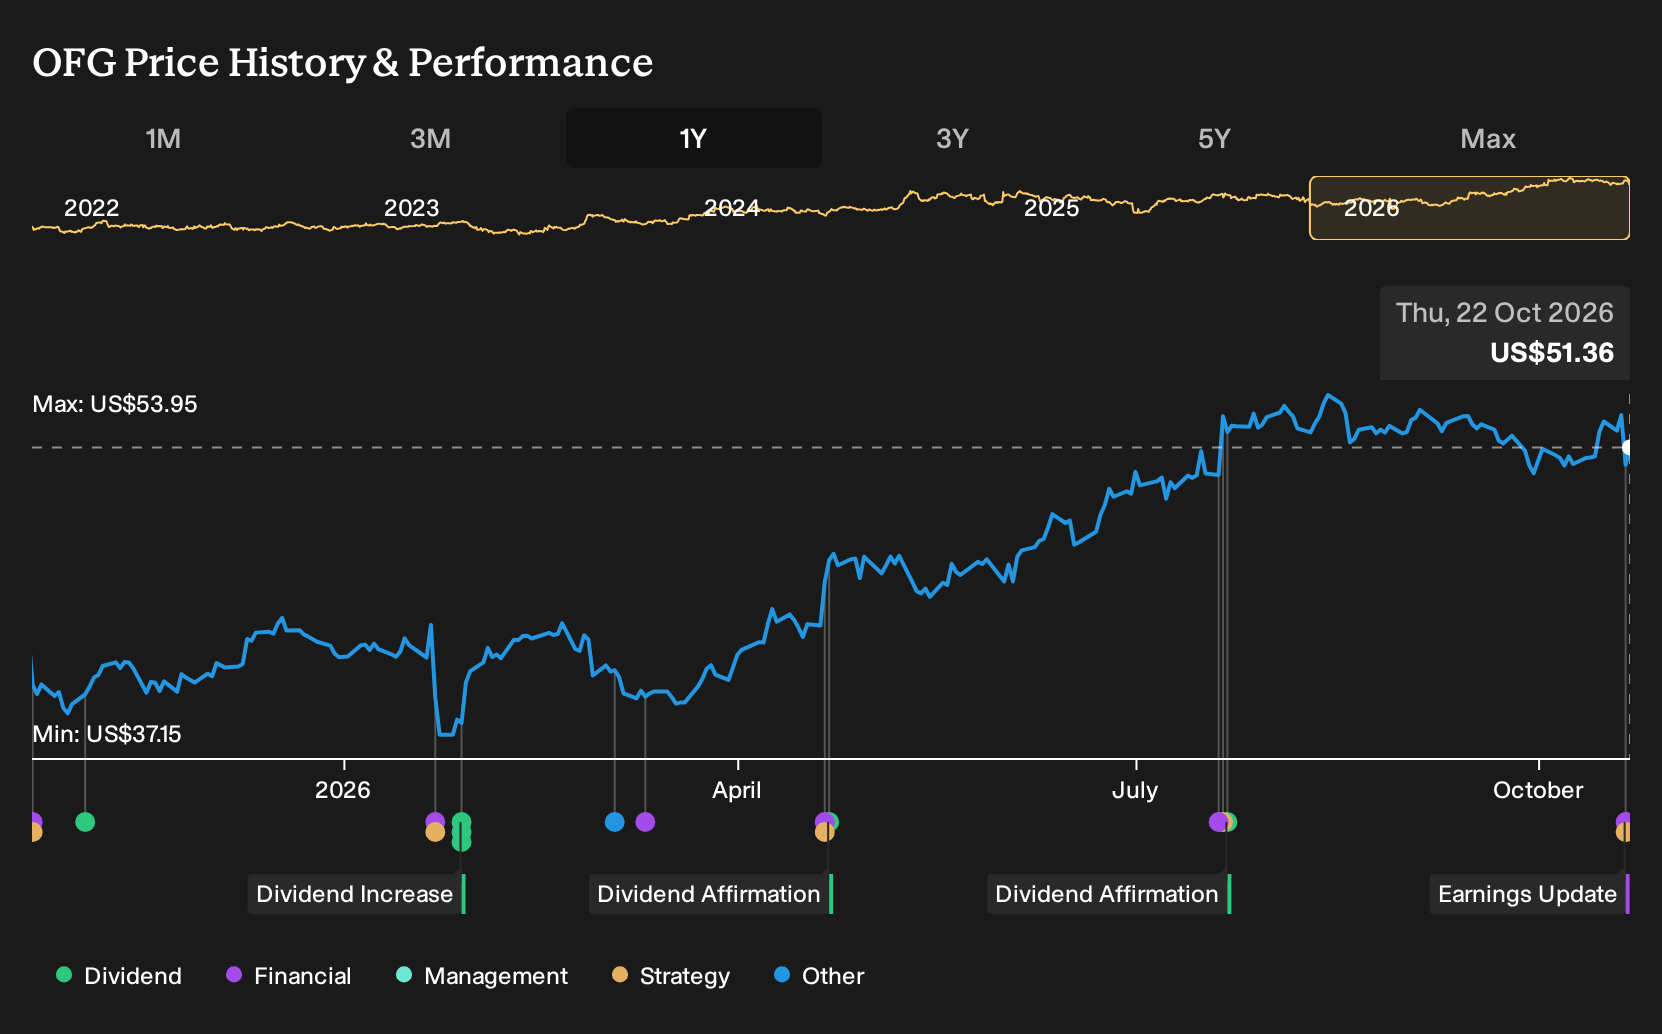
Valuation assumptions pull all of these moving parts together. To hit a price target of US$56.50 from a current share price of US$50.46, analysts are effectively asking investors to accept a future P/E of 12.7x on those 2029 earnings, compared with 9.7x today and above the current 11.4x P/E level for the wider US banks industry. The implied fair value case rests on OFG Bancorp reaching US$826.7 million of revenue and US$205.4 million of earnings by 2029 while still supporting dividends and buybacks. This would be a higher multiple on a slightly lower profit pool than today.
This set of expectations frames the trade off for anyone considering OFG Bancorp against other regional lenders. You are not looking at a consensus view that bakes in aggressive earnings expansion. Instead, the models point to steady revenue growth, some margin pressure and capital returns doing a meaningful share of the work on a per share basis. That is a very different profile from faster growing banks or the kind of early stage financial stocks often grouped with undiscovered gems that still rely heavily on reinvestment and have limited room for buybacks or dividends.
OFG Bancorp's narrative projects US$826.7 million revenue and US$205.4 million earnings by 2029. This requires 8.3% yearly revenue growth and an earnings decrease of US$15 million from US$220.4 million today.
Uncover why OFG Bancorp's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value opinions on OFG Bancorp from the Simply Wall St Community range from US$56.50 to about US$120 across 2 separate estimates, so you are seeing very different takes on what the shares are worth. Weigh those gaps against Puerto Rico concentration risk and digital driven efficiency catalysts, and then explore multiple viewpoints before forming your own stance.
Explore another OFG Bancorp fair value estimate, including one that suggests potential upside of as much as 134% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and using your own judgment.
- A great starting point for your OFG Bancorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OFG Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OFG Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond OFG Bancorp?
If you want to put OFG Bancorp in context, it helps to line it up against other listed businesses with different risk profiles and income drivers. The Simply Wall St Screener lets you scan the market quickly so you can focus on a shortlist that matches the type of balance sheet strength, income potential or growth profile you care about most.
- For investors who care most about stability and capital protection, consider starting with a 30 resilient stocks with low risk scores that may suit a more defensively minded portfolio.
- If income is a priority and you want to focus on cash returns, you could review a selection of 6 dividend fortresses that prioritise yield and payout resilience.
- When the goal is to find robust businesses with strong fundamentals beside OFG Bancorp, scan through a list of solid balance sheet and fundamentals (26 results) that can help you compare financing strength and debt profiles across the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com