


QuantumScape (QS) Stock Looks Above Fair Value After Its 86% Fall
QuantumScape has shifted its story toward AI data centers and high performance applications, yet the share price is still being judged against a business that is early in commercialisation. With the stock trading around book value territory for a pre revenue battery maker, the question is how much of the balance sheet investors are really paying for today.
- Over the past 5 years the share price has fallen 85.7%, which puts the focus squarely on whether the remaining market value lines up with what is on QuantumScape's books.
- Plans for a 100 MWh solid state production line and the QS PowerBlock launch aim to push QuantumScape toward future commercial use, which can affect how investors think about the timing and risk of turning book equity into revenue generating assets.
- There is a second opinion on QuantumScape worth weighing. See what analysts think QuantumScape's shares could be worth.
The issue now is whether QuantumScape's current market value is adequately supported by its book value once you factor in the recent shift toward AI data center focused projects and ongoing losses.
If you are considering whether QuantumScape's book value still justifies the current price, it can help to compare that question across 30 high quality undervalued stocks.
Is QuantumScape Getting Expensive on Book Value?
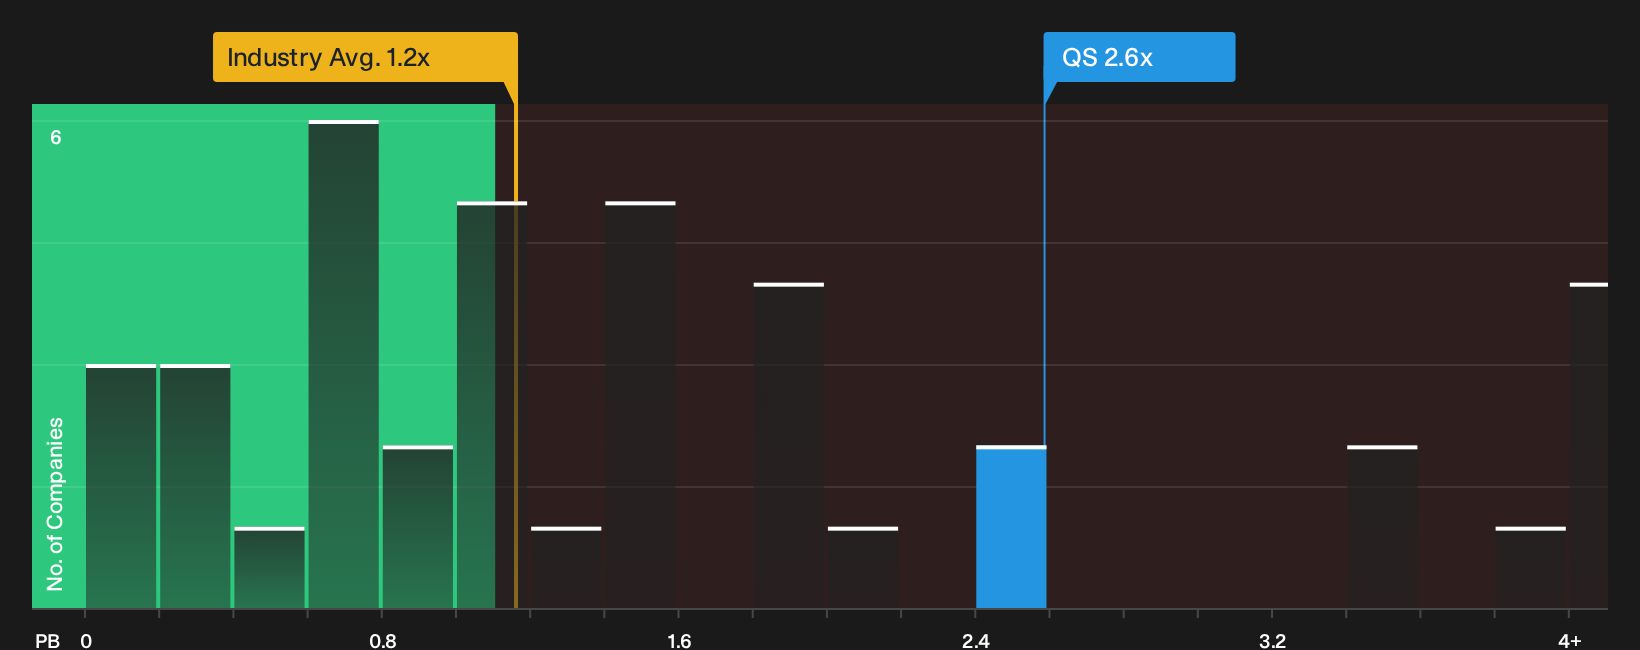
P/B works better than earnings based ratios for QuantumScape because the business still reports losses and has no revenue yet, so investors mostly weigh the balance sheet against the share price. On this lens, the stock trades at a P/B of 2.6x, compared with an Auto Components industry average of 1.2x and a peer group around 1.6x. That puts QuantumScape at a clear premium, which points to an overvalued reading on this single metric.
Because the 100 MWh AI data center production plan and QS PowerBlock launch have raised expectations around future use cases, the market appears willing to pay well above the sector book multiple despite zero revenue and recent losses. For you as a shareholder or potential buyer, the key question is whether the solid state roadmap and AI focused projects justify paying more than the value of the current equity on the balance sheet compared to peers at lower P/B levels. Explore the numbers behind QuantumScape's P/B valuation.
The QuantumScape Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where QuantumScape's book value puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to occur for the shares to be worth materially more or less than today's price, based on the scenarios discussed on the Community page. Each Narrative connects a specific fair value estimate to a clear story about QuantumScape's possible catalysts and risks so you can track which version of events is unfolding over time.
Community views on QuantumScape split between a royalty heavy success story and a long haul grind through losses and execution risk.
Bull case: 92% undervalued
"At the heart of QuantumScape''s innovation is its proprietary ceramic separator, a unique component that enables an anode-free lithium metal battery architecture…"
Discover why this Narrative puts QuantumScape at 92% undervalued.
Bear case: 66% overvalued
"Reliance on the Cobra process and Eagle Line blueprint to reach gigawatt hour production could expose execution bottlenecks, so any difficulty turning pilot success into high volume, high yield manufacturing would risk delaying customer programs and pushing out meaningful revenue and royalty streams…"
Explore why this Narrative puts QuantumScape at 66% overvalued.
One last check for QuantumScape before you move on
Balance sheet ratios and scenario stories only go so far. The next angle is how professionals currently model QuantumScape a few years from now, and how that compares with today’s pricing. Explore where analysts expect QuantumScape to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com