


Top 3 Growth Stocks To Watch In October 2026
Oil above US$112 and renewed conflict risk have pushed energy costs back into the spotlight, reminding investors how fast conditions can change. When markets swing on headlines, companies that analysts expect to grow earnings strongly while keeping their balance sheets in decent shape can look especially interesting. This article breaks down three stocks from a high quality, future focused growth list that fit that profile.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses with earnings that analysts expect to expand while balance sheets stay in acceptable shape. However, if you want the absolute best, these 486 best high growth potential stocks are the cream of the crop.
NVIDIA (NVDA)
NVIDIA is firmly linked to the Healthy high growth potential theme through its data center AI compute platform, while still running sizeable gaming and graphics operations. Compute & Networking generates about US$275.4b of revenue versus roughly US$27.6b from Graphics, and the company’s market cap is around US$5.36t.
NVIDIA’s AI-focused hardware and software give it outsized influence on how fast complex models can be trained and deployed, which is exactly the kind of earnings engine this screener targets.
"Successful competition from AMD, Intel, or a Chinese firm could undermine this."
What really matters now is how one less visible pressure shapes the balance between demand, pricing power and future profitability.
That pressure is exactly what the full narrative for NVIDIA unpacks, showing how NVIDIA’s AI engine could keep accelerating even if fresh rivals squeeze pricing power.

Kingboard Laminates Holdings (SEHK:1888)
Kingboard Laminates Holdings is a Hong Kong based producer of glass epoxy and paper laminates plus upstream materials like copper foils and specialty resins for printed circuit boards, with laminates contributing about HK$25.5b of its HK$25.7b segment revenue, and the group valued around HK$116.0b.
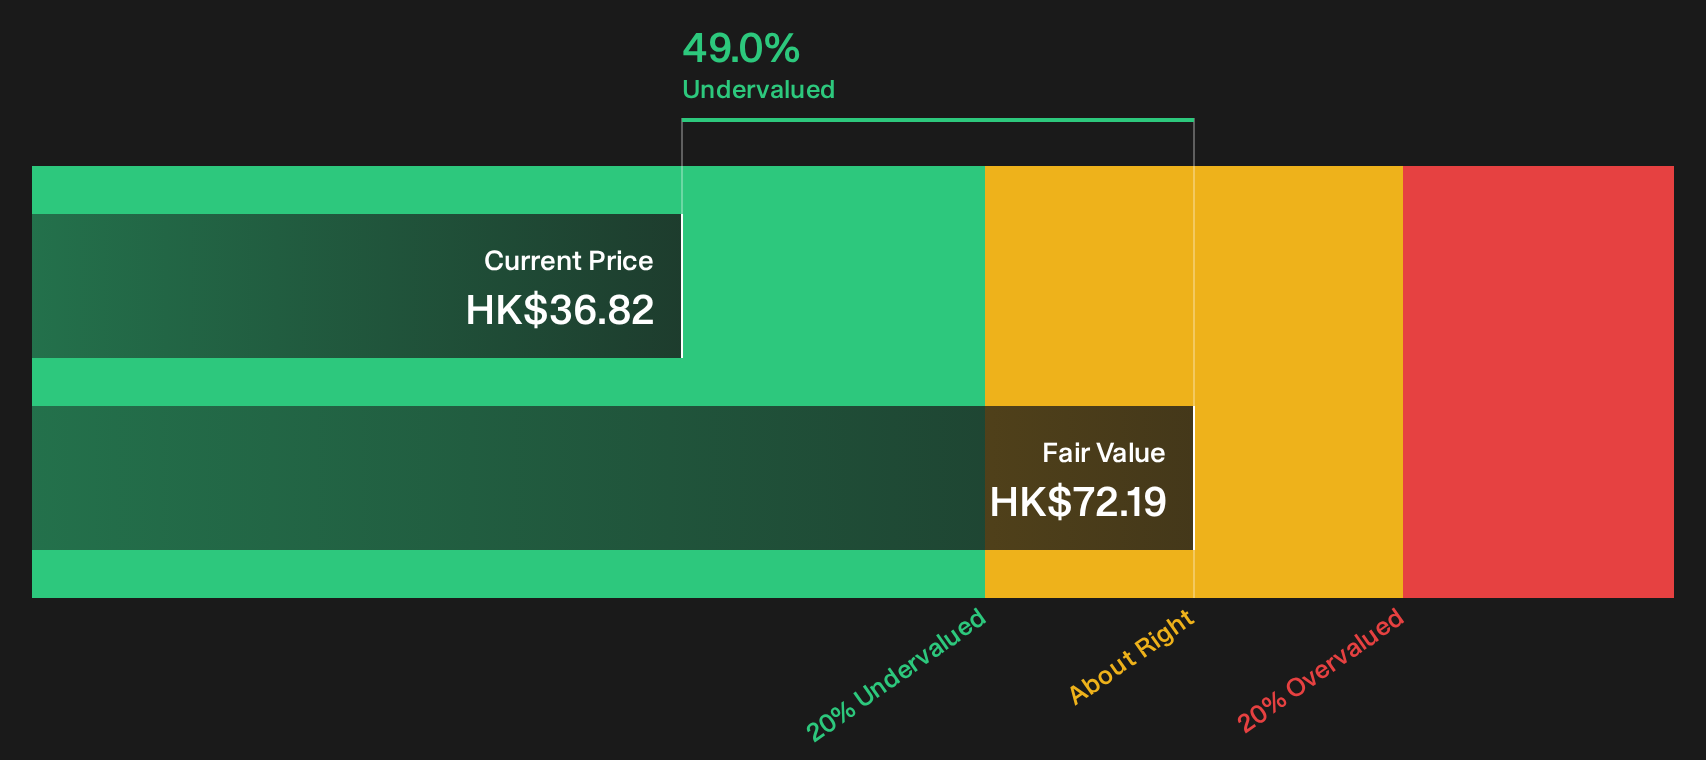
Kingboard Laminates is categorized in the Healthy high growth potential theme because analysts expect earnings to rise about 35% a year over the next three years from its PCB materials operations. The stock trades well below some fair value estimates, which means much depends on how a tight supply backdrop may influence future pricing power.
That supply squeeze angle is exactly what the DCF valuation analysis for Kingboard Laminates Holdings digs into, showing where Kingboard Laminates could rerate if pricing power really bites.
Oracle (ORCL)
Oracle is best known for databases, but the piece that really links it to the Healthy high growth potential theme is its cloud applications and Oracle Cloud Infrastructure. These now anchor a software and services business that brings in about US$62.8b of the US$69.8b total, with a market value near US$391.5b.
Oracle’s cloud pivot matters for this theme because it turns long-running enterprise relationships into high margin, recurring contracts that analysts expect to keep driving earnings. The real proof point sits in how its AI infrastructure is being used by headline grabbing customers.
"The foundation of Oracle’s AI narrative rests on its Gen2 AI infrastructure and the validation it received from the premier generative AI powerhouse, OpenAI."
What happens to Oracle’s growth story depends heavily on how one unresolved funding and cash flow pressure interacts with that surging cloud demand.
That funding pressure is exactly where the full narrative for Oracle connects the dots, showing how Oracle could turn Gen2 AI demand into accelerating cash generation while still keeping key risks in view.

Seeking Alternatives Before Momentum Flies?
Fresh opportunities move fast, and the best breakouts rarely wait around. Scan curated ideas before the crowd, while the data still matters and prices have not fully caught up, then act now.
- Spot cash rich businesses before the headlines catch on by running the list of solid balance sheet and fundamentals (26 results) and focus on companies with financial room to handle shocks.
- Ride early momentum in smaller AI players by scanning the 38 AI small caps that already pair commercial traction with disciplined capital use instead of endless cash burn.
- Target income streams by reviewing the 6 dividend fortresses that filter for yield and balance sheet strength, so payouts have support to stay on track.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com