


Enterprise Financial Services (EFSC) Q3 Earnings Face Persistent Credit Pressure
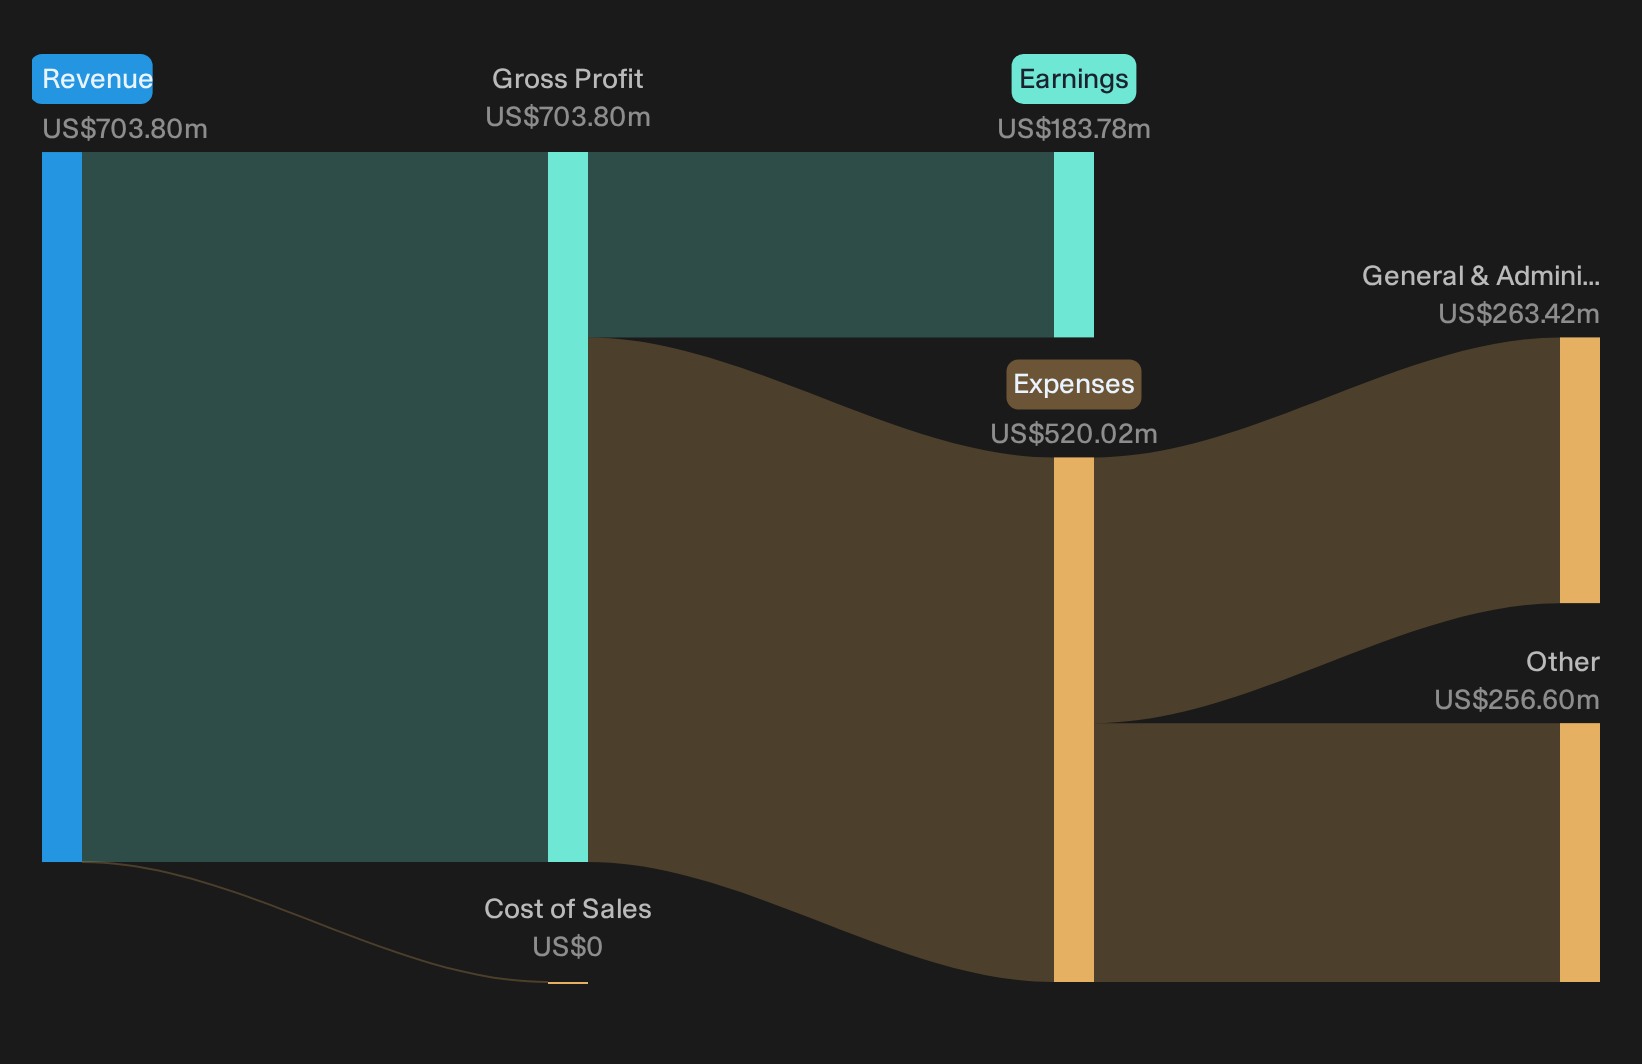
Enterprise Financial Services came into this Q3 2026 report with a stock that had drifted over the past quarter and a modest 1.3% pop today to about $61. The move looked calm. The earnings story was not. The bank posted basic earnings per share of about $1.15 on revenue of roughly $174.7m, while elevated credit costs again pulled at results and kept risk firmly in focus.
For a lender long viewed as a steady regional compounder, that gap between the share price reaction and the pressure from credit charges is the real headline for investors to watch.
Like the underlying Enterprise Financial Services story but uneasy about recurring credit costs tugging at earnings quality? Consider filtering for banks and lenders that pair measured growth with sturdier balance sheets using the list of solid balance sheet and fundamentals stocks (26 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$174.7m vs. US$166.7m (up about 4.8%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$41.5m vs. US$44.3m (down about 6.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.15 vs. US$1.20 (declined about 3.8%)
- Non Performing Loans, or NPLs (Q3 2026 vs. Q3 2025): US$76.1m vs. US$127.9m (fell about 40.5%)
Earnings tell you what Enterprise Financial Services reported this quarter, but cash flows tell you what the business is really throwing off over time and how resilient those payouts might be. Look at Enterprise Financial Services' cash flows alone and the stock could be a dramatic 41% undervalued.
EFSC bull case: deposits and margin under the microscope
The upbeat story says Enterprise Financial Services can lean on funding and prior tech spend to keep net interest economics strong.
"Margins and earnings are still positioned for expansion as Enterprise Financial Services continues to lean on prior digital banking and operational efficiency investments that support customer acquisition and lower cost to serve, which can help sustain a net interest margin that was 4.30% in Q2 2026 and support earnings."
Q3 results largely back that up. Net interest margin held at 4.30% and net interest income added about US$6m even with higher funding costs. Core deposits rose US$624m and noninterest-bearing deposits stayed around one third of the base, which supports the idea of a durable low cost funding mix. The offset is earnings per share slipping year on year as elevated provision expense soaks up that pre provision strength.
EFSC bear case: credit normalization still not delivered
The bear argument focuses on whether credit issues will continue to eat into that earnings power.
"Elevated nonperforming assets of about US$160 million and the recent miss against the Q2 2026 earnings consensus, driven by higher than expected credit provision, show that credit normalization is not yet complete."
Q3 numbers keep that concern alive. Provision for credit losses was US$18.1m, with net charge offs of US$11m, or 36 bps annualized, still well above the 15 bps long run ambition. Nonperforming assets stayed high at about US$183m, mostly real estate secured, and criticized loans sat around 6.3% versus management’s 4.5% to 5% target. Management reiterated confidence in collateral and reserves, yet the timing of Southern California OREO resolution is still uncertain, so credit costs remain a clear swing factor for future quarters.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Quiet Disconnects
Enterprise Financial Services just showed how a calm share move can come with a tougher earnings story. The real opportunity is finding companies that could be undervalued before fresh information forces investors to reprice them.
- Company 1 - 28% below our estimate - helps utilities upgrade grid hardware and diagnostics as electrification and infrastructure replacement reshape power networks and test systems.
- Company 2 - 31% below our estimate - supplies custom chips and connectivity hardware whenever data traffic surges through expanding AI, cloud and enterprise infrastructure projects.
- Company 3 - 27% below our estimate - equips dense AI data centres with liquid cooling and power systems as air cooling and legacy water hungry designs reach physical limits.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com