


CEO Shake Up Might Change The Case For Investing In Lindt Stock (SWX:LISN)
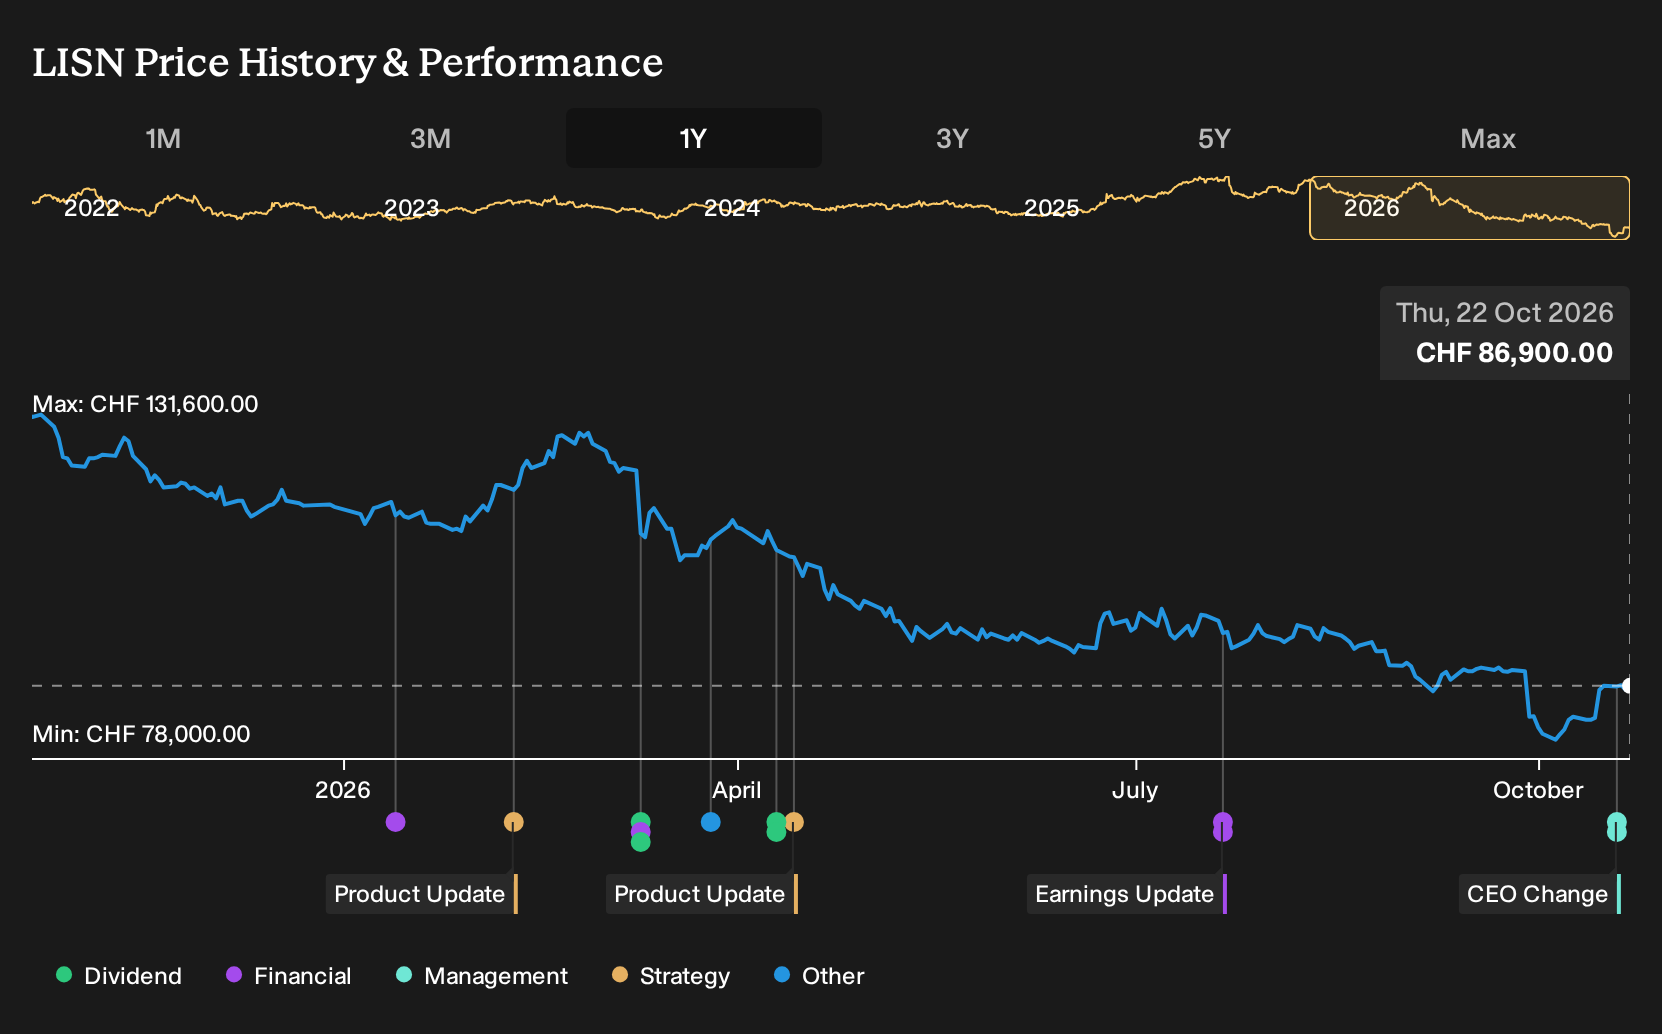
- Chocoladefabriken Lindt & Sprüngli has announced a leadership overhaul, with Group CEO Adalbert Lechner departing, Vice-Chairman and former Group CEO Dieter Weisskopf stepping in as interim CEO from 19 October 2026, and new CEOs appointed for Germany and Austria effective 26 October 2026.
- The reshuffle concentrates decision-making in experienced hands at the Group and Central European level, which matters for how Lindt & Sprüngli manages premium positioning, cost pressures and growth execution across key markets.
- We will examine how Chocoladefabriken Lindt & Sprüngli's investment narrative is affected by the interim CEO appointment and Central European leadership reshuffle.
Scan how Chocoladefabriken Lindt & Sprüngli’s leadership shake-up compares with other consumer-focused businesses undergoing change by reviewing the hand-picked 224 resilient stocks with low risk scores in the market.
Chocoladefabriken Lindt & Sprüngli Investment Narrative Recap
To own Chocoladefabriken Lindt & Sprüngli, you really need to believe that premium chocolate, gifting and direct retail can keep pulling in consumers even as cocoa stays expensive and shoppers trade down in parts of the category. The immediate operational swing factor is whether demand holds up as pricing and mix stay skewed to the higher end.
The board explicitly linked the CEO change to its ambition to regain consistent, strong growth, which puts near term execution under a brighter spotlight but does not by itself alter the economic drivers. The sharper risk is still margin pressure from high input costs and any slowdown in like for like retail store performance.
The most relevant move for that story is Dieter Weisskopf stepping in as interim CEO while a successor is sought for the second quarter of 2027. Investors now watch whether Chocoladefabriken Lindt & Sprüngli can keep growing earnings, which analysts expect at 4.85% per year, without relying purely on price increases in a soft volume backdrop.
Leadership continuity at the top, combined with the shift in Germany and Austria to Ali Kulein and Fabian Reinhardt, directly touches two levers behind the current thesis. Premiumization, more direct to consumer stores and geographic diversification only pay off if regional heads keep stores productive, protect pricing power and avoid overextending fixed costs while cocoa prices remain elevated.
Chocoladefabriken Lindt & Sprüngli's current analyst story points to revenues of CHF 6.7b and earnings of CHF 838.9m by 2029, based on a projected 4.1% yearly revenue growth rate and an earnings increase of about CHF 108.4m from CHF 730.5m today.
Uncover how Chocoladefabriken Lindt & Sprüngli's fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment follows the leadership reset.
Exploring Other Perspectives
Some of the lowest analysts on Chocoladefabriken Lindt & Sprüngli focus on the risk that cocoa cost relief arrives later than hoped. They were already working with slower revenue growth of about 2.7% a year and earnings of roughly CHF 746.9m by 2029. Leadership changes like this could nudge those already cautious forecasts even lower, or prompt a rethink in both directions. Use this spread in opinions as a cue to compare several viewpoints before you decide what feels reasonable.
Explore 5 other Chocoladefabriken Lindt & Sprüngli fair value estimates, including one that suggests as much as 36% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Chocoladefabriken Lindt & Sprüngli research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Chocoladefabriken Lindt & Sprüngli. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chocoladefabriken Lindt & Sprüngli's overall financial health at a glance.
Looking for more investment ideas beyond Chocoladefabriken Lindt & Sprüngli?
If this leadership story has you reassessing Chocoladefabriken Lindt & Sprüngli, it can help to line it up against other opportunities with different risk and return profiles using the Simply Wall St Screener.
- For investors who care most about resilience, check out a curated 224 resilient stocks with low risk scores that may hold up better if conditions turn tougher.
- If value is your north star, scan a focused 191 high quality undervalued stocks that highlights companies where quality and pricing appear out of sync.
- For those who want stability from the balance sheet first, start with a list of solid balance sheet and fundamentals (204 results) and then filter down to businesses that fit your own style.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com