


Is KB Home (KBH) Fairly Valued Following Weaker Orders And Rising Debt Risk?
KB Home (KBH) is in the spotlight after management flagged weakening fundamentals, with declining backlog and orders pointing to softer future revenue, while higher debt levels raise financial risk despite recent new community openings.
KB Home’s recent fundamentals are reflected in the chart, with a 1-day share price return of 7.39% and a 7-day share price return of 5.82%, following a 90-day share price decline of 18.62% and a year-to-date share price drop of 19.06%.
Scan how KB Home’s pressures compare with other builders facing similar demand and balance sheet questions by sizing up our hand-picked list of solid balance sheet and fundamentals (26 results) in the same sector.
KB Home is still building new communities and paying dividends even as its share price has slid and orders have softened. The business story and the recent stock drop now pull in opposite directions. Which side does the valuation favor?
Most Popular Narrative: 10% Undervalued
KB Home’s most followed narrative points to a fair value of $51.57, above the last close at $46.19. This puts the recent selloff and rebound in a different light and raises the question of whether the market is underestimating what faster build cycles and land control might mean for future earnings power.
KB Home is focusing on maintaining attractive pricing by offering compelling value relative to local market conditions, and is now leaning more on higher margin Built to Order product that carries a margin premium compared with inventory homes as that mix trends toward roughly three quarters of deliveries. This mix shift can support housing gross margin and earnings.
See why 15 investors see KB Home as 10% undervalued.
Result: Fair Value of $51.57 (UNDERVALUED)
Still, KB Home’s story can break if weak demand lingers and resale competition forces deeper price cuts that squeeze housing margins and future earnings power.
Find out about the key risks to this KB Home narrative.
Another View: KB Home Through A Cash Flow Lens
The first narrative presents KB Home as about 10% undervalued at $51.57, but the SWS DCF model tells a very different story. Based on that calculation, the estimated future cash flow value is $33.26 while the shares last closed at $46.19, which appears overvalued rather than cheap. Which story do you trust more: the cash flow model or the earnings-driven fair value?
To see how the cash flow work compares with your own expectations for KB Home, Look into how the SWS DCF model arrives at its fair value.
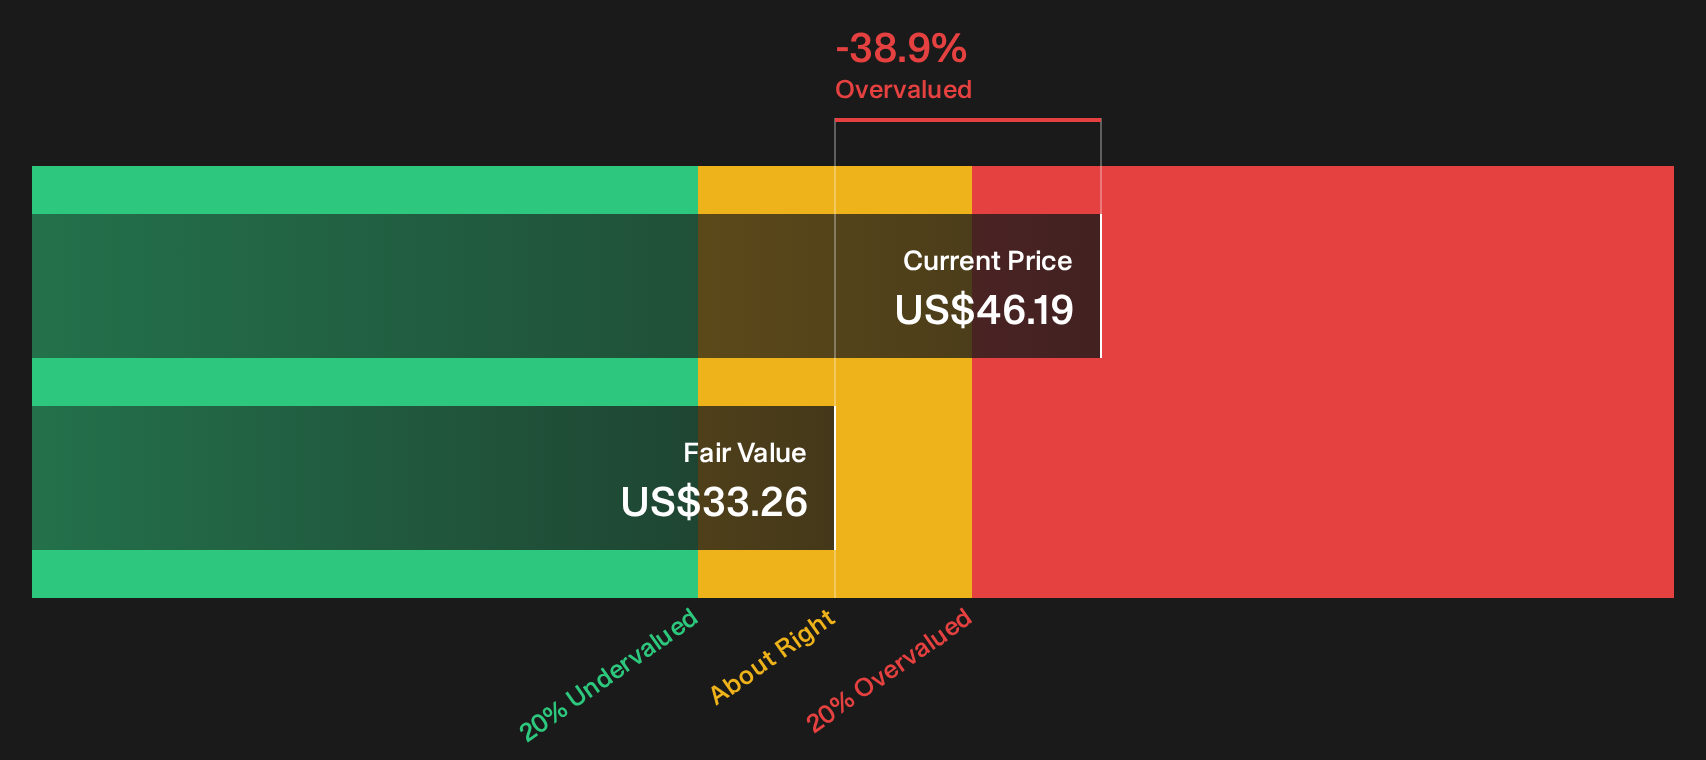
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KB Home for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on KB Home’s outlook can feel messy, so move fast, test the numbers against your own expectations, and weigh both the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond KB Home?
KB Home might be on your radar today, but widening your watchlist can help you spot opportunities that better match your risk, income, and valuation preferences.
- Target resilient balance sheets by scanning companies that feature in our list of solid balance sheet and fundamentals (26 results) and compare how their financial footing stacks up against more stretched peers.
- Hunt for mispriced quality by working through a curated 31 high quality undervalued stocks that filters for strong fundamentals paired with prices that may not fully reflect them.
- Boost your income focus by reviewing a hand picked 6 dividend fortresses that highlights higher yield payouts supported by underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com