


Saudi Aramco Stock And 2 Oil Plays Exposed To Higher Crude Prices
Oil infrastructure in Saudi Arabia and nearby producers is back in the headlines, with Houthi attacks, U.S. evacuation orders and reports of explosions in southern Iran keeping a firm risk premium in Brent and WTI. Higher crude supports some businesses and hurts others, and that split matters for your portfolio. This article walks through 3 stocks exposed to this news and explains how the current backdrop might help or harm them.
The three stocks below are a sample of what this risk backdrop means for large integrated producers, and the full screen surfaced 22 more companies with equally detailed stories that are not covered here. If you want to identify and analyze which of these large oil and gas groups best fits your own risk tolerance and time horizon, head straight into the Global Integrated Oil & Gas Producers screener.
Delek US Holdings (DK)
Delek US Holdings plugs into the Global Integrated Oil & Gas Producers theme as a downstream focused refiner and logistics operator whose earnings move with crude cycles and fuel spreads, making it a direct way to play refining margins rather than pure oil production.
Delek US Holdings runs refineries in Texas, Arkansas and Louisiana and a linked logistics network, with about US$11.9b of revenue from refining and US$1.2b from logistics, and a market value near US$4.8b, which anchors it in the larger end of this screener universe.
"Ongoing operational optimization and infrastructure investments are expected to boost margins, lower costs, and create new earnings streams."
The real swing factor is how one evolving pressure on future profitability ultimately reshapes the refining economics that investors are counting on.
That pressure point is exactly what the full narrative for Delek US Holdings unpacks, revealing where Delek US Holdings could see earnings power accelerate or quietly stall.

Saudi Arabian Oil (SASE:2222)
Saudi Arabian Oil sits at the center of the Global Integrated Oil & Gas Producers theme, with a large footprint in crude extraction, pipelines, refining and chemicals that directly ties results to swings in global oil prices and supply risk premia.
Saudi Arabian Oil runs a vast integrated energy and chemicals platform, with roughly SAR1.09t of revenue from Upstream and SAR1.11t from Downstream operations, offset by eliminations and corporate items, and a market value around SAR6.12t that places it in mega-cap territory.
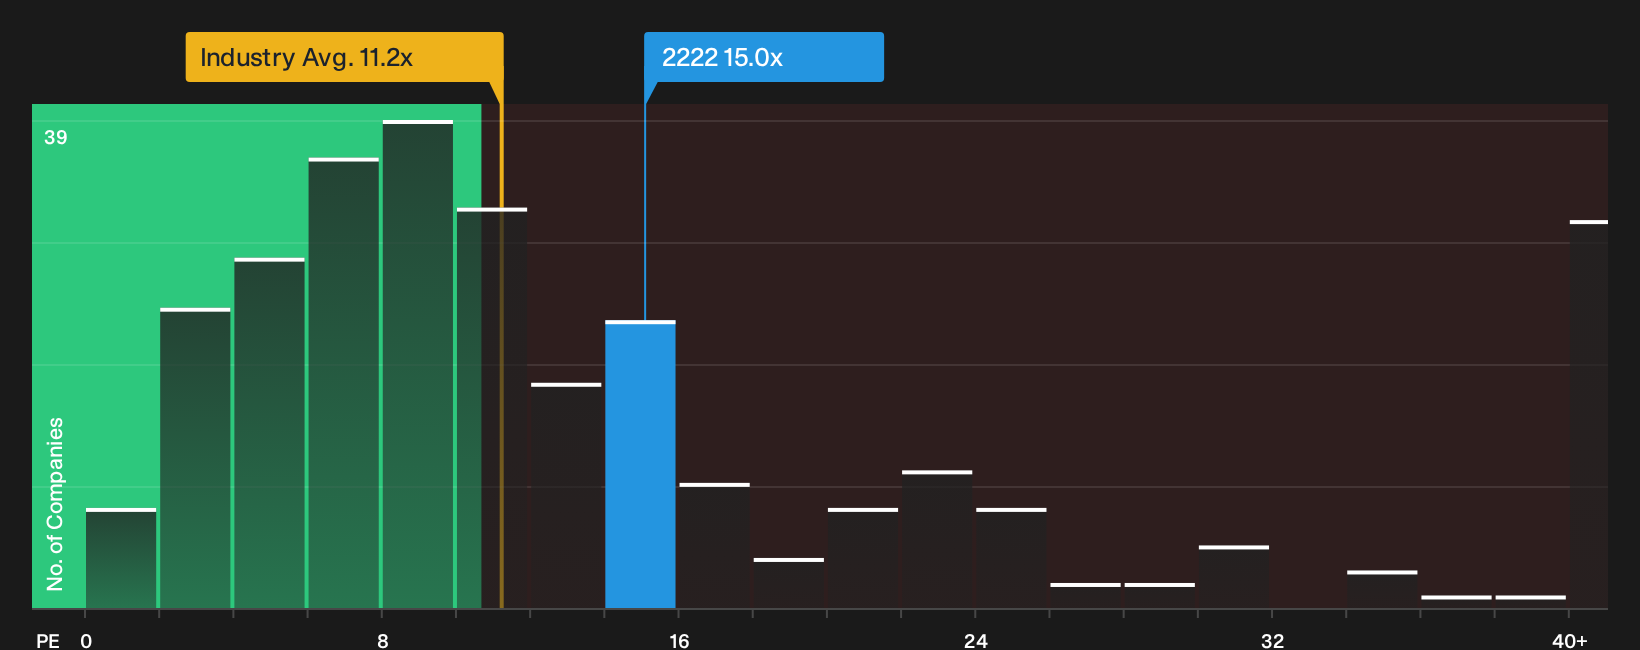
In a market that often values crude producers on simple commodity cycles, Saudi Arabian Oil is being treated as something quite different.
"The absence of the RSI indicator does not prevent the conclusion that the stock is priced as a "Tech and Growth" entity rather than a basic commodities company."
The key question is how one persistent pressure on future cash generation interacts with that premium narrative if pricing conditions change.
If that premium ever cracks, you will want the full context in the full narrative for Saudi Arabian Oil, which maps how Saudi Arabian Oil could still compound its edge.
Antero Resources (AR)
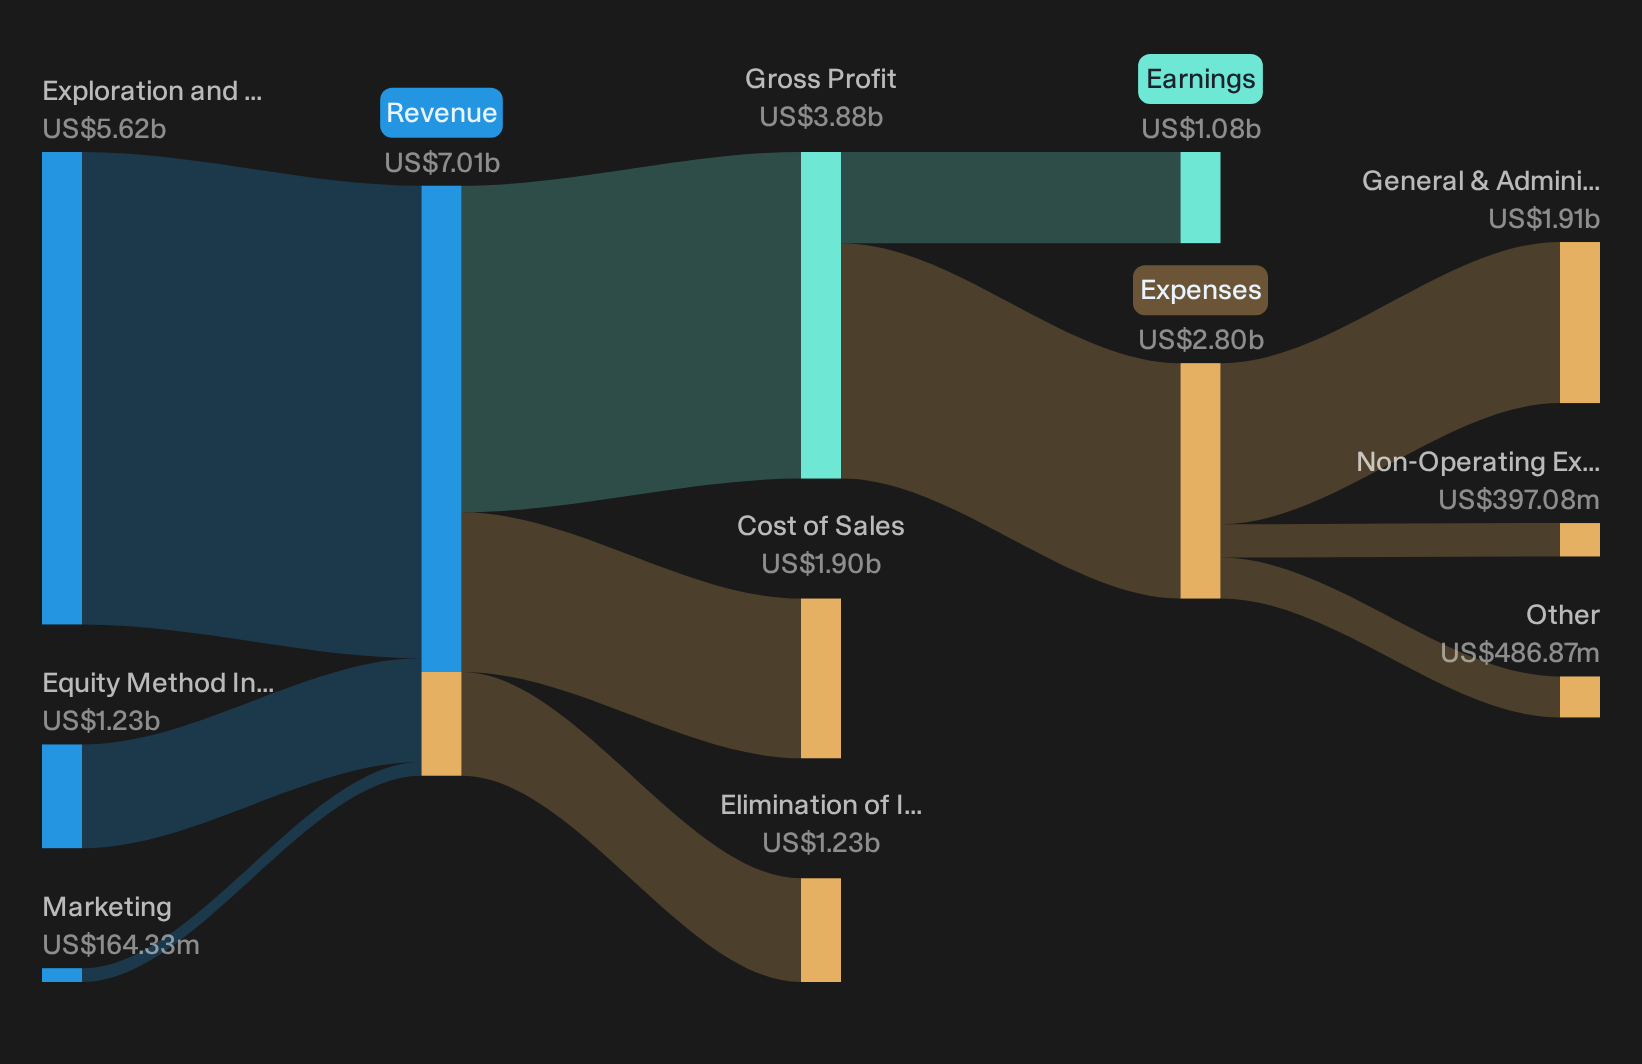
Antero Resources plugs into the Global Integrated Oil & Gas Producers theme through its upstream focus on U.S. gas and liquids, backed by 537,000 net acres in the Appalachian Basin and linked midstream interests. It generated about US$5.6b from exploration and production and has a market value near US$11.8b.
For investors looking at U.S. producers tied into global pricing, Antero Resources offers a way to gain exposure to export linked gas and liquids within this integrated energy screen without leaving North America.
"Accelerating US LNG export demand, combined with growing exports to Mexico, is expected to increase the share of Antero Resources gas volumes linked to export pricing, which could support revenue and cash flow as additional capacity ramps."
What matters now is how one quiet shift in Antero Resources cost base shapes the gap between headline prices and the cash that actually sticks.
To see how that cost shift could amplify or mute those export linked gains, read the full narrative for Antero Resources to understand what might be getting overlooked now.
Seeking Alternatives Before The Crowd?
Fresh ideas often move first and prices may move next. Screens can fill up quickly once momentum is obvious and any potential edge can diminish. Consider scanning new angles now to explore opportunities earlier in the process.
- Target resilient compounders that aim to hold up when volatility bites by running the 30 resilient stocks with low risk scores before they stop flying under the radar.
- Hunt for income workhorses with yields that could matter if prices swing, and filter for potential 6 dividend fortresses while it still feels under the radar.
- Explore future-facing infrastructure that is linked to power demand and grid upgrades, using the curated 42 power grid technology and infrastructure stocks while the best candidates may still be quietly priced.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com