


Domino's Pizza (DPZ), What Is Behind The Fresh Attention?
Domino's Pizza (DPZ) drew fresh attention after its latest quarterly update, which paired higher third quarter earnings with a new dividend declaration and ongoing share repurchases that together reshaped the shareholder return story.
Domino's Pizza shares now trade at US$311.15, and the 7-day share price return of 5.16% and 30-day gain of 5.14% suggest short-term momentum building, even as the year-to-date share price return has fallen 26.84% and the 5-year total shareholder return is down 30.23%.
Review Domino's Pizza alongside other consumer-focused stocks that exhibit resilient earnings and shareholder returns by focusing on our curated list of 33 high quality undervalued stocks.
After a sharp rebound to US$311.15, Domino's Pizza now trades between an implied intrinsic premium and a double digit discount to analyst targets. So where does fair value actually land in that spread?
Most Popular Narrative: 24% Undervalued
Against the last close at $311.15, the most followed valuation narrative for Domino's Pizza points to a fair value of $408.07, which frames the current rebound as still short of what some see as intrinsic worth.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around ~20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake "pizza slice" in the company.
See why 13 investors see Domino's Pizza as 24% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, Domino's Pizza relies heavily on franchised operators and a concentrated US supply chain. As a result, weaker franchise economics or distribution issues could quickly challenge that undervalued thesis.
Find out about the key risks to this Domino's Pizza narrative.
Another View On Domino's Pizza Valuation
The community narrative leans on a blended approach that points to Domino's Pizza trading around 24% below an estimated fair value of $408.07. The in house SWS DCF model, which focuses purely on projected future cash flows, actually puts fair value lower at $285.57, implying the stock is overpriced on that lens. Which lens you lean on depends on how much weight you give to historical multiples and user assumptions versus a more mechanical cash flow forecast.
Look into how the SWS DCF model arrives at its fair value.
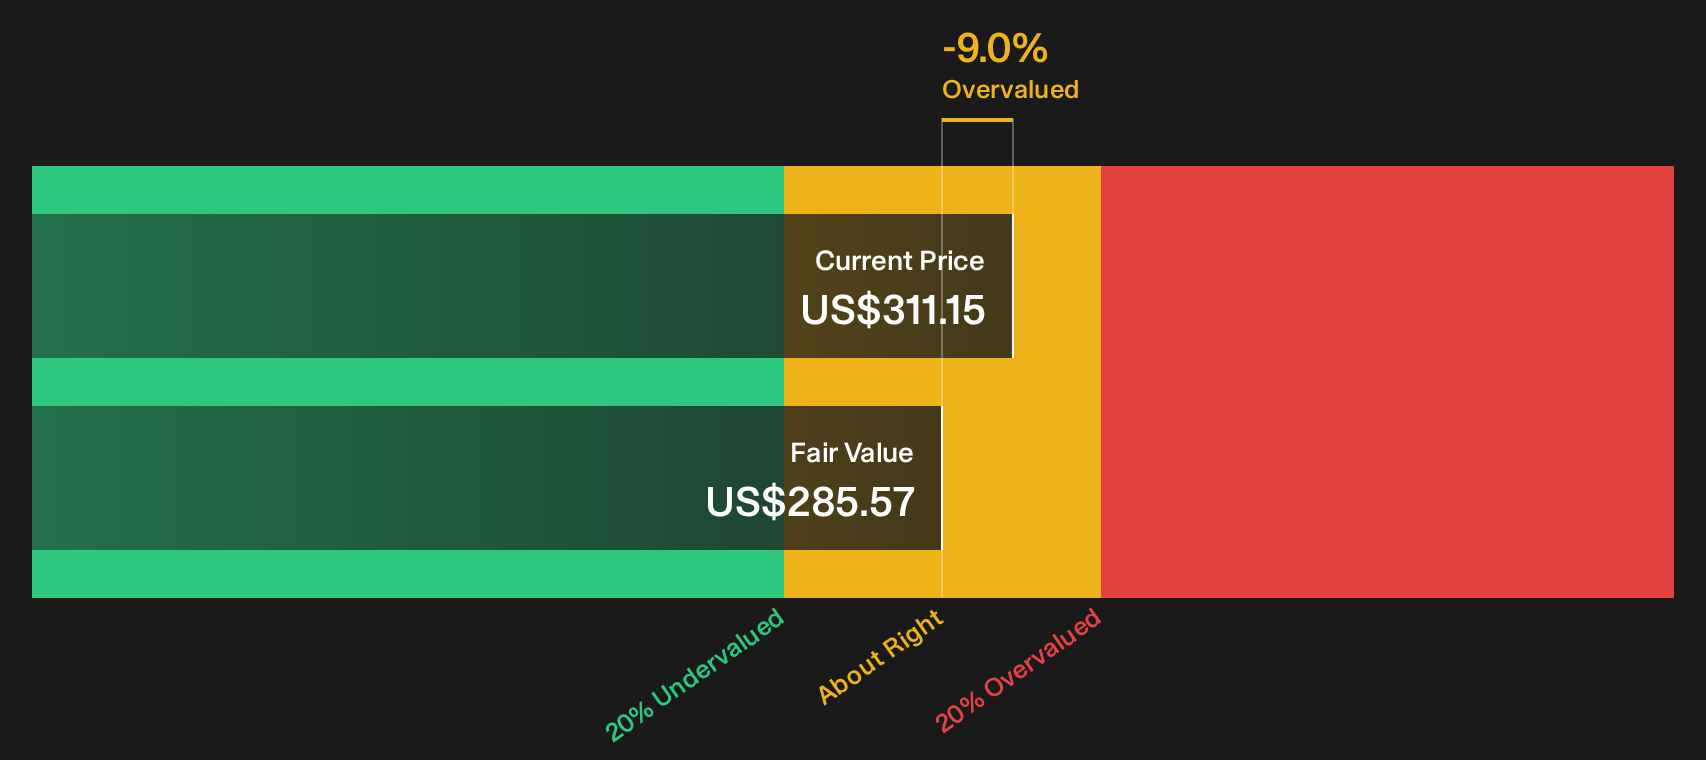
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Domino's Pizza feels familiar, use it as a prompt to move quickly and review the underlying data yourself. To see both sides laid out clearly, review the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
Do not stop at Domino's Pizza. Use this momentum to widen your watchlist with focused ideas that match your risk tolerance and income goals.
- Target steadier returns by concentrating on resilient companies in our 31 resilient stocks with low risk scores.
- Boost potential income streams by focusing on businesses in the 7 dividend fortresses.
- Hunt for overlooked opportunities by zeroing in on financially strong prospects in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com