


Alkermes (ALKS) Sleep Research Push Keeps Undervalued Narrative In Focus
Alkermes (ALKS) is in focus after its presentations at Sleep Europe 2026 in Maastricht, where company clinicians and external sleep specialists highlighted clinical work around narcolepsy and broader sleep medicine research.
Recent trading has been choppy for Alkermes, with the share price slipping 1.4% on the day and down about 18% over 90 days, even after a strong year to date share price return of 53.9% and a 1 year total shareholder return of 39.9% that reflects growing interest in its neuroscience and sleep disorder pipeline ahead of earnings in early November.
Scan other neuroscience and sleep disorder players showing similar momentum and pipeline depth through our curated 37 healthcare AI stocks for added context around Alkermes.
After a sharp run over 12 months but a choppy past quarter, Alkermes now sits at a curious intersection of recent gains and renewed uncertainty. Does the current valuation still lean in favor of new buyers or recent holders?
Most Popular Narrative: 23% Undervalued
On the latest numbers, Alkermes closed at $43.48, while the most followed narrative framework pegs fair value at about $56.56 using an 8.47% discount rate. That gap reflects a view that the current share price does not fully capture the earnings and cash flow potential tied to its psychiatry and sleep disorder portfolio.
Robust, above-expectation demand growth for Alkermes' proprietary neuroscience products VIVITROL, ARISTADA and LYBALVI, now reflected in Q2 2026 proprietary net sales of US$411.7 million and maintained full year guidance, continues to support the view that higher volumes can still feed into future revenue and operating leverage.
See why 9 investors see Alkermes as 23% undervalued.
Result: Fair Value of $56.56 (UNDERVALUED)
Still, the Alkermes story can change quickly if orexin trials disappoint or if higher R&D and deal related costs keep net losses wider for longer.
Find out about the key risks to this Alkermes narrative.
Another View: Alkermes Looks Expensive On Earnings
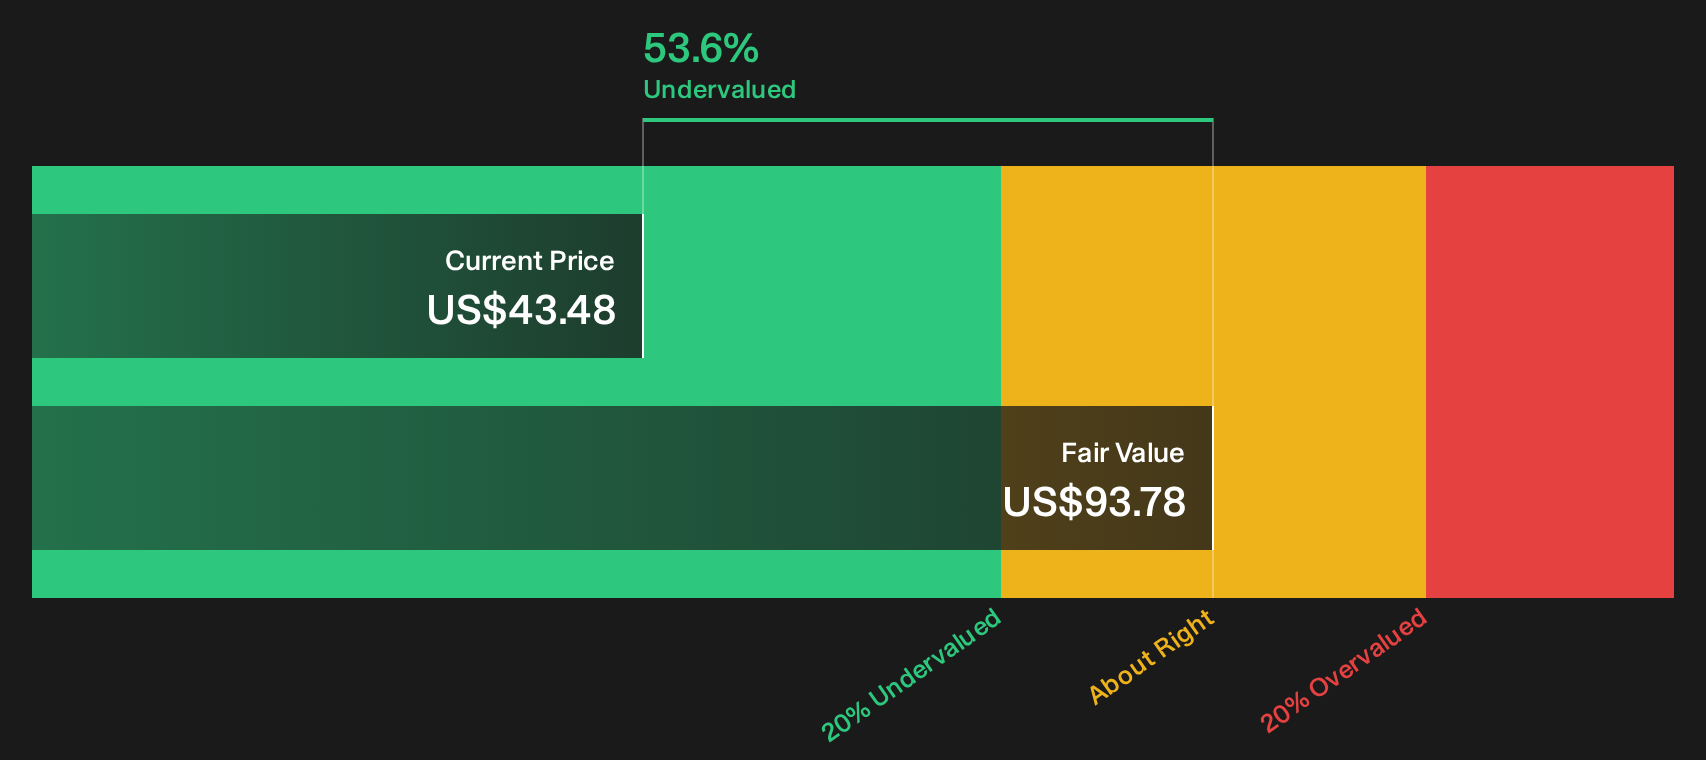
The first narrative leans on a fair value of $56.56, yet Alkermes trades on a P/E of 110.3x compared with 18.1x for the US Biotechs group, a peer average of 89.9x and a fair ratio of 41.7x. That rich gap suggests valuation risk if sentiment cools and multiples compress.
For investors weighing which signal to trust more, it helps to see how those earnings based ratios compare with a full cash flow view using the SWS DCF model, and how sensitive that output is to the orexin pipeline assumptions in particular. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Alkermes often spark strong opinions. Move quickly, review the underlying data yourself, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more Alkermes sized opportunities?
Do not park everything in one idea. Widen your universe with a few targeted stock lists that surface different kinds of opportunities across the market.
- Target rock solid balance sheets and resilient fundamentals with the list of solid balance sheet and fundamentals (25 results) to reduce the risk of fragile finances derailing your thesis.
- Hunt for quality businesses that the market may be overlooking by scanning the 21 high quality undiscovered gems before everyone else catches on.
- Prioritise stability and income potential using the 7 dividend fortresses so you are not relying only on price moves for returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com