


Will Energy Drink Growth Change Monster Beverage's (MNST) Narrative
- Monster Beverage reported currency adjusted Q2 2026 sales growth of 19.3% in its Monster Energy Drinks segment, while Alcohol Brands segment sales declined 15.2% as the firm continued to work through volume and scaling issues.
- The long running Coca Cola partnership remains central. Monster Beverage continues to rely on that distribution system to push new low and zero sugar variants and deepen reach across APAC, EMEA and LATAM, even as alcohol products face operational friction.
- We will now examine how Monster Beverage's strong Monster Energy Drinks segment growth interacts with its broader investment narrative and cost pressures.
Monster Beverage Investment Narrative Recap
To hold Monster Beverage, you need to believe the core energy drinks engine can keep doing the heavy lifting while management contains cost inflation and fixes Alcohol Brands execution issues. The immediate upside hinge is whether strong Monster Energy Drinks segment growth can support operating leverage as distribution, freight, fuel and aluminum costs put pressure on margins.
The biggest short term risk is that Alcohol Brands keeps underperforming and turns into a drag on consolidated earnings while cost lines creep higher as a share of net sales. This Q2 mix, strong energy and weaker alcohol, reinforces that risk but does not materially change it. The core thesis remains centered on energy drinks scale and pricing.
The Coca Cola relationship is the announcement that still matters most in light of this update. That equity stake and transfer of Coca Cola’s global energy drinks portfolio created the framework Monster Beverage is using today to push low and zero sugar variants and reach markets like APAC, EMEA and LATAM with more efficiency.
Current execution in international channels runs directly through that system, from Monster Energy Green vending in Japan to broader food service wins. For you as an investor, the key question is whether this distribution backbone can keep supporting energy segment growth in the double digits while offsetting weaker Alcohol Brands performance and higher logistics and commodity costs.
What The Monster Beverage Forecasts Are Asking You To Believe
Analysts are effectively asking you to underwrite a bigger Monster Beverage by the end of the decade. The consensus framework leans on the idea that the energy franchise can keep doing enough work to support rising earnings while Alcohol Brands and cost inflation remain controlled rather than fixed outright.
The stock analysis points to a revenue growth assumption of 9.6% each year over the next 3 years, paired with a profit margin shift from 23.1% today to 24.1% by around 2029. That setup implies that management would not just hold the line on input and freight costs, but also squeeze a bit more profit out of each dollar of sales even while aluminum and logistics stay pressured.
On the earnings side, the consensus view anchors around profits climbing from US$2.1b today to US$2.9b by 2029. That is a US$0.8b step up that depends heavily on the same themes already showing up in Q2 2026: a strong Monster Energy Drinks segment, Coca Cola system reach across APAC, EMEA and LATAM, and some relief from mix and pricing as more low and zero sugar variants scale.
Monster Beverage's narrative projects US$12.1b revenue and US$2.9b earnings by 2029. This assumes 9.6% yearly revenue growth and an earnings increase of about US$0.8b from US$2.1b today.
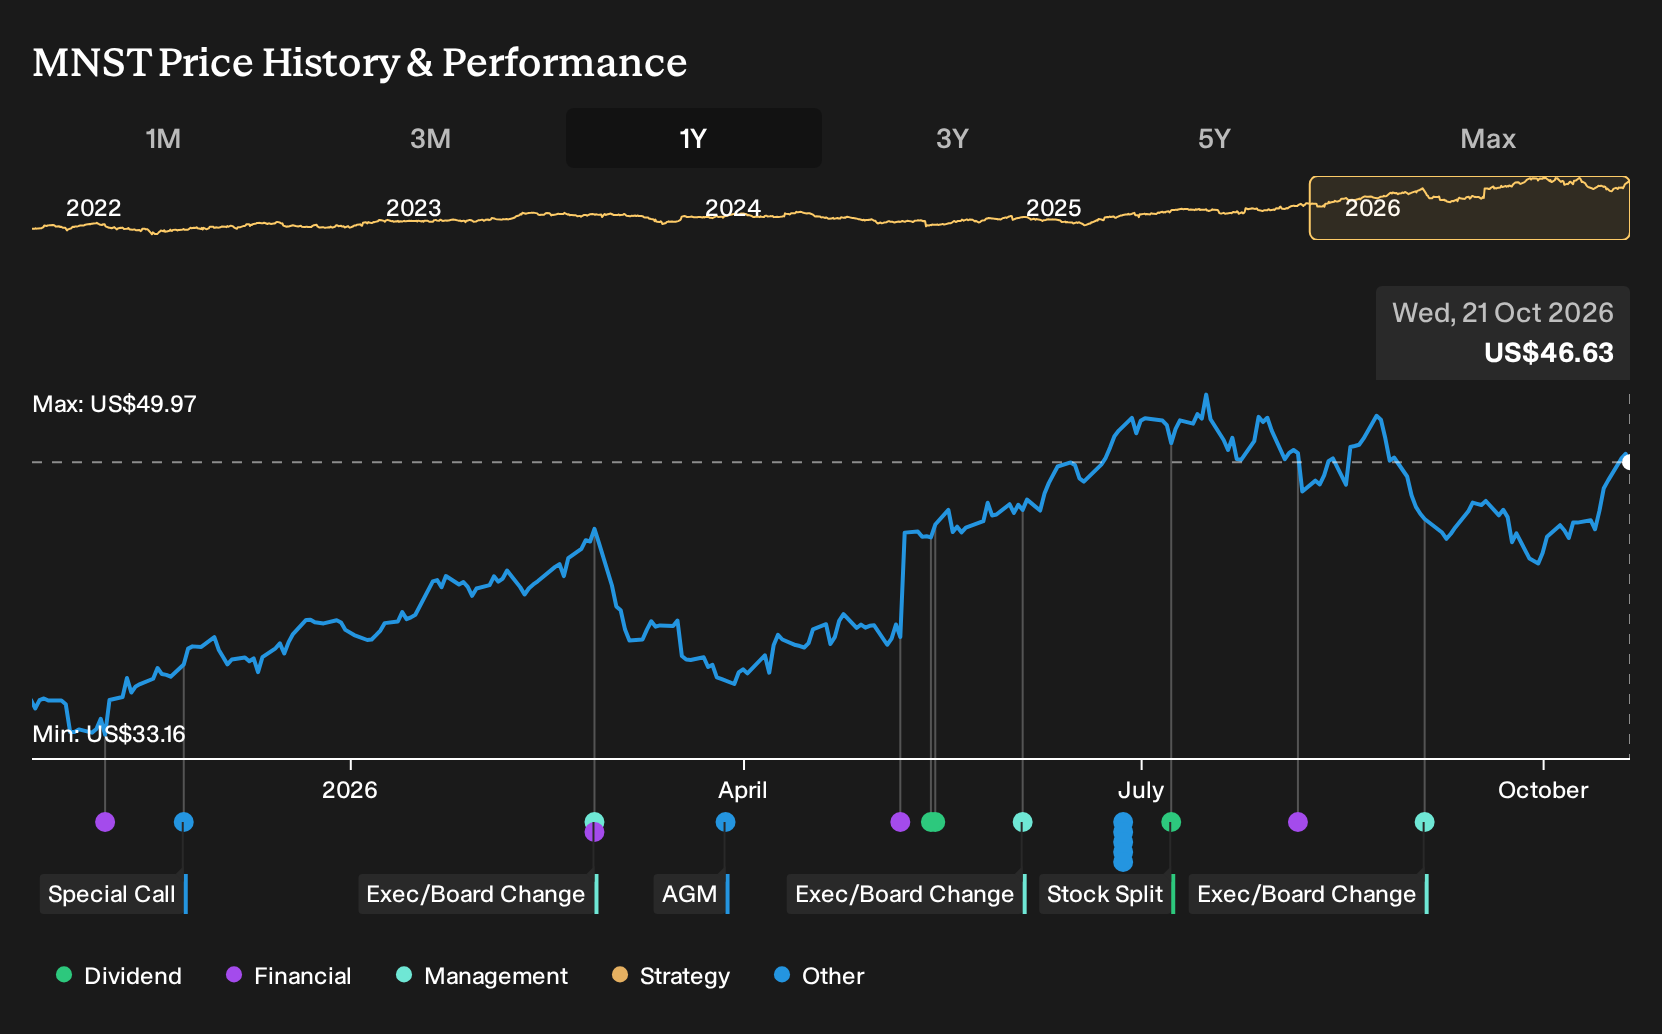
Valuation work in the consensus bundle then layers a P/E assumption on top. To get to the US$50.24 price target from a current share price of US$41.62, the analysis uses a 41.8x multiple on those 2029 earnings versus roughly 38.3x today for Monster Beverage and about 26.1x for the broader US beverage peer group. That is a clear premium and it only holds together if the revenue growth, margin lift and earnings bridge all land close to plan.
There is also some spread in opinion. The most bullish target at US$57 and the most cautious at US$35 show that not every analyst assigns the same weight to execution risks around Alcohol Brands, share count creeping up 0.26% a year, or the prospect of aluminum and freight staying higher for longer. For you as an investor, the task is to test whether the 9.6% growth path and margin expansion feel realistic given Monster Beverage's Q2 2026 mix of strong energy drinks performance and weaker alcohol, rather than simply accepting the midpoint of that target range.
Uncover how Monster Beverage's fair value indicates an 8% potential upside to its current price that could narrow quickly if Monster Beverage keeps executing to plan.
Exploring Other Perspectives
One alternate view puts less weight on Q2’s 19.3% Monster Energy Drinks segment jump and focuses on the risk that energy drink category growth cools over time. Those more cautious analysts were penciling in about US$11.5b of revenue and US$3.0b of earnings by 2029, which supported a lower Fair Value and a P/E closer to 33.8x. That is a meaningfully more pessimistic narrative than consensus. Both sets of forecasts came before this latest Alcohol Brands weakness, so you should expect some opinions to shift. Use that spread to test your own stance on Monster Beverage rather than treating any single target as a truth.
Explore 3 other Monster Beverage fair value estimates, including one that suggests as much as 12% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Monster Beverage?
If the Monster Beverage story has sharpened your thinking and you want to line it up against other opportunities, the Simply Wall St Screener can help you build a wider watchlist that fits your risk, quality, and income preferences.
- For investors who care most about resilience and downside protection, scan a set of companies with steadier profiles through the 31 resilient stocks with low risk scores.
- If strength of balance sheet and fundamentals is your filter, compare Monster Beverage with businesses highlighted in our list of solid balance sheet and fundamentals (25 results).
- When you want growth potential backed by quality metrics rather than hype, broaden your search using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com