


Skyworks Solutions (SWKS) Stock Looks Fully Valued Even Against Current Earnings
Skyworks Solutions has seen its share price move around over different time frames, and that naturally raises a question for you as an investor. Is the current US$82.22 price tag adequately grounded in the earnings power the business generates today?
- Over the past 5 years the stock has declined 42.9%, which puts extra weight on whether the earnings profile now supports a different long term story than the one shareholders have lived through.
- The group’s role in supplying chips into high volume connectivity and mobile devices can heavily influence how much of its profit is tied to a few large customers, which in turn may affect how durable its earnings base looks.
- There is a second opinion on Skyworks Solutions worth weighing. See what analysts think Skyworks Solutions's shares could be worth.
The stock’s next move may depend on whether Skyworks Solutions’ current earnings are strong and reliable enough to justify today’s valuation.
If you are weighing whether Skyworks Solutions’ earnings justify the current US$82.22 share price, it can help to compare that question against a wider set of 33 high quality undervalued stocks
Has Skyworks Solutions Run Too Far on Earnings?
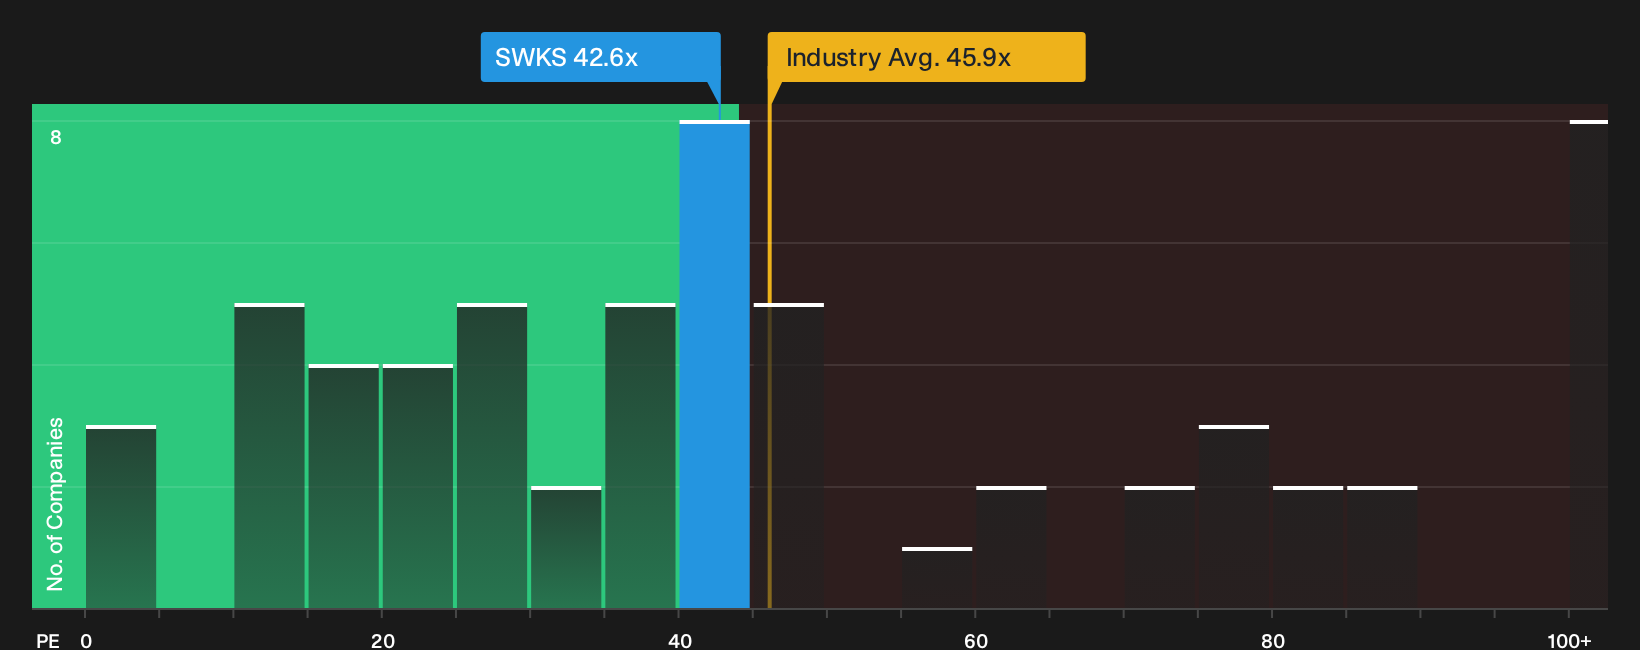
P/E is usually the cleanest shorthand for what you are paying today for Skyworks Solutions’ current earnings stream. At the recent price, the stock trades on a P/E of 42.6x, compared with a Semiconductor sector average around 45.9x and a peer group closer to 59.7x, so the headline ratio sits below many direct comparables.
The fair multiple that folds in Skyworks Solutions’ own mix of growth profile, margins, size and risk comes out lower than the current 42.6x. This means the shares screen overvalued on this framework even if the gap to the sector is not huge. For you as a shareholder, the key question is whether the company’s earnings quality and customer concentration justify paying more than that tailored reference point for each dollar of profit today. Explore the numbers behind Skyworks Solutions's P/E valuation.
The Skyworks Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Skyworks Solutions leaves off and explain which combinations of future growth, profitability and earnings power would need to occur for the stock to be worth materially more or materially less than today’s price, all housed on the Community page. Each scenario links a fair value to a clear storyline about Skyworks Solutions' possible catalysts and pressure points so you can track over time which version of events appears to be unfolding.
The Skyworks Solutions community splits between one camp that thinks the merger and product pipeline are underappreciated and another that sees those same drivers already priced in.
Bull case: 18% undervalued
"The decision to eliminate the quarterly dividend and authorize a US$2b buyback program to 2029, combined with a focus on deleveraging and targeted M&A, creates scope for Skyworks Solutions to adjust share count, interest expense and acquired product portfolios in ways that could alter reported earnings per share and net margin over time..."
Discover why this Narrative puts Skyworks Solutions at 18% undervalued.
Bear case: 8% overvalued
"The current valuation implies the market is already pricing Skyworks Solutions for successful execution on RF content growth, broad market expansion and merger synergies, even though this narrative views the stock as overvalued and bearish..."
Explore why this Narrative puts Skyworks Solutions at 8% overvalued.
An unresolved piece of the Skyworks Solutions story
All of this still leaves one angle open: how professional analysts currently see Skyworks Solutions a few years down the road compared with where the valuation sits today. Explore where analysts expect Skyworks Solutions to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com