


Cameco (TSX:CCO) After Westinghouse Fuel Plant Start Has Its Valuation Case Changed
Westinghouse has started building a US$1b commercial LEU+ fuel plant in South Carolina, and Cameco (TSX:CCO), which owns 49% of the venture, now has deeper exposure to next generation nuclear fuel demand.
Cameco’s share price has been under pressure, with a 30 day share price return down 12.04% and the year to date move down 14.88%, even though the 3 year total shareholder return of 113.99% and 5 year total shareholder return of 270.89% still point to strong longer term momentum. Recent weakness has tracked broader selling in reactor developers after higher Treasury yields, while policy support for nuclear in Canada and the long term India supply deal have kept interest focused on Cameco’s exposure to future fuel demand and perceived risk around the story rather than any single headline.
Scan the nuclear fuel theme more broadly by comparing Cameco with hand-picked infrastructure peers in our 16 nuclear energy infrastructure stocks to see how this story compares across the sector.
The question now is whether Cameco’s recent slide reflects a shift in how investors feel about nuclear exposure, or a gap opening between price and the underlying business. It is time to weigh what the current valuation implies.
Most Popular Narrative: 36% Undervalued
Cameco’s most followed thesis pegs fair value around CA$179 per share, compared with the recent CA$115.22 close. This frames the current pullback as a potential discount rather than a verdict on the business.
Ongoing structural supply tightness in the Western nuclear fuel chain now includes tight conversion markets. Port Hope has reached record UF6 output and conversion pricing is at historically high levels, while new long-term contracts such as the approximately C$2.6b India agreement add contracted volumes that can underpin future revenue visibility and EBITDA.
See why 156 investors see Cameco as 36% undervalued.
Result: Fair Value of CA$179 (UNDERVALUED)
Still, this Cameco story can be knocked off course if Saskatchewan production issues drag on or if major Westinghouse projects are delayed, pushing back expected cash flows.
Find out about the key risks to this Cameco narrative.
Another View: What Cameco’s P/E Is Telling You
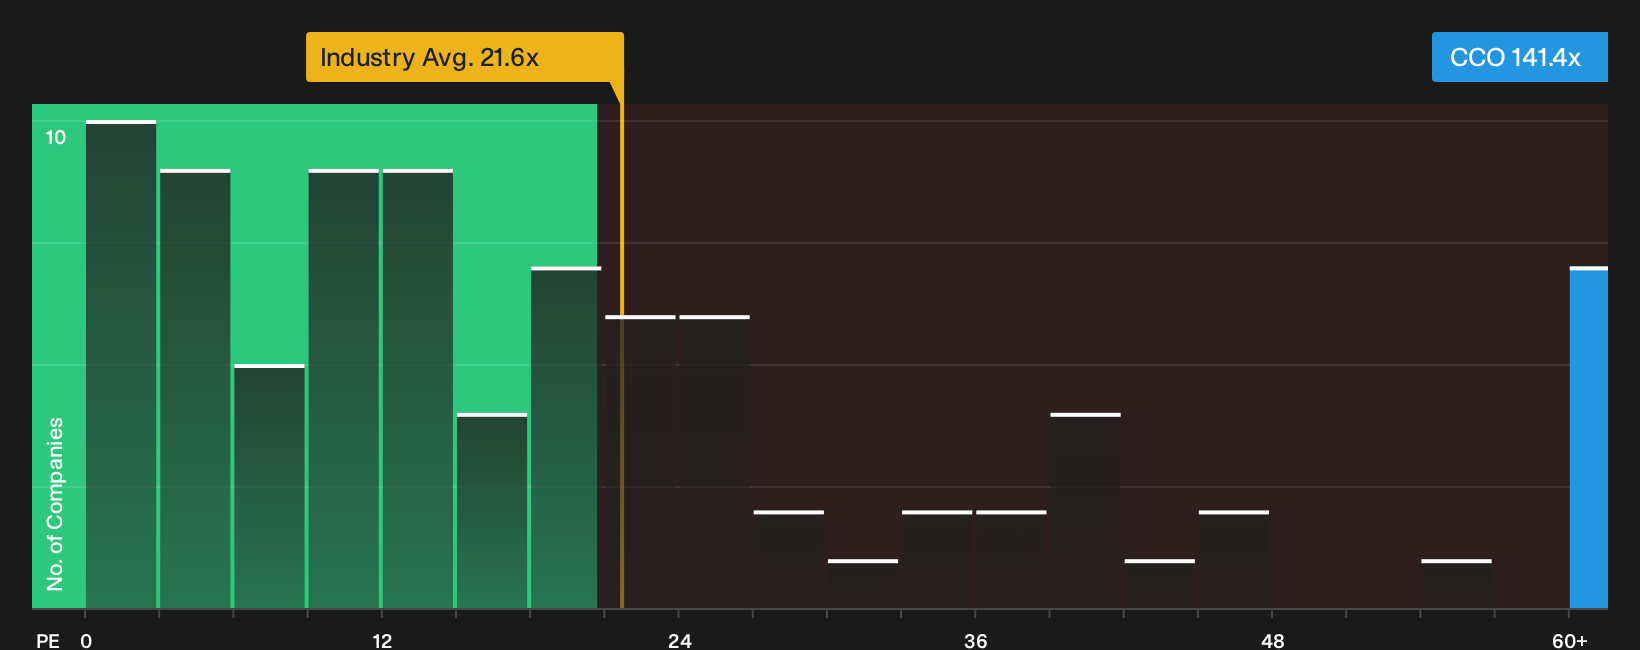
Cameco may screen as undervalued on fair value models, yet its P/E of 141.4x is far above the Canadian Oil and Gas industry at 21.6x, peers at 20x, and a fair ratio of 27.9x. That gap loads a lot of expectation into the price. How comfortable are you paying that much upfront for growth that still has to arrive?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Cameco’s story so far. Act while sentiment is still split and test the data for yourself with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cameco?
Do not stop with Cameco. Broaden your watchlist now, because the opportunities you skip today are the ones someone else will act on tomorrow.
- Target potential bargains by scanning for resilient quality at a discount with the 4 high quality undervalued stocks.
- Prioritise stability and sleep-better-at-night positions using the 8 resilient stocks with low risk scores before volatility picks your portfolio for you.
- Hunt for under-the-radar potential by tracking financially sound outliers through the 10 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com