


We're Keeping An Eye On Lokotech Group's (OB:LOKO) Cash Burn Rate
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So, the natural question for Lokotech Group (OB:LOKO) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
How Long Is Lokotech Group's Cash Runway?
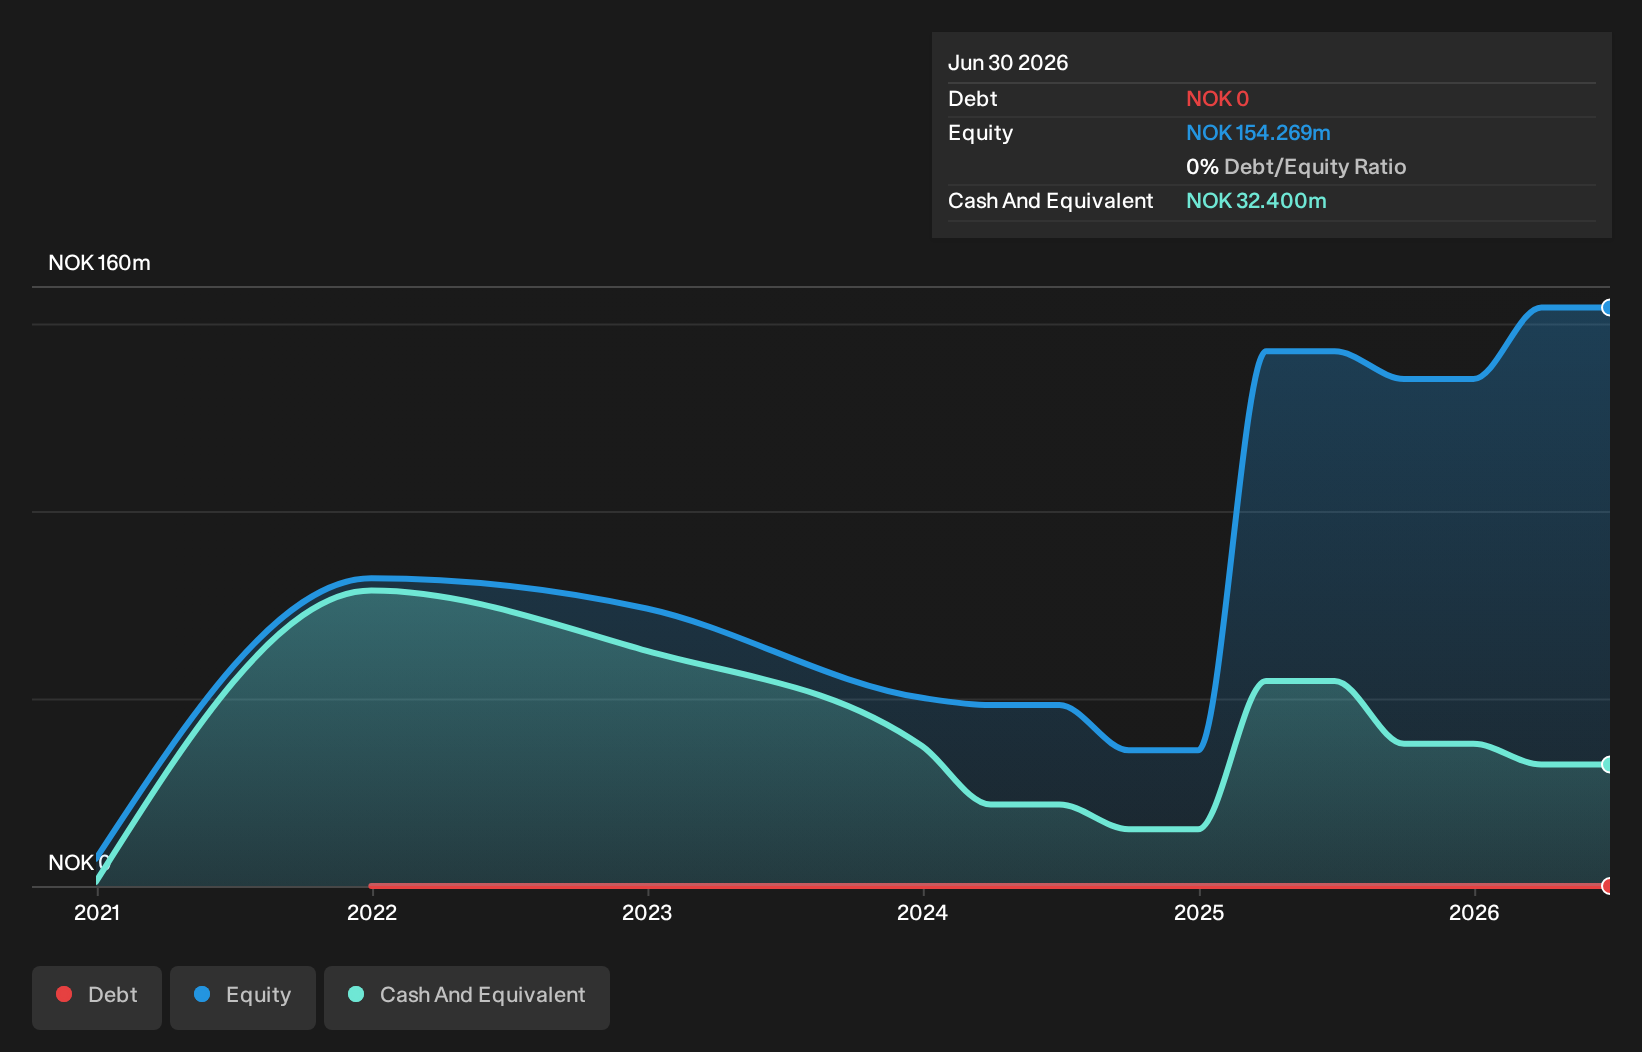
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, Lokotech Group had kr32m in cash, and was debt-free. Importantly, its cash burn was kr62m over the trailing twelve months. That means it had a cash runway of around 6 months as of June 2026. Importantly, the one analyst we see covering the stock thinks that Lokotech Group will reach cashflow breakeven in 3 years. Essentially, that means the company will either reduce its cash burn, or else require more cash. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for Lokotech Group
How Is Lokotech Group's Cash Burn Changing Over Time?
Whilst it's great to see that Lokotech Group has already begun generating revenue from operations, last year it only produced kr8.9m, so we don't think it is generating significant revenue, at this point. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. As it happens, the company's cash burn reduced by 45% over the last year, which suggests that management are mindful of the possibility of running out of cash. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
Can Lokotech Group Raise More Cash Easily?
While Lokotech Group is showing a solid reduction in its cash burn, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of kr455m, Lokotech Group's kr62m in cash burn equates to about 14% of its market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
Is Lokotech Group's Cash Burn A Worry?
On this analysis of Lokotech Group's cash burn, we think its cash burn reduction was reassuring, while its cash runway has us a bit worried. One real positive is that at least one analyst is forecasting that the company will reach breakeven. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. Separately, we looked at different risks affecting the company and spotted 4 warning signs for Lokotech Group (of which 1 is potentially serious!) you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.