


Is Valle Ancho Spinout Altering The Investment Case For NGEx Minerals Stock?
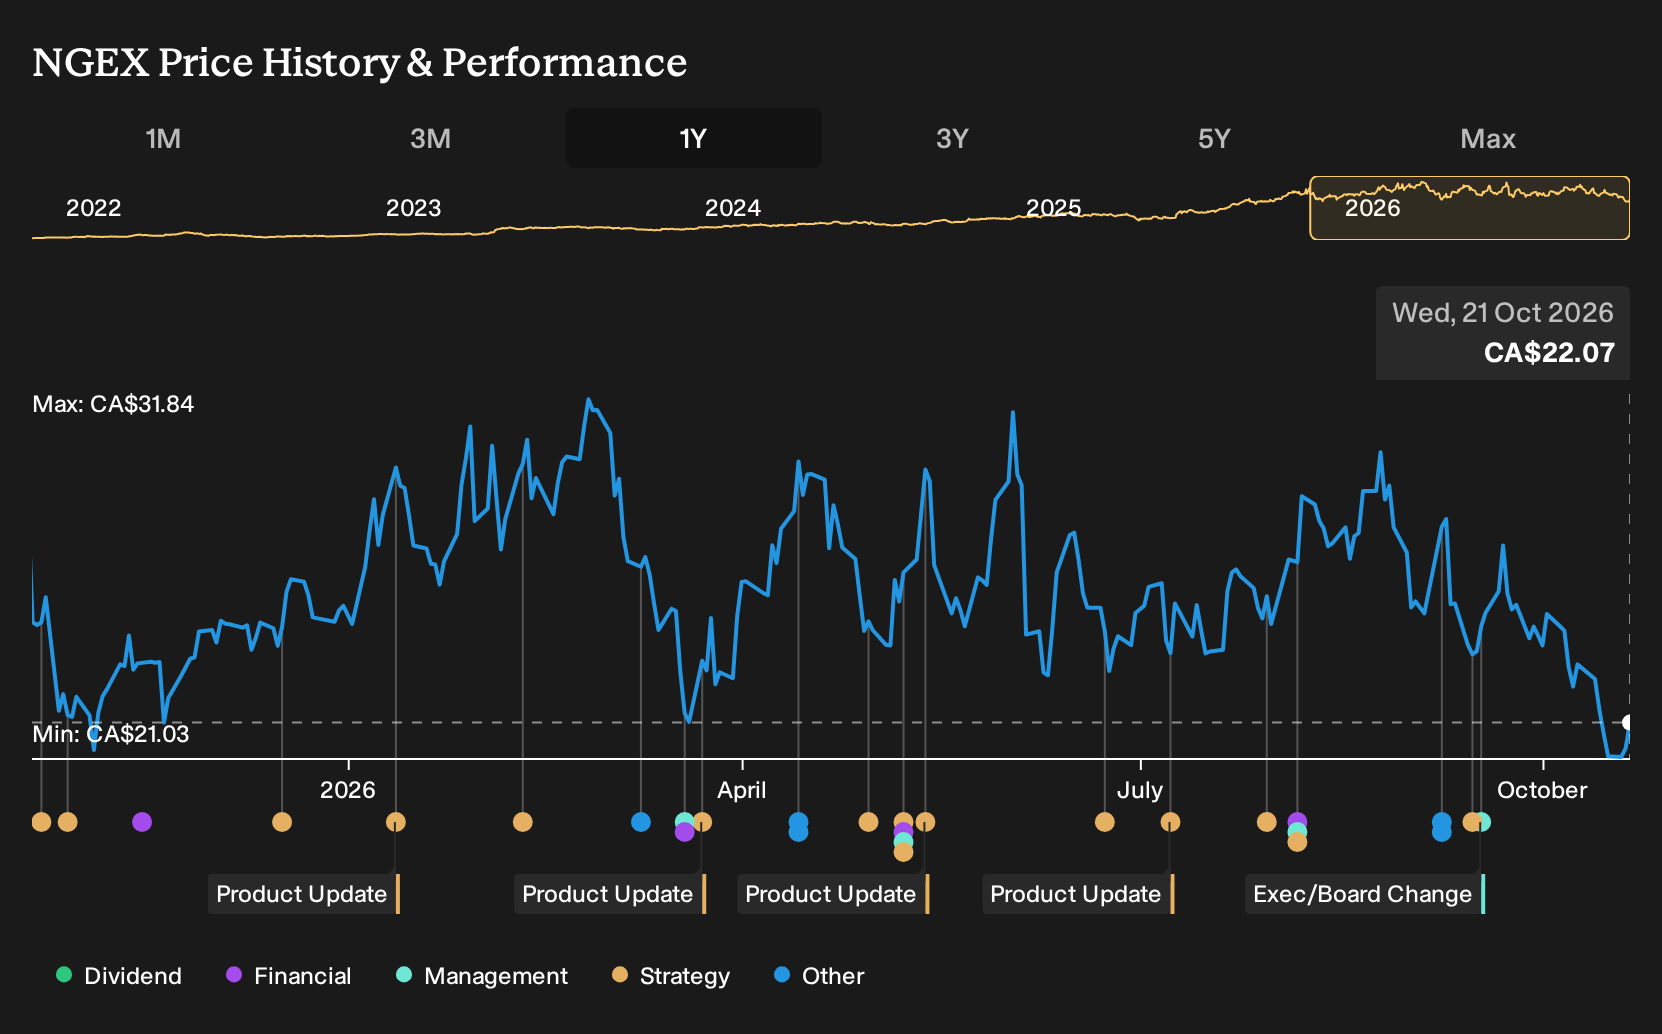
- NGEx Minerals has moved to spin out its Valle Ancho project into Valiente Resources Inc., prompting fresh attention on how this changes its portfolio of South American exploration assets and associated capital needs.
- The business now trades at a sizeable premium to book value compared with peers, which puts day to day focus on whether its exploration pipeline and royalty holdings justify such a rich balance sheet multiple.
- This article examines how NGEx Minerals' premium to book value and the Valle Ancho spin out plan could reshape its investment narrative.
Compare NGEx Minerals' premium story with other high potential miners by scanning our hand picked 16 top copper producer stocks that could be gearing up for their next big rerating.
NGEx Minerals Investment Narrative Recap
To own NGEx Minerals today, you need to be comfortable backing a pure explorer with no current revenue and a high P/B multiple that rests on Lunahuasi and Los Helados eventually maturing into economic projects. The key short term swing factor remains drill results and technical work around Lunahuasi, which feeds directly into how investors view the scale and quality of that asset.
The biggest operational risk is simple. Heavy exploration spending and a widened net loss, without incoming cash flow, could stretch funding needs if project progress slows or results disappoint. The Valle Ancho spin out does not materially change that near term equation, although it may sharpen attention on capital allocation into the remaining core projects.
The Valle Ancho transfer into Valiente Resources is the announcement that ties most closely to the current debate around NGEx Minerals and its premium to book value. Moving this project into a separate vehicle places a clearer spotlight on Lunahuasi and Los Helados as the engines that need to justify the current valuation and ongoing spend.
For you as a shareholder, the key question is whether a leaner portfolio, together with the LunR Royalties stake and the prior US$175 million placement, provides enough financial flexibility to support intensive work at Vicuña without frequent fresh equity. If drilling, underground access, metallurgical work or permitting at Lunahuasi slip, the absence of Valle Ancho inside the group does not remove the risk of delays or future dilution.
NGEx Minerals' narrative projects CA$510.5 million of revenue and CA$160.4 million of earnings by 2029. This implies revenue growth from a zero base and an earnings increase of about CA$291.3 million from the current loss of CA$130.9 million, moving from no revenue today to a forecast profit profile in that estimate year.
Uncover why NGEx Minerals' fair value indicates a 62% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between CA$35.51 and CA$63.02, which leaves room for both steep discount and rich premium arguments around NGEx Minerals. When you set that against heavy exploration spend, a 10.7x P/B ratio and the Valle Ancho spin out, you get sharply different investor opinions. Use that spread to test your own thesis and weigh several alternative viewpoints before committing fresh capital.
Explore 3 other NGEx Minerals fair value estimates, including one that suggests it could be worth just CA$35.51.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NGEx Minerals research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NGEx Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NGEx Minerals' overall financial health at a glance.
Looking for more investment ideas beyond NGEx Minerals?
Once you have a view on NGEx Minerals, it can help to balance that single idea with a shortlist of other opportunities that fit your own risk, income, and quality preferences.
- If you want potential upside without paying up for quality, start by scanning a curated set of 4 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into their prices.
- If income matters more than headlines, focus your attention on a hand picked group of 3 dividend fortresses that prioritize regular payouts and cash generation.
- If capital preservation sits near the top of your checklist, anchor your watchlist around a 8 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com