


AGNC Investment (AGNC) Could Be 26% Below Fair Value As Losses Raise Questions
AGNC Investment (AGNC) just posted a third quarter net loss of US$1.36b, swinging from net income of US$806m a year earlier and putting the mortgage REIT’s earnings profile under closer investor scrutiny.
AGNC Investment’s share price has slid roughly 12% over the past month and about 17% over 90 days, signalling fading near term momentum even as the 3 year total shareholder return of about 95% points to a very different longer run picture.
Scan how AGNC Investment’s recent volatility compares with other higher yield plays by reviewing our hand-picked 7 dividend fortresses across the market.
AGNC Investment now trades at a clear discount to some analyst targets and estimated fair value, yet the latest quarterly loss has shaken confidence. Is that gap a genuine opportunity, or a warning sign about risk pricing?
Preferred Price-to-Sales of 46.9x: Is it justified?
AGNC Investment screens as expensive on its preferred valuation yardstick, with a P/S of 46.9x against a last close of $8.78, even though some models flag a discount to estimated fair value.
P/S compares the market value of the equity to the revenue the business generates. It gives a quick sense of how much investors are paying for each dollar of top line. For a mortgage REIT like AGNC Investment, an elevated P/S can signal that the market is assigning a rich tag to its income stream relative to peers.
Here the gap is wide. Management is running a REIT that is currently unprofitable. The P/S of 46.9x sits well above the Mortgage REITs industry average of 3.5x, and it also exceeds an estimated fair P/S of 7.6x that the market could eventually move toward.
Explore the SWS fair ratio for AGNC Investment.
Result: Price-to-sales of 46.9x (OVERVALUED)
Still, the reported net loss of US$76m and the recent double digit share price slide could signal that both income sustainability and risk appetite are under pressure.
Find out about the key risks to this AGNC Investment narrative.
Another view on AGNC Investment’s value
The preferred sales multiple presents AGNC Investment as expensive, yet the SWS DCF model offers a different perspective. At $8.78, the stock trades about 26% below an estimated future cash flow value of $11.94, which suggests that recent weakness may reflect a potential valuation gap rather than pure overpricing.
Look into how the SWS DCF model arrives at its fair value.
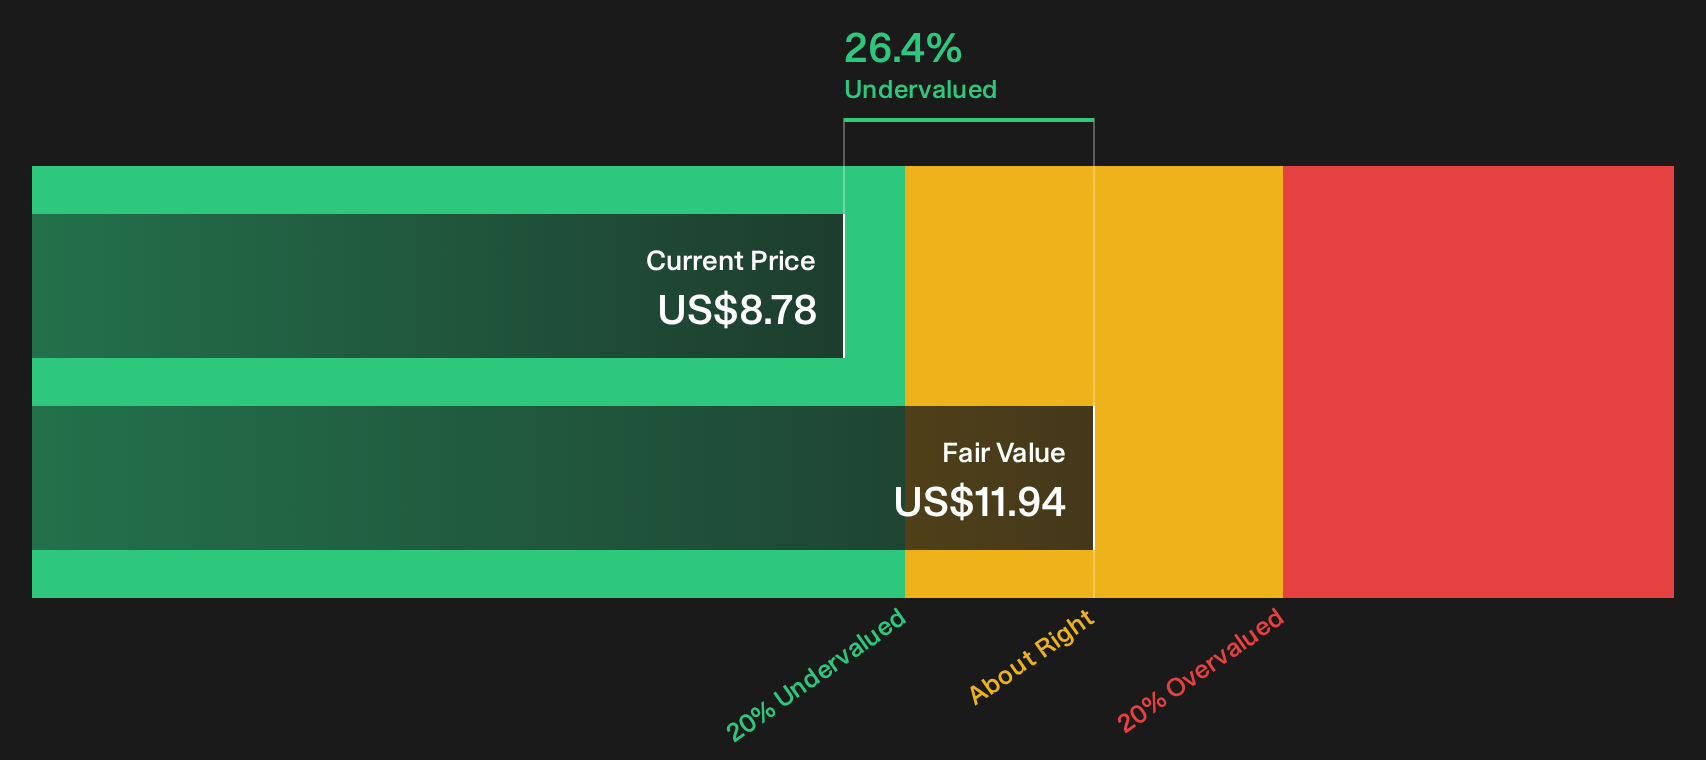
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AGNC Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on AGNC Investment’s value and risk profile can feel confusing. Move quickly based on the data rather than the noise and form your own stance using the 2 key rewards and 3 important warning signs.
Looking for more AGNC Investment style ideas?
If AGNC Investment has sharpened your focus on value, do not stop here. Broader idea generation can help you build a stronger, more resilient portfolio.
- Spot potential mispricings early by checking the 33 high quality undervalued stocks that align with strong fundamentals and disciplined pricing.
- Strengthen your downside protection by reviewing the 31 resilient stocks with low risk scores that pair financial resilience with measured risk profiles.
- Get ahead of the crowd by scanning the 21 high quality undiscovered gems that combine quality metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com