


Indigenous Pipeline Deal Might Change The Case For Investing In TC Energy Stock
- TC Energy reported the closing of an agreement with FN CGL Pipeline Limited Partnership, giving five First Nations an economic interest in the entity that holds TC Energy’s limited partner stake in the Coastal GasLink pipeline.
- The creation of an Indigenous owned and financed partnership around Coastal GasLink adds a long term community alignment layer that directly affects project stability, cash flow visibility and execution risk for TC Energy’s gas infrastructure portfolio.
- The next area of focus will be how TC Energy’s investment narrative interacts with this new Indigenous ownership stake in Coastal GasLink.
Scan opportunities that reflect TC Energy's focus on long term, infrastructure-style cash flows by reviewing our curated list of 42 power grid technology and infrastructure stocks in one place.
TC Energy Investment Narrative Recap
To own TC Energy, you need to be comfortable with a regulated, capital intensive pipeline and power business that targets long lived, infrastructure style cash flows instead of rapid growth. The short term swing factor is still execution on its large gas pipeline portfolio alongside balance sheet discipline, since interest costs and dividend coverage remain key pressure points.
The new Coastal GasLink Indigenous partnership mainly influences execution risk and social license rather than near term earnings. Unless it meaningfully changes project timing or capital needs, the bigger immediate watch items stay the same: contract renewals, funding costs and how comfortably TC Energy services its debt and dividend.
The Coastal GasLink Indigenous ownership deal links most clearly to existing concerns around regulatory and stakeholder challenges that could delay projects or raise costs. More aligned local communities can reduce the odds of future disruptions, which directly affects construction timelines, utilization and how reliably the asset supports TC Energy’s contracted revenue base.
At the same time, the arrangement does not remove the bigger structural questions flagged for the business, such as long term gas demand under climate policy pressure and the company’s current reliance on higher risk external borrowing. For you as a shareholder, this news mainly tweaks execution risk on one core asset while the broader catalysts and balance sheet risks stay intact.
TC Energy's current analyst narrative points to CA$18.5b revenue and CA$4.7b earnings by 2029, based on consensus estimates. That profile implies 5.7% yearly revenue growth and an earnings increase of about CA$1.0b from CA$3.7b today.
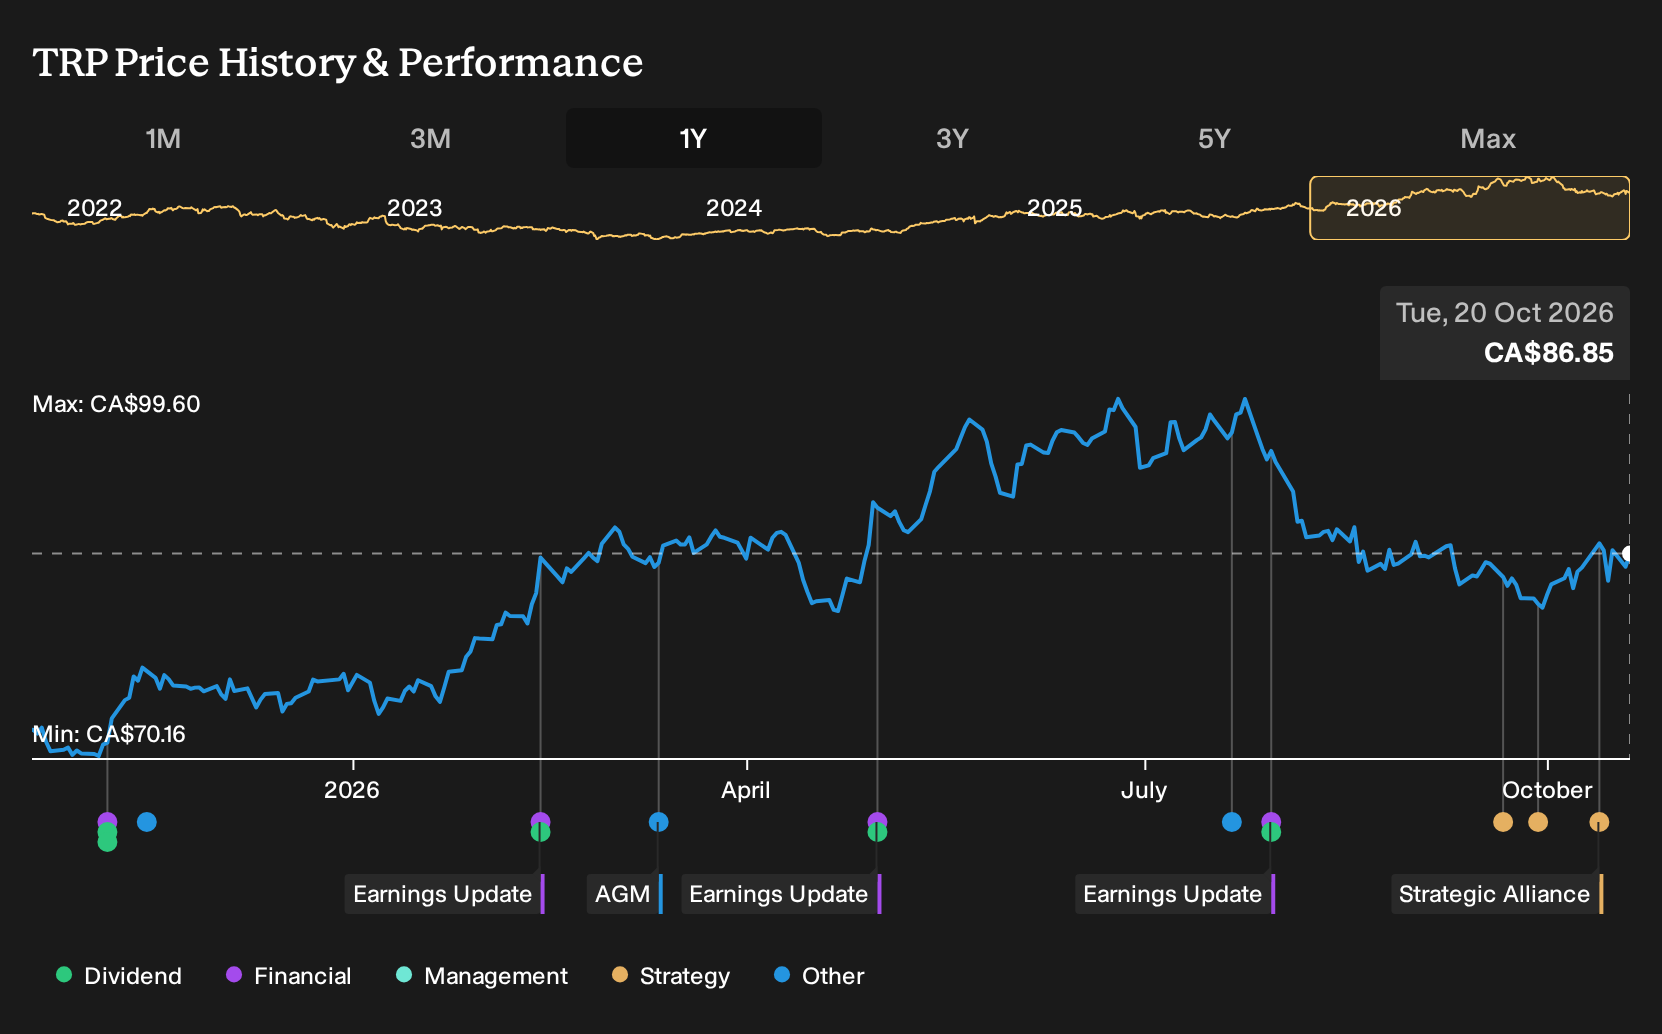
Uncover why TC Energy's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views for TC Energy, yet the span is wide, from CA$33.13 to CA$100.77. That gap reflects how far opinions can stretch. Considering the long term gas demand debate and balance sheet pressures, the Coastal GasLink news becomes just one of several moving parts you should weigh.
Explore another TC Energy fair value estimate, including one that suggests potential upside of as much as 16% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own analysis.
- A great starting point for your TC Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TC Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate TC Energy's overall financial position at a glance.
Looking for more investment ideas beyond TC Energy?
If you want to pressure test your thesis on TC Energy or simply broaden your watchlist, it helps to compare it with other businesses that share similar qualities or offer very different risk and income profiles.
- For investors who care most about financial resilience, start with companies that pair sturdy balance sheets with solid fundamentals by checking our list of solid balance sheet and fundamentals (7 results).
- If your priority is finding resilient opportunities with lower overall risk profiles, scan the 8 resilient stocks with low risk scores and see which stocks line up with your tolerance for volatility and drawdowns.
- Those hunting for underappreciated quality can review our 10 high quality undiscovered gems and spot businesses that the broader market may not be focusing on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com