


Ayalon Insurance (TASE:AYAL) Tests Its Valuation On CAL Deal Talk
Why Ayalon Insurance's Capital Moves Matter Now
Ayalon Insurance (TASE:AYAL) is back in focus as investors weigh its capital allocation record against talks around a potential purchase of CAL Israel Credit Cards, a deal that could reshape returns on equity.
The recent discussion around a possible CAL Israel Credit Cards acquisition comes on top of strong share price momentum, with a 90 day share price return of 28.48% and a year to date share price return of 112.07%. At the same time, the 1 year total shareholder return of 180.30% and very large 3 and 5 year total shareholder returns suggest long term investors have already seen substantial gains, so any new deal now feeds into a story where expectations are already elevated and the market is actively reassessing Ayalon Insurance's risk and reward profile.
Scan how Ayalon Insurance's capital allocation compares with other potential compounders by checking our curated list of 188 high quality undervalued stocks.Bulls see Ayalon Insurance using its CAL move to support stronger returns on equity. Bears see a stretched story around already rich gains. Which side do the current valuation markers lean toward?
Preferred P/E of 11.8x: Is it justified?
Ayalon Insurance is trading on a P/E of 11.8x, with the last close at ₪184.5, and that puts the valuation above both peer and regional insurance averages.
The P/E ratio compares the current share price to earnings per share. For an insurer like Ayalon Insurance, it effectively shows how much investors are paying for each unit of current profit and how confident they are that those earnings can be maintained or improved.
High quality earnings, a 24.7% return on equity and profit margins that are higher than last year all help to explain why investors might be willing to accept a richer P/E. Earnings have also grown 55.2% per year over the past 5 years, although the most recent 27.1% earnings growth rate is below that longer run pace.
The comparison line is stark. Ayalon Insurance trades on 11.8x earnings, which is described as expensive compared to the Asian insurance industry at 10.4x and also expensive versus a 9x peer average, even though the P/E is below the wider IL market at 14.7x.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 11.8x (OVERVALUED).
Still, any Ayalon Insurance bid for CAL or shift in underwriting quality could pressure returns on equity and challenge the current premium P/E story.
Find out about the key risks to this Ayalon Insurance narrative.
Another View: What The SWS DCF Model Says
The market is treating Ayalon Insurance as expensive on an 11.8x P/E, yet the SWS DCF model points to a different conclusion. On that framework, the estimated future cash flow value sits at ₪171.23 per share, which is below the current ₪184.5 price. That flags Ayalon Insurance as overvalued on this measure and raises a simple question for investors: Which signal should carry more weight, earnings strength today or what the cash flows imply about tomorrow?
Look into how the SWS DCF model arrives at its fair value.
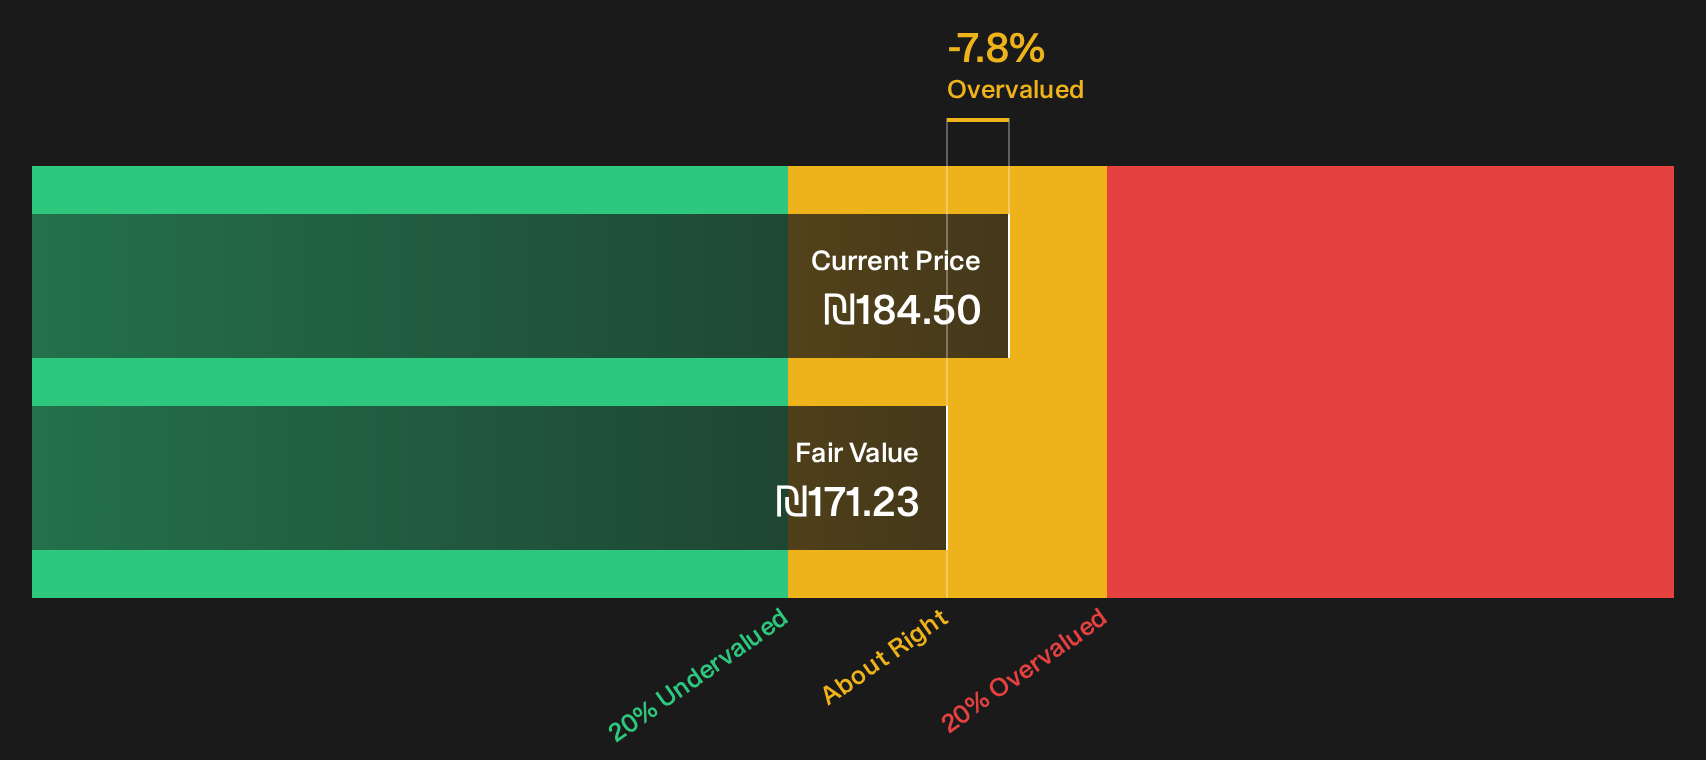
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ayalon Insurance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 188 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Ayalon Insurance's story so far. If the risk reward balance looks finely poised, it may be worth moving quickly to review the full picture and weigh the 2 key rewards and 1 important warning sign.
Looking for more Ayalon Insurance style ideas?
If Ayalon Insurance has you rethinking what belongs in your portfolio, do not stop here. The real edge comes from comparing it against fresh, high conviction ideas surfaced by targeted screeners.
- Target stronger downside protection by reviewing a focused 228 resilient stocks with low risk scores that prioritises balance sheet resilience and historically steadier trading profiles.
- Hunt for quality at a discount by scanning a curated 188 high quality undervalued stocks that blends solid cash generation with disciplined financial structures.
- Spot tomorrow's quiet outperformers by working through a 616 high quality undiscovered gems built to highlight under-followed businesses with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com