


InPost (ENXTAM:INPST) Shares Climbed, What Is Behind The Move?
InPost (ENXTAM:INPST) has been removed from the FTSE All-World Index (USD), an index reshuffle that can prompt index-tracking funds to rebalance and influence trading volumes around the stock.
At around €15.60, InPost’s recent 1-day share price return of 2.63% and 7-day gain of 1.43% sit against a softer 30-day share price move that declined 1.70%. Year-to-date share price momentum of 50.00% and a 3-year total shareholder return of 67.81% indicate that longer term performance has remained strong even as the index removal event reshapes how some investors assess risk around the stock.
Scan how other high-growth logistics and e-commerce enablers are priced right now by reviewing the hand-picked 616 high quality undiscovered gems alongside InPost’s latest index reshuffle move.
Index removal is one story; where fair value sits is another. With InPost at about €15.60 and a cluster of higher analyst estimates, how wide is the gap that current holders are really underwriting?
Most Popular Narrative: 13% Undervalued
InPost last closed at €15.60, while the most followed narrative pins fair value closer to €17.89. The gap that investors debate today is about whether that difference is justified by future growth and profitability.
Ongoing expansion and network densification across key European markets, especially via M&A (Yodel, Sending) and rapid APM (locker) deployment including battery-powered units from Bloq.it, are allowing InPost to capture outsized parcel volume growth and extend its out-of-home leadership, supporting sustained double-digit revenue growth and operating leverage.
See why 26 investors see InPost as 13% undervalued.
Result: Fair Value of €17.89 (UNDERVALUED)
Still, the bullish InPost story can break if heavy investment and acquisition costs drag on cash generation, or if key e-commerce partners shift parcel volumes elsewhere.
Find out about the key risks to this InPost narrative.
Another View: What InPost’s Valuation Ratios Are Signalling
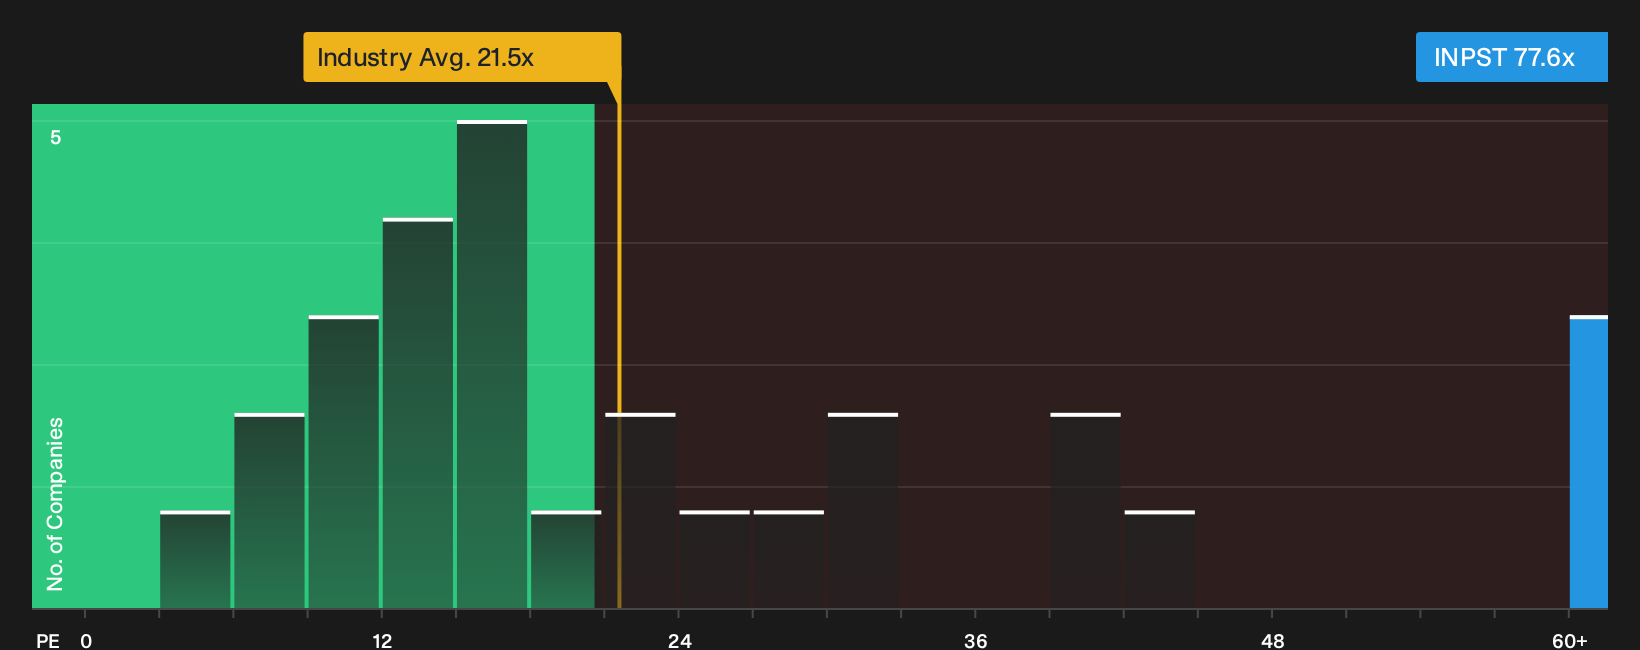
Analysts see InPost as about 13% undervalued at €15.60 versus a fair value of €17.89, yet the P/E ratio near 77.6x tells a different story. That is far above the estimated fair ratio of 39.7x, the European logistics average of 21.5x and the 12.6x peer group level, which lifts the risk that sentiment cools faster than earnings catch up.
To pressure test those earnings expectations against the current price, take a closer look at how the market is applying these ratios to InPost through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals across price, index status and valuation can feel messy. This is exactly why it helps to inspect the full picture yourself. Act quickly and weigh both the potential upside and the pressure points by checking the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond InPost?
If you stop with InPost, you risk missing other opportunities that fit your style, risk appetite and income needs across different corners of the market.
- Zero in on potential mispricings by scanning a curated pool of companies that screen as quality yet overlooked through the 188 high quality undervalued stocks.
- Lock in potential income ideas by reviewing a focused lineup of higher yielding payers using the 221 dividend fortresses.
- Dial back portfolio stress by filtering for businesses with sturdier finances via the 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com