


What Universal Music Group Investors Missed Before The Fall
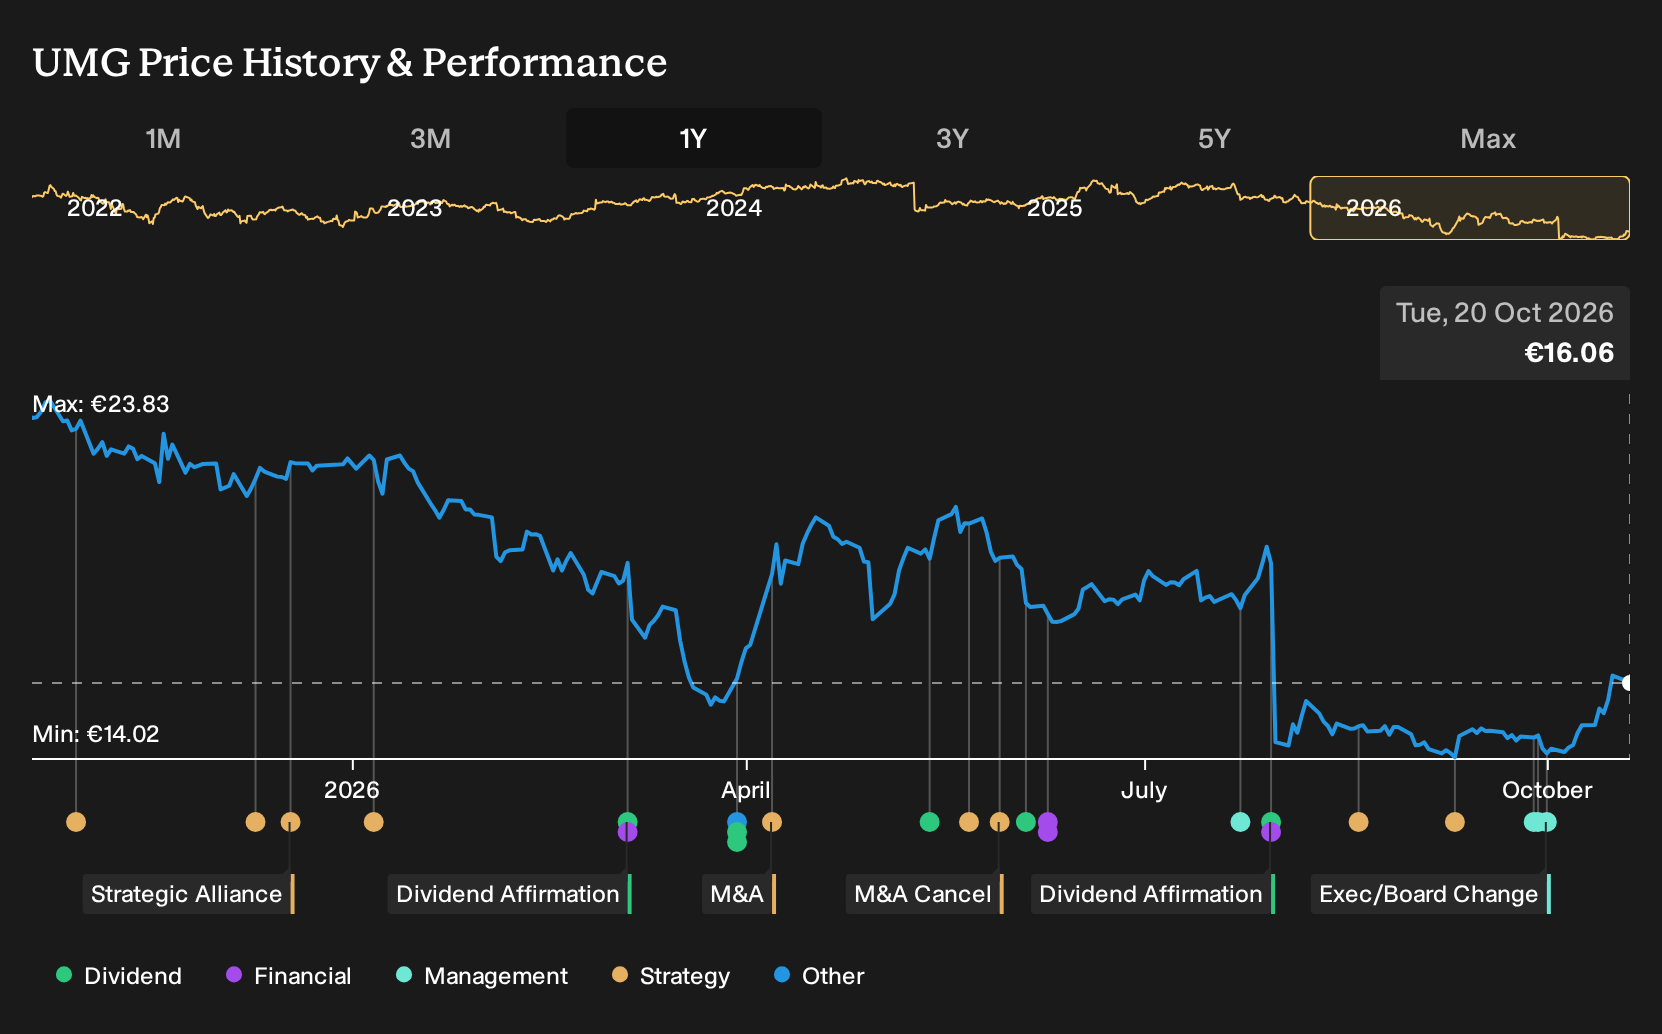
Universal Music Group highlighted paid streaming adoption, AI partnerships and cost savings, yet the most recent half year told a different story, with revenue higher while net income and margins compressed sharply. Investors who held Universal Music Group over the past year are down 29.1%, including dividends. If you had been weighing a position back in October 2025, what early cracks, if any, were visible before that drawdown showed up on your statement?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Universal Music Group. Zero in on 188 high quality undervalued stocks for companies trading below our estimates.
The Two Universal Music Group Stories Investors Were Weighing
The shares cost €23.34 at the start of the period, and Universal Music Group sat between two sharply different stories that both looked reasonable on the numbers.
On the optimistic side, the bull narrative put Fair Value at €29.32 and focused on paid streaming adoption alongside premium and superfan tiers. Streaming 2.0 deals and €250 million of planned cost savings were aimed at lifting margins over time despite pressure on profit rates.
The bear narrative pinned Fair Value at €22 and focused on AI generated music eroding catalog value. It assumed slower 4.7% revenue growth and margins shrinking toward 12.5% as superstar dependence and rising technology and marketing costs weighed on profitability.
What The Results Changed In The Universal Music Group Debate
Universal Music Group’s H1 2026 report gave the clearest signal. Total revenue moved from €5,881m in H1 2025 to €6,194m in H1 2026, which lined up with the bullish focus on paid streaming adoption. Net income excluding extra items went from €1,432m to €222m and the net margin shifted from 24.3% to 3.6%, which challenged the profitability part of that optimistic case. Overall, the evidence cut both ways.
The lesson is simple. When a story leans on margin expansion, do not just watch the top line. Track net income and net margin side by side, then ask whether new costs or payout decisions are quietly eating the earnings that the growth story assumes.
What Universal Music Group’s Current Price Already Assumes
Universal Music Group trades at €16.06 today, after a 29.1% loss over the past year. The selected Narrative sees Fair Value above that quote, based on the view that the catalog and core label economics justify a richer multiple than the market currently applies.
The key hinge is whether UMG’s large catalog and independent-services platform continue to behave like durable royalty assets rather than short-life hit making. A buyer today needs to believe execution issues stay temporary while those underlying economics hold up.
"UMG controls approximately 39.76% of U.S. catalogue consumption, versus 19.80% for Warner. Its Recorded Music operation is substantially larger. Its leverage is materially lower. Its Publishing franchise is larger. Its independent-services infrastructure has been materially expanded through Virgin Music Group and Downtown."
The price and this Narrative do not agree. → Uncover what this Narrative says Universal Music Group is actually worth
Where Universal Music Meets AI Demand
Universal Music Group keeps steering listeners toward paid streaming and tighter fandom. That strategy depends on platforms that can surface the right track instantly.
To make that experience work, another giant is investing heavily in search, video and AI tools. It is quietly building the digital pipes that help people find songs and creators.
Those same systems help businesses analyse data, run AI models and collaborate online.
Entertainment might be the hook, but enterprise workloads steadily deepen the need for these tools.
As fans and businesses spend more time inside those services, the parallel exposure to search, cloud and AI infrastructure becomes harder to ignore.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 27% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com