


How Investors Are Reacting To Axcelis Technologies (ACLS) Korea Factory Plan
- Axcelis Technologies has committed US$35 million to build an ion implantation equipment facility in Pyeongtaek, Korea, adding cleanrooms, warehousing, and a training center, with production targeted for the second half of 2028.
- This Korean plant points to a push for more diversified manufacturing and closer support for Asian chipmakers, which could reshape Axcelis Technologies' cost base and regional supply resilience over time.
- The focus now turns to how Axcelis Technologies' investment narrative could shift as this US$35 million Korean capacity build comes into view.
Scan 55 AI infrastructure stocks that could benefit as chip equipment suppliers like Axcelis Technologies build out capacity to support the next wave of semiconductor demand.
Axcelis Technologies Investment Narrative Recap
To own Axcelis Technologies, you need to be comfortable with a capital equipment story that depends on sustained demand for ion implantation in memory, power and compound semiconductors, along with an expanding services base. The Korean facility fits that picture as a long dated capacity add, with limited effect on the near term focus on orders, margins and cash generation.
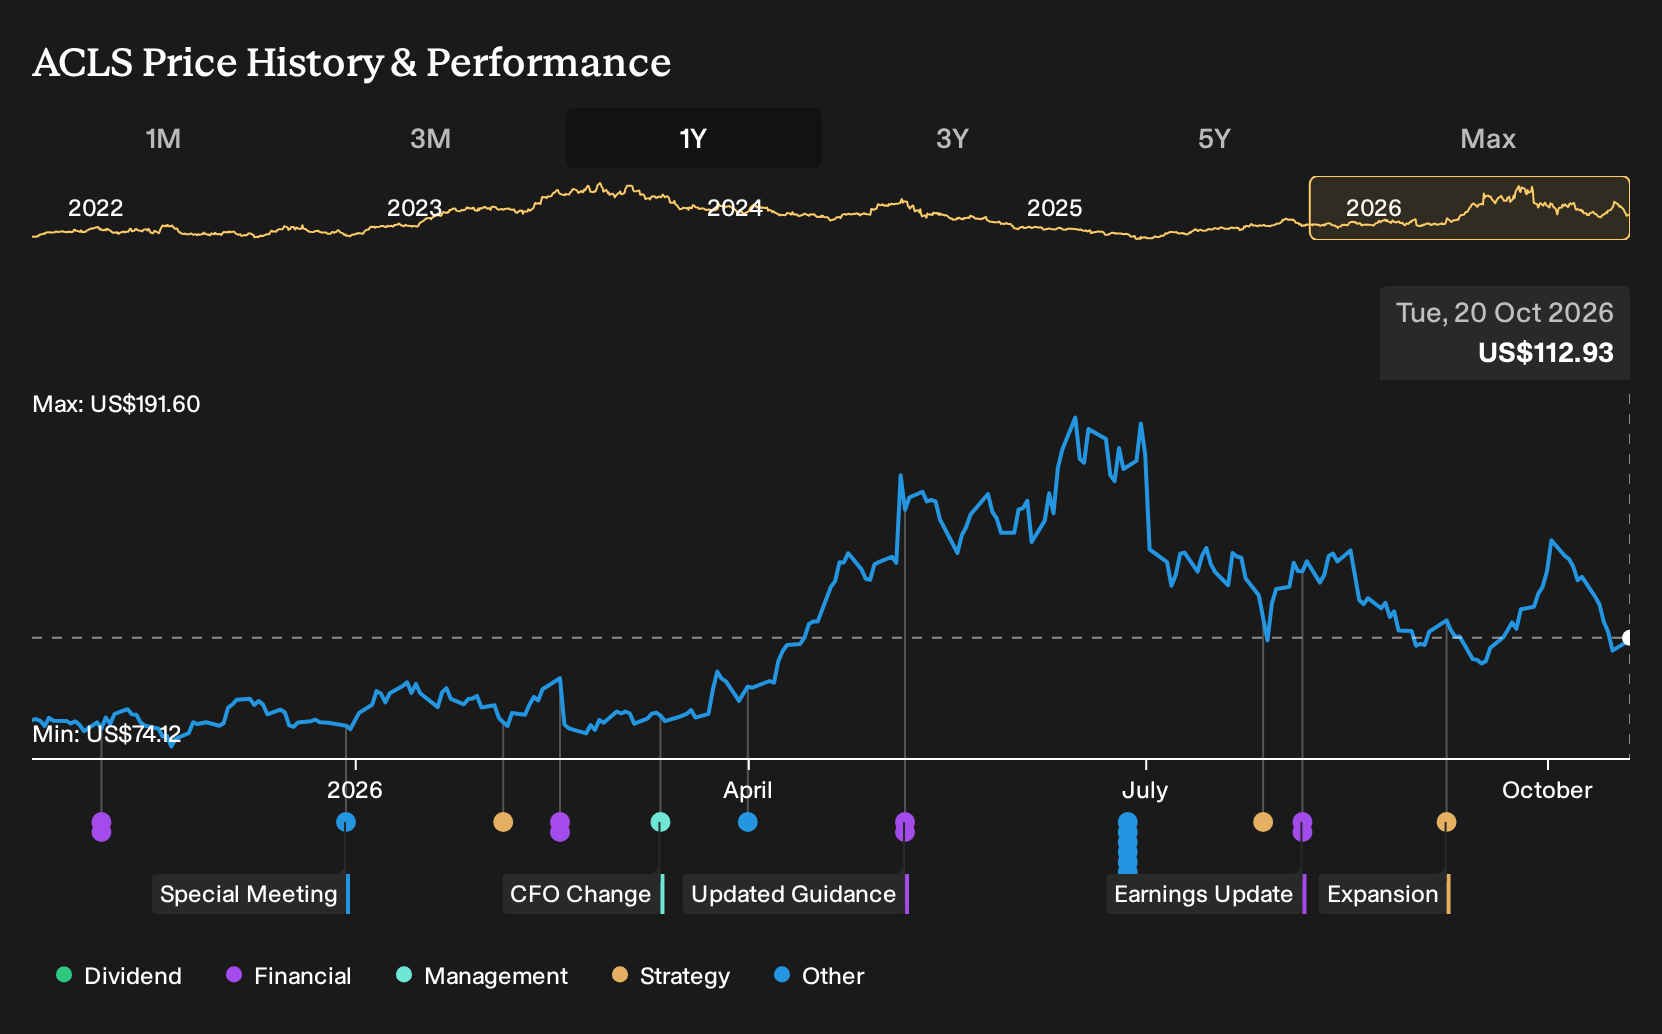
The bigger swing factor in the next couple of years still appears to be order momentum against heavy China exposure and mix sensitive gross margins that recently sat at 10.7%, down from 17.7%. The Korea build also introduces future fixed costs, which could amplify margin pressure if utilization disappoints once production starts.
The current update on the US$35 million Pyeongtaek build aligns most directly with the earlier push to widen Axcelis Technologies geographic footprint beyond China, which has been around 40% to 46% of revenue. A local manufacturing base in Korea could support that diversification effort by shortening lead times and tightening support for Asian fabs.
The facility is not expected to produce tools until the second half of 2028, so it does not change the shorter term catalysts tied to silicon carbide adoption, DRAM related bookings or CS&I growth. For now, the main operational question for readers is whether future demand justifies the extra capacity enough to protect margins and free cash flow once the plant is live.
Axcelis Technologies' current analyst script points to revenues of US$1.2b and earnings of US$202.7 million by 2029. That profile is based on an assumed 13.0% yearly rise in revenue and an earnings increase of roughly US$110 million from the US$92.8 million reported today.
Uncover why Axcelis Technologies' fair value indicates a 43% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Korea news against a different swing factor. They focus on AI linked DRAM and HBM demand, where their May 2026 models already assumed about 15.3% yearly revenue growth and earnings near US$256.5 million by 2029. You can compare that upbeat Axcelis Technologies view with your own expectations and evaluate how this new factory announcement might influence those scenarios.
Explore 4 other Axcelis Technologies fair value estimates, including one that suggests as much as 43% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Axcelis Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Axcelis Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axcelis Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Axcelis Technologies?
If the Axcelis Technologies story has you thinking about how to position your portfolio for the next phase of semiconductor and hardware demand, it can help to widen the lens and review other stocks with clear financial traits.
- For investors who want strong quality with a valuation that still looks reasonable, scan a curated 35 high quality undervalued stocks that match those filters.
- If reliability and balance sheet strength matter most to you, review a focused list of solid balance sheet and fundamentals (25 results) that can help anchor your watchlist.
- When you are hunting for future leaders before they are widely followed, work through a targeted 20 high quality undiscovered gems that share solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com