


Learn Why The Bull Case For Fast Retailing Stock Could Change Following Dividend Increase
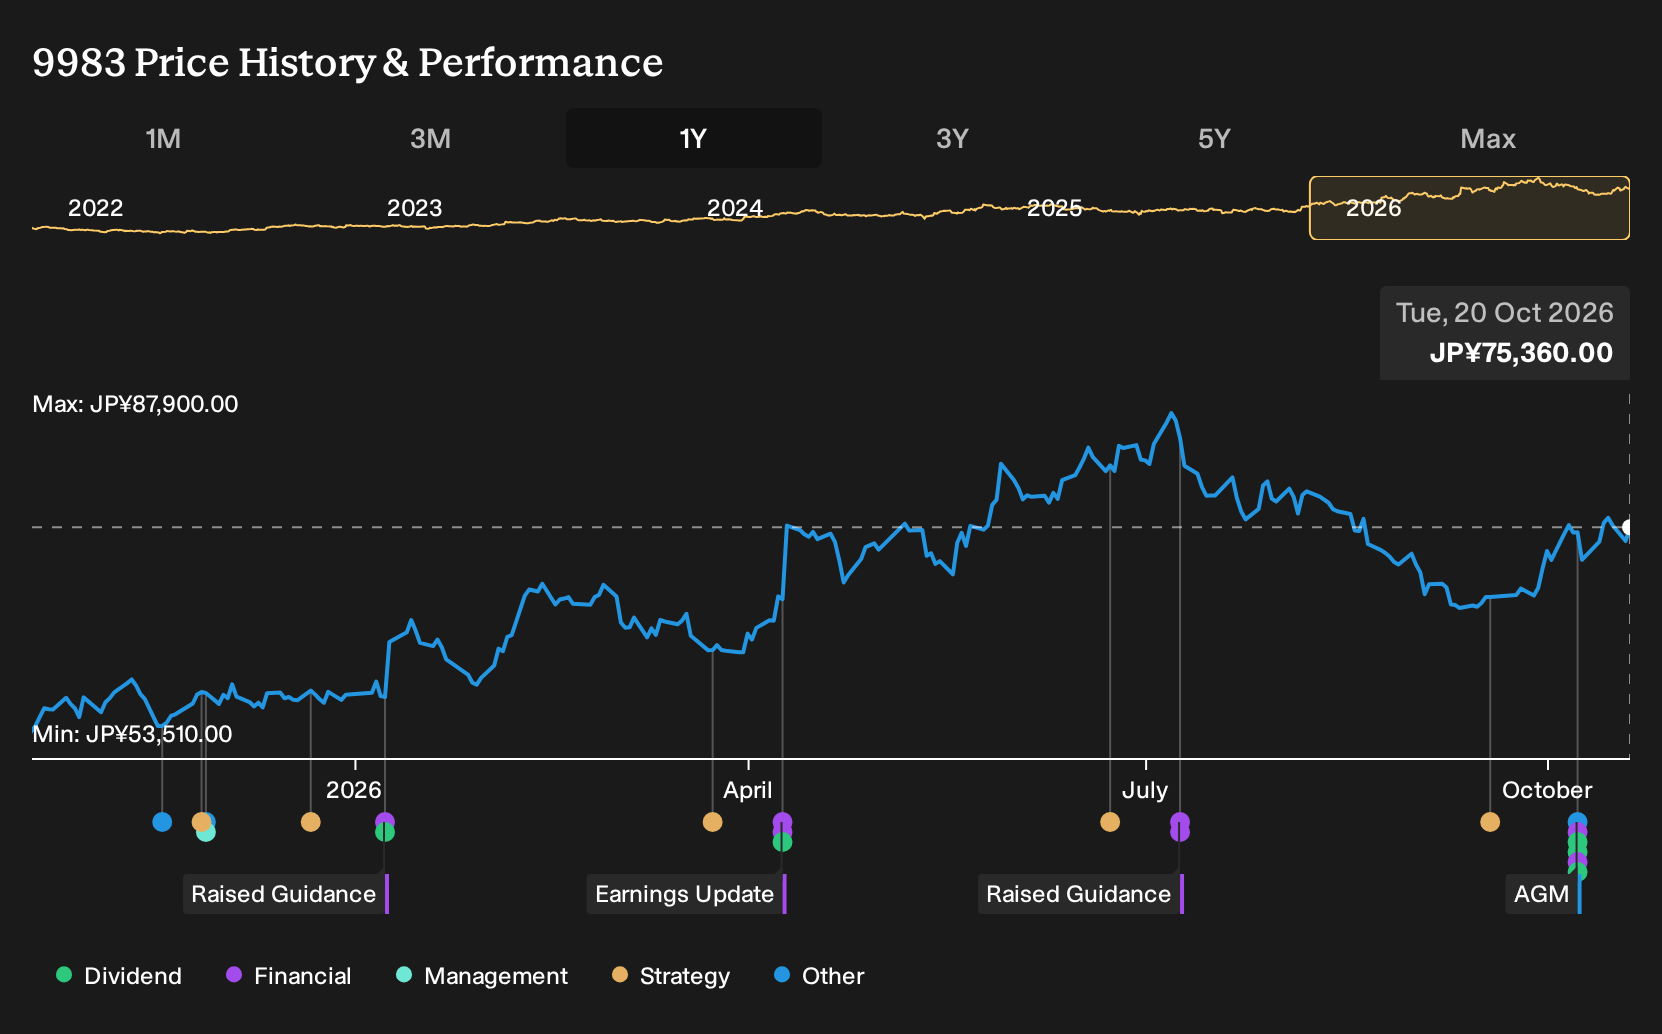
- Fast Retailing reported full year 2026 results with sales of JPY 3,963,389 million and net income of JPY 542,516 million, and lifted its year end 2026 dividend to JPY 530 per share, taking the full year payout estimate to JPY 850.
- Management described the higher dividend and revised payout as a response to stronger profitability and cash generation, while still emphasizing active investment in future growth pillars across the business.
- The focus now turns to how Fast Retailing's richer dividend profile, supported by recent earnings figures, could influence the broader investment narrative.
Compare Fast Retailing's richer payout with other income ideas, and scan a curated 29 dividend fortresses that could appeal if you are focused on cash returns from equities.
What Is Fast Retailing's Investment Narrative?
To own Fast Retailing, you need to believe this is a global apparel platform that can keep turning scale into steady cash generation, not just a Japan retailer with a one off earnings bump. The latest full year numbers, with revenue of ¥3,963.4b and profit of ¥542.5b, support that picture of broad based demand and solid execution across UNIQLO Japan, UNIQLO International and GU. Higher net margins and a richer dividend for 2026 show management is comfortable sharing more cash while still talking up investment in future growth pillars.
The twist is what happens next. Guidance for the year to August 2027 pairs higher earnings and revenue targets with a lower year end dividend of ¥450 per share versus the 2026 ¥530. That combination indicates management is treating the 2026 step up as partly a reset and partly a signal of balance sheet strength, but does not lock investors into a one way payout climb. In the short term, the key catalysts remain operational, including store productivity, pricing power in core basics and how much capital needs to go back into new markets and formats.
Even so, there is a more awkward tension running through the Fast Retailing story that centers on ...
There's only one way to know the right time to buy, sell or hold Fast Retailing. Head to Simply Wall St's company report for the latest analysis of Fast Retailing's Fair Value.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community span a wide band, from about ¥40,119 to roughly ¥86,481 per share, which shows how far opinions on Fast Retailing can stretch. You are weighing those pre news views against fresh dividend guidance and earnings targets, so it makes sense to review several contrasting takes.
Explore another Fast Retailing fair value estimate, including one that suggests as much as 15% potential upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fast Retailing research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fast Retailing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fast Retailing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fast Retailing?
If Fast Retailing has sharpened your focus on income, quality and valuation, it can help to line it up against a wider watchlist built from clear, rules based filters.
- For investors hunting for resilient cash generators with lower perceived risk, review the 21 resilient stocks with low risk scores that may help you concentrate on steadier profiles.
- If you want potential mispricings with solid fundamentals, scan a curated 13 high quality undervalued stocks that aims to surface candidates for deeper research.
- When the goal is to find under-followed opportunities, sort through a 73 high quality undiscovered gems that highlights companies with strong underlying metrics but limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com