


Q3 Results Could Be A Key Test For Somnigroup International Stock
- Somnigroup International, a bedding manufacturer and retailer, is set to report Q3 results on 9 November 2026. Investors expect these results to clarify how acquisitions and global expansion are influencing cash generation.
- A discounted cash flow model suggests that Somnigroup International is trading below an estimated intrinsic value. This focuses attention on how Mattress Firm integration may affect future cash inflows and overall valuation.
- We will now explore how Somnigroup International's investment narrative could shift as investors weigh upcoming Q3 results and acquisition integration.
Scan the bedding space beyond Somnigroup International by reviewing hand-picked sleep-focused businesses that also flag as value opportunities in our 35 high quality undervalued stocks.
Somnigroup International Investment Narrative Recap
To own Somnigroup International, you need to believe the bedding group can turn its broad brand portfolio and global reach into consistent cash generation, not just one-off acquisition gains. The near term hinge is Q3 on 9 November 2026, where investors are looking for proof that operations are bedding down and cash flows are keeping pace with the bigger footprint.
The biggest swing factor right now is the Mattress Firm integration. Smooth execution keeps the focus on cost savings, store productivity and omnichannel gains. Any signs of strain, such as weaker store economics or pressure from higher input costs, would push attention back to Somnigroup International's leverage and its exposure to North American demand.
Among recent developments, the clearest operational focal point is management's emphasis on cost and sales synergies from Mattress Firm, with US$100 million in annual net cost benefits projected and sales cross over viewed as ahead of schedule. That is exactly what upcoming Q3 numbers can either corroborate or call into question, especially for investors leaning on discounted cash flow analysis.
If Somnigroup International shows those Mattress Firm efficiencies flowing through to margins and cash generation, it reinforces the current narrative of growing earnings, which analysts forecast at 19.64% per year, while the stock trades below some intrinsic value estimates. If the integration proves slower or more expensive, the debt load and reliance on acquisitions for growth become more prominent in the risk column.
Somnigroup International's current narrative anchors to analyst expectations that revenues reach US$12.2b and earnings hit US$1.1b by 2029, based on earnings today of US$533.3m. That profile implies 16.9% yearly revenue growth and an earnings increase of about US$566.7m from current levels.
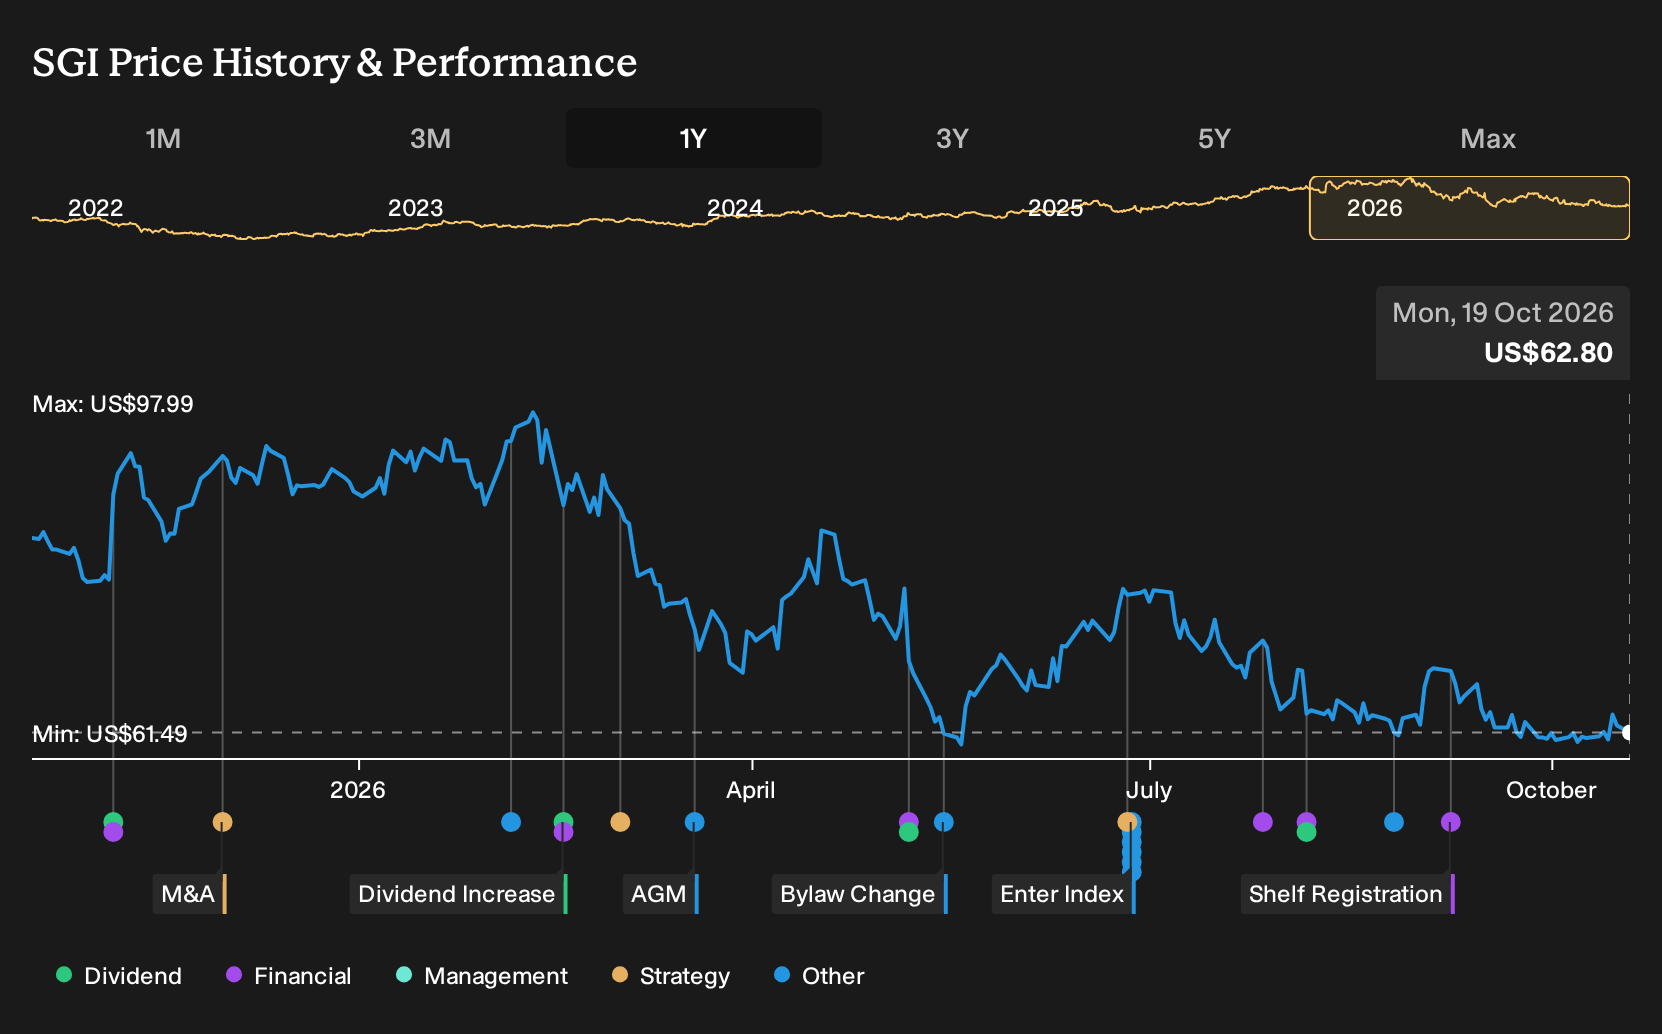
Discover why Somnigroup International's fair value indicates a 49% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
You might see Somnigroup International very differently if you focus on execution risk rather than Mattress Firm synergies. The lowest analysts were already cautious before Q3, pencilling in about US$12.4b of revenue and US$1.1b of earnings by 2029, while assuming only a 19.5x P/E. Their view shows how sharply opinions can diverge, so consider several narratives before deciding what this Q3 update could mean for you.
Explore another Somnigroup International fair value estimate, including one that suggests it could be worth just $93.44!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Somnigroup International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Somnigroup International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Somnigroup International's overall financial health at a glance.
Looking for more Somnigroup International investment ideas?
Somnigroup International may be your starting point, but your portfolio benefits when you compare it with other businesses that fit clear, disciplined criteria. Use the Simply Wall St Screener to surface companies that match the kind of risk, income, or balance sheet profile you want to focus on next.
- For investors who want income to play a bigger role in returns, check out 8 dividend fortresses that have historically offered higher yields.
- If capital preservation and steadier profiles matter most to you, filter for 32 resilient stocks with low risk scores and see which businesses line up with your comfort zone.
- When you are hunting for underappreciated opportunities with solid fundamentals, start with a curated 20 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com