


What Thermo Fisher Scientific Doubters Missed
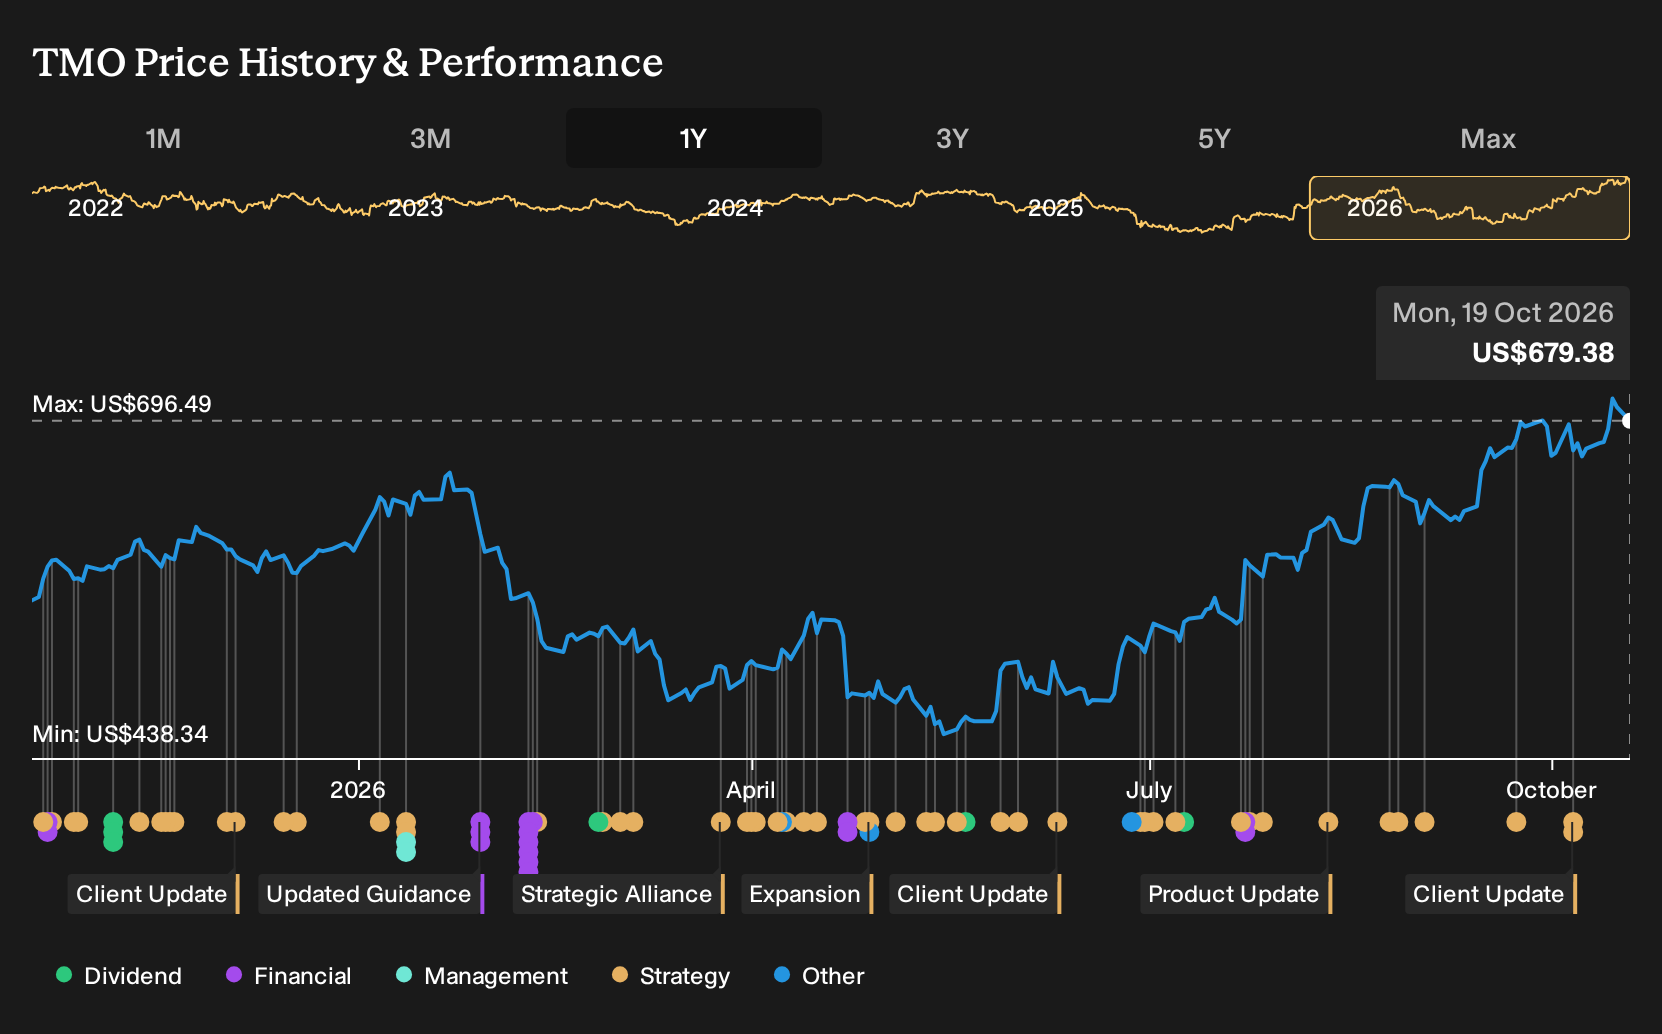
If you only skimmed the headlines about Thermo Fisher Scientific this year, the story looked choppy. Q1 2026 beat expectations yet still triggered a selloff, then Q2 results and an upbeat Investor Day reset the mood. Holding Thermo Fisher Scientific over the past year would have returned 25.4%, including dividends. If you had bought on 2025-10-19 with only those mixed early views, what exactly in the record justified taking that ride?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Thermo Fisher Scientific has already moved. Pinpoint other ways to investigate the theme among 33 healthcare AI stocks.
The Argument You Would Have Been Weighing Up On Thermo Fisher Scientific
The shares cost US$539 at the start of the period, so any decision on Thermo Fisher Scientific began with what investors thought that price already implied.
The bullish narrative saw fair value at US$767, 42% above the start price, assuming aging populations and gene therapies would support precision medicine demand across bioprocessing, diagnostics, and services.
The bearish view put fair value at US$450, 16% below the start price, focusing on US China trade restrictions as a risk to global supply chains and long term margins.
What The Results Changed For The Thermo Fisher Scientific Debate
Thermo Fisher Scientific’s Q2 2026 report showed revenue at US$11.99b and net income at US$1.74b, both above Q2 2025 levels, which leaned toward the bullish view that demand for its tools and services would keep growing. Net margin slipped from 14.9% to 14.5%, and mixed analyst commentary on growth tempered that optimism. Overall, the evidence cut both ways.
The hinge assumption here was not just growth, but profitable growth. For a different stock, track whether rising revenue and earnings come with stable or improving net margin instead of assuming higher sales alone validate an upbeat thesis.
What Thermo Fisher Scientific's Price Already Assumes
Thermo Fisher Scientific now trades at US$679 after a 25.4% gain over the past year. The selected Narrative’s Fair Value sits below that level, even while acknowledging recent business progress and analyst optimism.
The Narrative focuses on questions about organic growth and margin resilience. A buyer today effectively assumes recent strength can persist despite geopolitical, pricing, and acquisition risks flagged in that assessment.
"Heightened geopolitical tensions, cost control measures, and changing industry dynamics are likely to pressure margins and limit meaningful global growth for Thermo Fisher. Heavy reliance on acquisitions and exposure to disruptive technologies present ongoing risks to revenue stability and the firm's long-term market leadership."
One Narrative disagrees with today's price. → See where this Narrative says Thermo Fisher Scientific should trade
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 50% below our estimate - builds a digital-first small business bank where core lending and deposits scale together efficiently.
- Company 2 - 49% below our estimate - supplies steel reinforcement that tracks infrastructure funding into highways, streets and large concrete projects.
- Company 3 - 39% below our estimate - connects large merchants to local payment methods as transaction volumes spread across more channels.
Those are three of them. See the full list of 35 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com