


What Welltower Doubters Missed
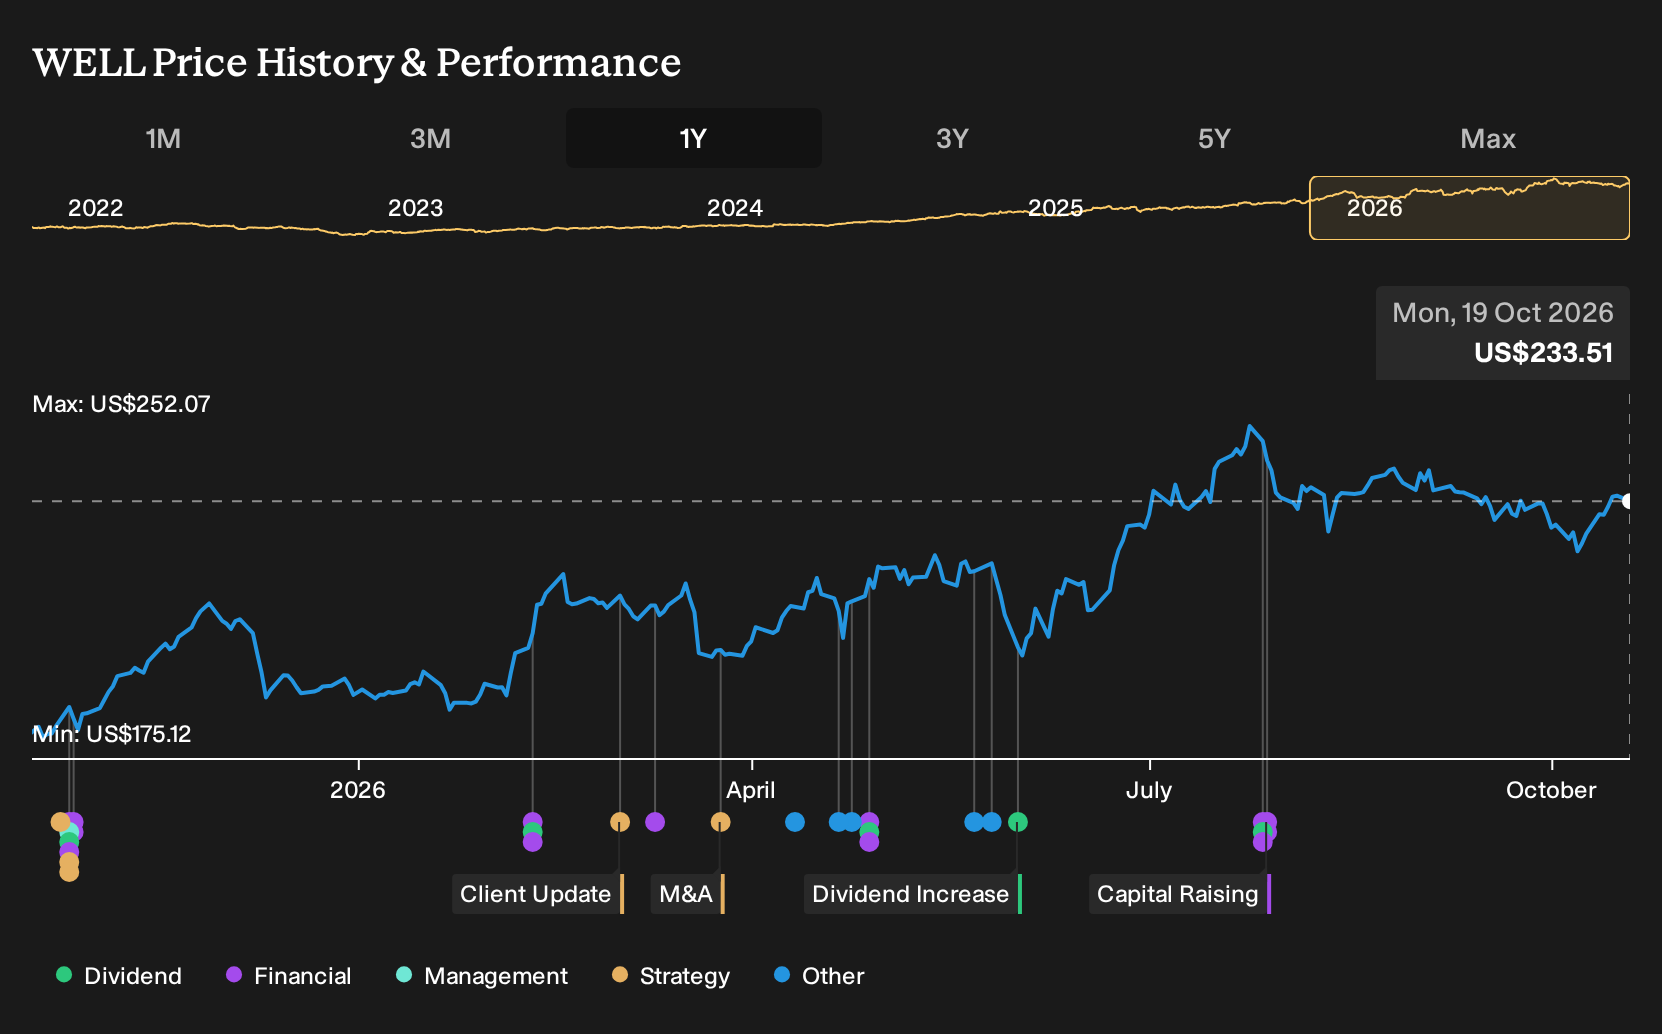
If one development captured how ambitious Welltower became over the period, it was the launch of external licensing for its data science platform, turning internal analytics into a fee-based service. Investors who held Welltower over the past year are up 33.3%, including dividends. If you had been deciding on 19 October 2025 whether to buy, what conviction about acquisitions, fund management, and senior housing demand would you have needed before that news ever hit the tape?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Welltower is not the only name tied to this theme. Zero in on 10 top silver producer stocks and compare how each one is priced.
The Two Stories Investors Were Weighing On Welltower
The shares cost US$175 at the start of the period, so anyone looking at Welltower then had to decide which story felt more reasonable.
The bullish narrative pinned fair value at US$185 and leaned on private fund management plus acquisitions to lift efficiency. It rested on assumptions of 16.4% revenue growth, a 14.5% profit margin and a future P/E of 87.8x over a 3 year window.
The bearish view set fair value at US$145 and focused on pressure from macro risks and leverage. It flagged that rapid acquisitions might strain resources and that tighter credit conditions could hurt occupancy, revenue and net margins.
What The Results Changed For The Welltower Thesis
The launch of external licensing for Welltower’s data platform and record senior housing NOI growth gave the bullish story fresh support, because both relied on operations plus acquisitions doing more with the same real estate. Reported revenue reached US$3.54b in Q2 2026 versus US$2.55b a year earlier, profit rose, and net margin moved from 11.8% to 12.6%, so the cautious view on margin pressure was not settled. The evidence cut both ways.
The useful lesson is simple. When a REIT like Welltower leans on acquisitions and fund management, you judge it by whether revenue, net income and margin all move in the same direction. Apply the same test elsewhere by tracking those three lines whenever management talks about efficiency and platform returns.
What You Are Paying For In Welltower Today
Welltower now trades at US$234 after a 33.3% gain over the past year, and the selected Narrative’s Fair Value sits above that level. The argument focuses on senior housing occupancy catching up, fee income growing from data and fund platforms, and leverage staying contained.
Any buyer today has to judge whether Welltower can continue rotating into higher growth senior housing assets while holding leverage near 3x and scaling its platforms without diluting returns. The business assumption that would need to hold is that this mix shift and fee growth keep earnings power compounding.
"Bullish analysts expect Welltower to keep compounding earnings power as affluent senior demand, tight new supply, and the operations focused platform support high occupancy, healthy rate growth, and solid SHOP margins. The main requirement is that Welltower continues to execute on rotating into higher growth senior housing assets while maintaining disciplined leverage around 3x and scaling its technology and fund management platforms without eroding returns."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Welltower’s Walls
Welltower highlights how senior care shifts closer to everyday neighborhoods and routines.
The same aging forces strain earlier links in the healthcare chain, before hospital doors.
Another landlord concentrates on modern community clinics, not big inpatient wings far away.
It provides up to date primary care properties that doctors and health services can use, backed by long leases and government payment streams.
If that migration continues, real estate tied to routine checkups could rival the importance of buildings where patients ultimately arrive when something goes very wrong.
That argument has a Narrative and a number behind it. → See the company one Narrative values 27% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com