


AutoZone (AZO) Could Be 10% Undervalued On Conflicting Fair Value Views
Board Change Sparks Fresh Look at AutoZone Stock
AutoZone (AZO) is back in focus after board member Claire R. McDonough told the company on October 6 that she will not seek reelection at the 2026 Annual Meeting.
Her decision follows acceptance of a new executive role elsewhere. That employer’s key events calendar clashes with several future AutoZone board meetings and is prompting investors to reassess how this governance shift fits into the wider AZO story.
AutoZone shares trade at US$3,097.88 and have climbed 8.5% on a 1 month share price basis and 2.8% over 3 months, even as the year to date share price return is down 6.2% and the 1 year total shareholder return has fallen 21.9%. This is set against a 5 year total shareholder return of 70.1%, where momentum looks more uneven than the longer record suggests.
Scan how board stability and governance quality stack up across other retailers with the list of solid balance sheet and fundamentals (25 results) that filters for financial resilience alongside management depth.
Bulls see AutoZone’s recent pullback and board change as a chance to buy a resilient operator, while bears read it as a warning. Which side does current valuation lean toward next?
Most Popular Narrative: 9.5% Overvalued
AutoZone last closed at $3,097.88 while the most followed narrative pegs fair value nearer to $2,829.08, so the gap between price and story has widened and puts extra weight on how recent results are being interpreted.
None of that held. Total operating expenses grew 8.9% this quarter, SG&A deleveraged 101 basis points, and per-store SG&A growth went straight back to 4%, precisely the direction the prior commentary said would not happen. Management’s explanation this time was that the deleverage was “driven primarily by our growth initiatives,” the same initiatives that were supposed to be moderating.
See why 1 investors see AutoZone as 10% overvalued.
Result: Fair Value of $2,829.08 (OVERVALUED)
Still, the AutoZone narrative could shift quickly if DIY traffic keeps weakening or SG&A growth stays elevated, since both directly pressure the current fair value story.
Find out about the key risks to this AutoZone narrative.
Another View: AutoZone Through a Cash Flow Lens
While the most popular AutoZone narrative leans on a fair value of $2,829.08 and labels the stock as overvalued, the SWS DCF model points the other way. On that framework, AZO at $3,097.88 trades around 10.1% below an estimated cash flow value of $3,446.72. Which story do you trust when the market forces you to pick a side?
Look into how the SWS DCF model arrives at its fair value.
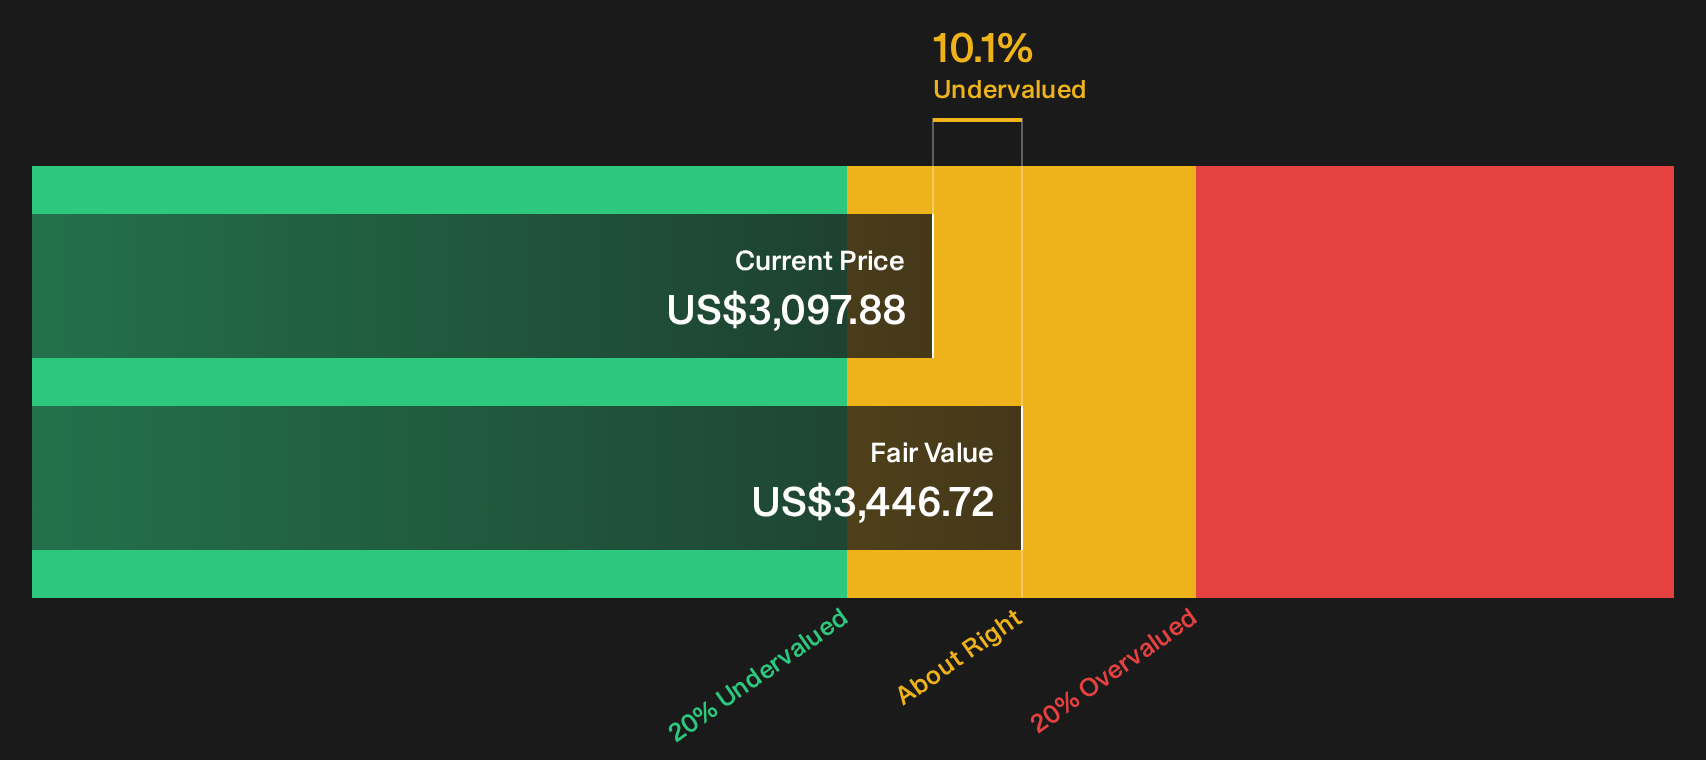
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AutoZone for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around AutoZone can be confusing, so move fast, pull up the numbers, and weigh both the caution and the upside. To see the full balance of risks and potential rewards that investors are focused on right now, start with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond AutoZone?
AutoZone gives you one angle on the market, but your next strong move often comes from widening the lens with fresh stock ideas powered by data.
- Target higher quality opportunities by scanning companies that look undervalued on both earnings and balance sheet strength through the 35 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses with payout strength using the 8 dividend fortresses.
- Reduce portfolio stress by concentrating on sturdier financial profiles and robust fundamentals through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com