


What Zensar Technologies Investors Missed Before The Fall
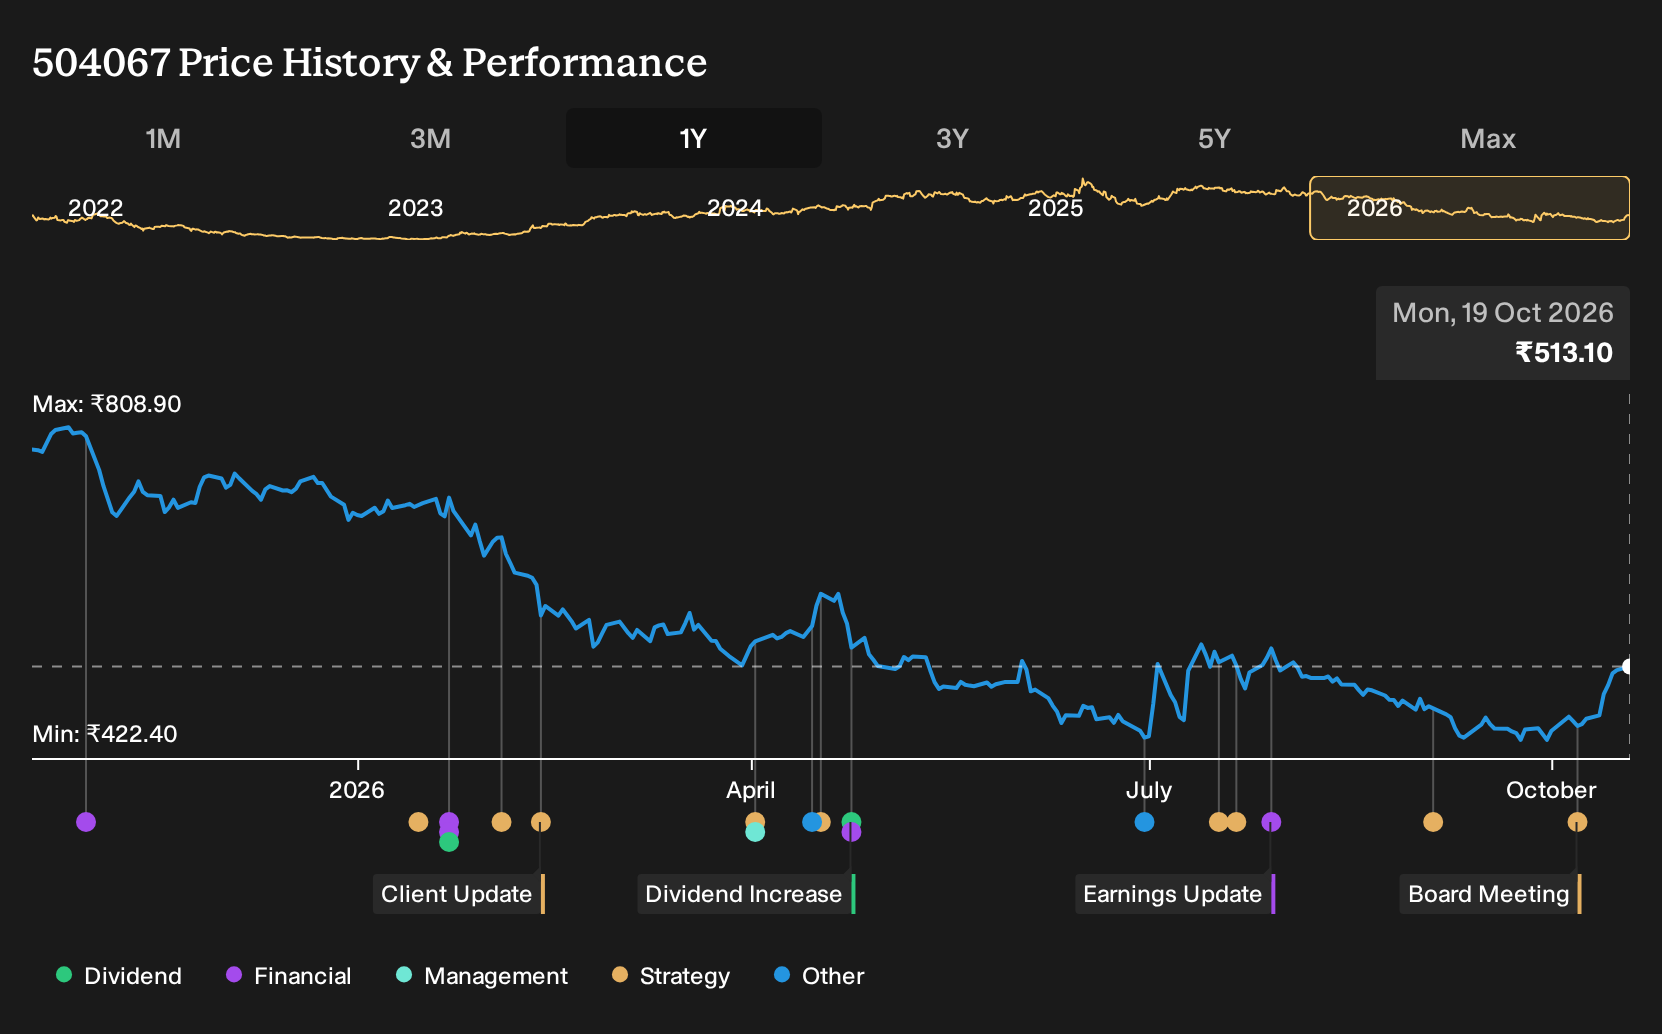
If you had backed the bullish July 2025 case for Zensar Technologies, expecting AI accelerators, longer contracts, and a strong cash pile to support higher earnings multiples, the result was painful. Holding Zensar Technologies over the past year would have meant a 32.4% loss, including dividends. If that decision date was 19 October 2025, what did those original assumptions miss about AI driven productivity, client concentration, or deal pricing that could explain such a gap?
The easy part of this move is behind Zensar Technologies. Zero in on 199 high quality undervalued stocks for companies trading below our estimates.
The Two Zensar Technologies Stories Investors Had To Weigh
The shares cost ₹783 at the start of the period, and anyone looking at Zensar Technologies then had to choose between two sharply different stories.
The bullish narrative pointed to a Fair Value of ₹1,130, a price implied by assumptions of 13.0% annual revenue growth and profit margins rising from 12.5% to 13.6%, helped by ZenAI accelerators, mandatory GenAI training, and a cash pile seen as fuel for large deals.
The bearish view argued for a Fair Value of ₹599, built on 10.0% yearly revenue growth, only a slight margin lift to 12.6%, and pressure from client concentration, heavier salary costs, and tougher AI competition.
What The Results Changed For Zensar Technologies
The clearest datapoint was the Q1 2027 print. Zensar Technologies reported revenue of ₹15,083m and net income of ₹1,838m, up from ₹13,850m and ₹1,820m a year earlier, yet net margin slipped from 13.1% to 12.2%. That combination supported the cautious case on profitability even as it gave the bullish growth story some backing.
The lesson is simple. When a thesis leans on margin expansion, do not just watch revenue and profit. Track net margin quarter by quarter and test whether claims about efficiency and pricing are reflected in that measure.
What You Would Be Paying For In Zensar Technologies Today
Zensar Technologies now trades at ₹513 after a 32.4% loss over the past year. The selected Narrative argues its Fair Value sits above the current price, built on AI embedded delivery, a record large deal pipeline, and meaningful cash on hand.
The key assumption a buyer must judge is whether Zensar can execute the mega deal and broader large contracts while protecting margins through AI driven productivity and offshore delivery.
"Bullish analysts expect Zensar Technologies to turn its broad AI upskilling and AI agent platforms into a larger stream of AI-native transformation work, supported by a record order book that already includes a single mega deal of about US$210m. The main thing that has to go right is that Zensar successfully executes on the mega deal and the wider large-deal pipeline, while keeping margins supported through offshore delivery, AI-enabled productivity gains and low voluntary attrition."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
One Step Beyond Zensar
Zensar Technologies leans on AI delivery and large contracts. Your next question might be what quietly keeps all that digital activity running.
Behind the scenes, someone must handle heavy data traffic and complex connectivity. The work includes moving information quickly, linking machines, and keeping systems reliable.
A different business spends its energy on that plumbing. It builds components and software that help process, route, and secure vast data flows.
The same AI push that pressures Zensar’s margins can increase infrastructure demands. As digital workloads compound, that quieter role could become even more important.
Could this be another way into the opportunity? → Explore the AI infrastructure opportunity and its 49% discount to one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com